


Levi Strauss shares have climbed to US$24.39, and after a strong multi year run the question now is whether that price still lines up with what the company earns.
- Over the past 3 years the stock has returned 77.0%, which puts a lot of weight on the idea that Levi Strauss' earnings can support this higher level.
- Recent reports of stronger international revenue and improved operating margins suggest that investors are paying close attention to how overseas expansion may support profit growth and cash generation over time.
- The analysts covering Levi Strauss have run their own numbers. See what analysts think Levi Strauss's shares could be worth.
The stock's next move may depend on whether Levi Strauss' current earnings are enough to justify the price investors are paying today.
If you are weighing Levi Strauss against other earnings driven stories, it can help to scan a wider field of companies through the 35 high quality undervalued stocks
Does Levi Strauss Look Undervalued on Earnings?
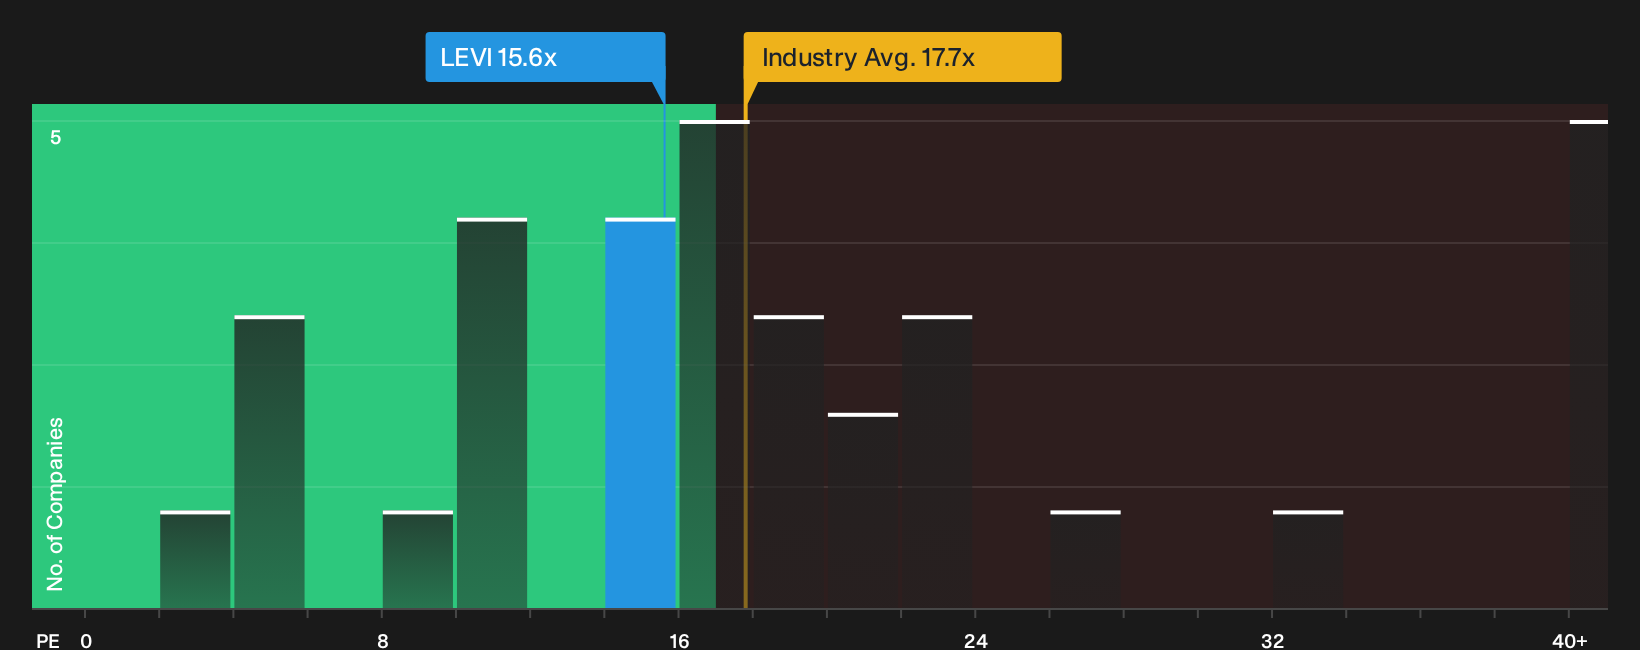
The P/E lens suits Levi Strauss because earnings are a key anchor for how investors currently frame this apparel stock. At a P/E of 15.6x, Levi Strauss trades below the Luxury industry average of 17.7x and also below the peer group on roughly 23.6x. This points to a more cautious price tag relative to other branded fashion businesses that investors follow.
Because the current P/E sits under the level suggested by a more tailored fair multiple that takes account of the firm's growth profile, profitability, size and risk, the shares screen as undervalued on this earnings yardstick. Recent headlines around stronger international business and improved operating margins mean sentiment has warmed. Yet the present P/E still reflects a markdown against peers and that fair value anchor, which is worth weighing if you see Levi Strauss as an ongoing earnings story. Explore the numbers behind Levi Strauss's P/E valuation.
The Levi Strauss Narrative: What Would Justify Today's Price?
Levi Strauss Narratives on Simply Wall St take the valuation puzzle a step further by spelling out which paths for growth, margins and earnings would need to play out for the stock to be worth meaningfully more or meaningfully less than the current share price, and they sit on the Community page for the company. Rather than relying on a single multiple or model line, each narrative lays out its own set of assumptions so you can compare those expectations with the actual numbers as they come through.
Views on Levi Strauss now split between a premium denim and DTC expansion story and concern that execution missteps are starting to bite.
Bull case: 11% undervalued
According to the analyst consensus Narrative on Simply Wall St, the upside hinges on mix shift and execution improvements paying off.
"The main thing that has to go right is that Levi Strauss continues to grow higher margin DTC, women’s and international mix while executing its supply chain, ERP and AI investments..."
Discover why this Narrative puts Levi Strauss at 11% undervalued.
Bear case: 30% overvalued
LunaRodas, a Simply Wall St Community investor who wrote the Narrative, argues that recent wording and execution raise sharper questions.
"Direct-to-consumer growth stalled to 2%, comp sales went flat, and a distribution overhaul management had promised would already be delivering savings instead absorbed a fire and arrived late..."
Explore why this Narrative puts Levi Strauss at 30% overvalued.
One more piece of the Levi Strauss puzzle to check
Before you lean too hard on the valuation work, it helps to ask who is steering Levi Strauss, how their interests line up with yours, and what incentives really drive their decisions. See who runs Levi Strauss and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com