


- Nordson’s EFD business has launched the PICO Pµlse XP HV jetting system, an automation ready valve designed for precise, high speed dispensing of thick silicones, greases and UV cure adhesives, fully compatible with the PICO Nexµs controller for Smart Factory integration.
- The PICO Pµlse XP HV system points to Nordson’s push toward higher value dispensing solutions that support demanding semiconductor, electronics and medical assembly workflows, where factors such as accuracy, uptime and repeatable dosing directly influence customer production economics.
- We will now explore how Nordson’s high viscosity PICO Pµlse XP HV launch interacts with the existing investment narrative around advanced technology demand.
Scan other automation focused plays that could benefit from similar high precision dispensing trends by running Nordson alongside our curated 91 robotics and automation stocks in your research today.
Nordson Investment Narrative Recap
To own Nordson, you need to believe the shift toward higher value dispensing and testing gear for semiconductor, electronics and medical customers can keep supporting earnings quality and cash generation. The analyst consensus Narrative on Simply Wall St leans on that mix shift plus frameworks like NBS Next. The PICO Pµlse XP HV launch fits this story but does not change it in a material way by itself.
In the short term, the key swing factor is execution in Advanced Technology Solutions, which posted 31% organic sales growth in Q3 FY2026. The main risk is that expectations stay high while Nordson carries meaningful debt and trades on a premium P/E, so any slowdown or order pushouts could hit sentiment quickly.
Among recent developments, the Q3 FY2026 update remains the most relevant backdrop for this PICO Pµlse XP HV news. Management reported free cash flow of US$237 million and a leverage ratio of 1.7x, alongside a US$1.2b commercial paper program. That combination gives Nordson room to keep funding new systems and Smart Factory capable platforms.
For you as an investor, the link between products like the new jetting system and those Q3 disclosures is about follow through. Analysts expect earnings to grow about 11.3% per year and margins around 32%, supported by a larger recurring aftermarket base. The opportunity and the risk both sit in whether Nordson keeps turning this type of equipment launch into durable orders across semiconductor, electronics and medical assembly lines.
Nordson's narrative projects US$3.7b revenue and US$805.7m earnings by 2029, based on analyst estimates. This is based on an assumption of 7.8% yearly revenue growth and an earnings increase of about US$250.5m from US$555.2m today.
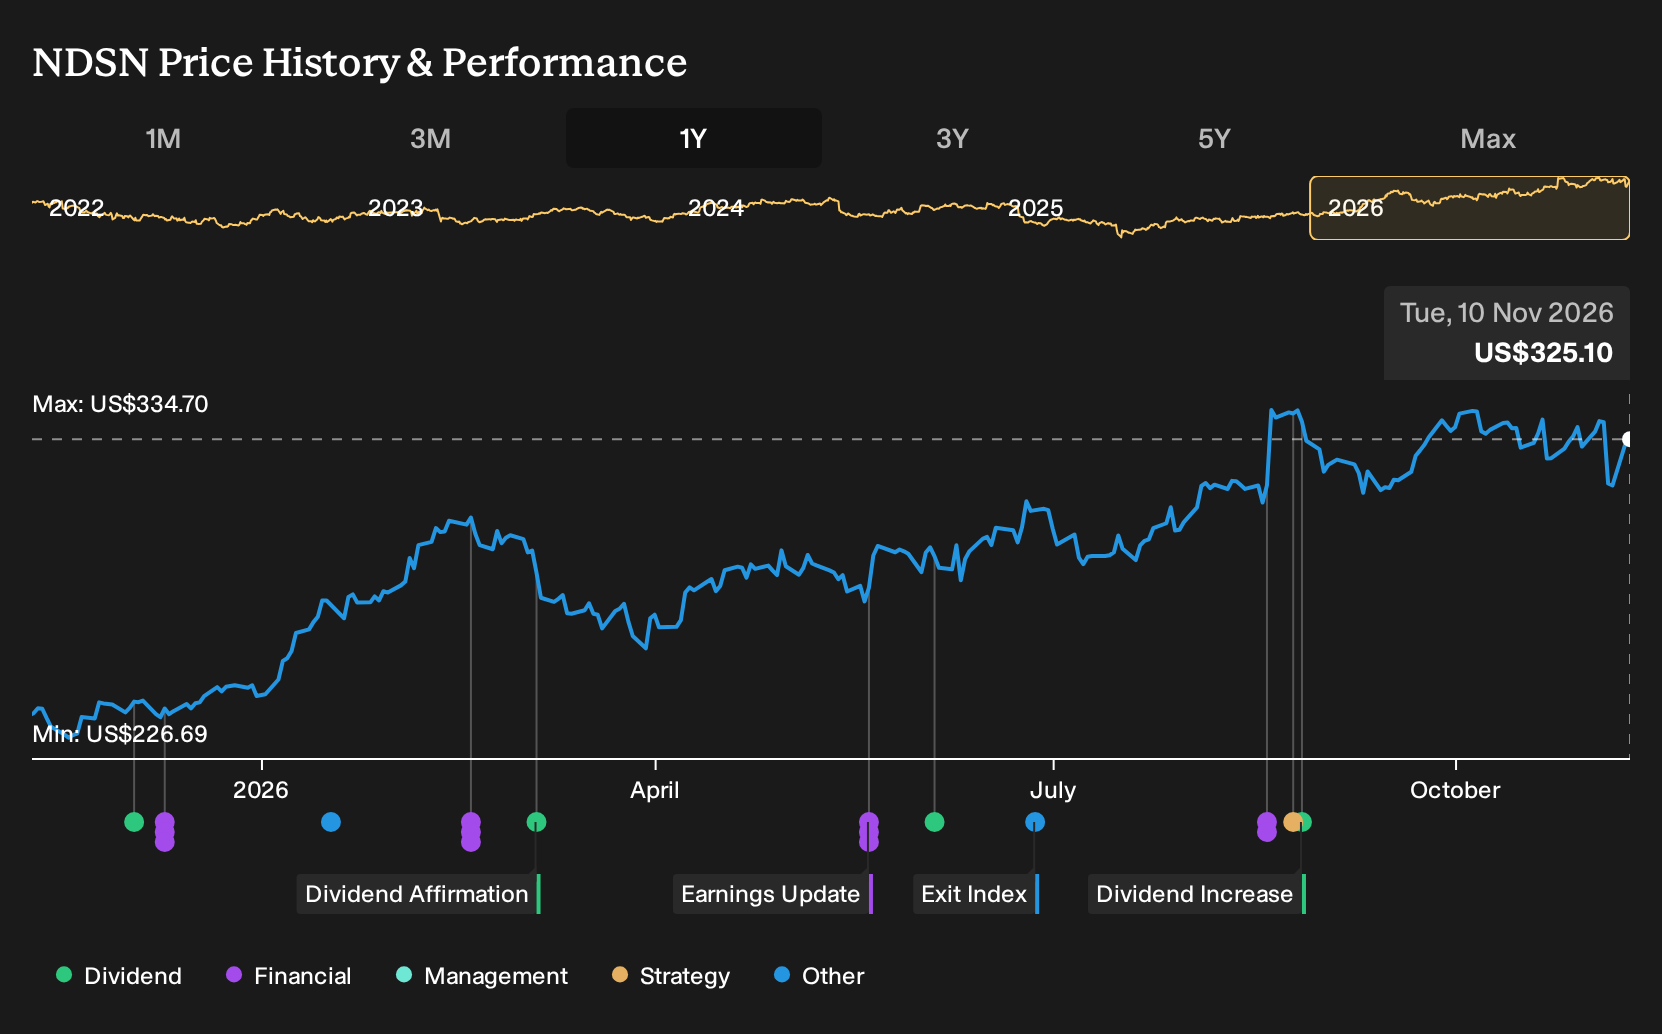
Uncover why Nordson's fair value indicates an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view around Nordson focuses on the risk that Advanced Technology Solutions growth could normalize from record 2026 levels. The most cautious analysts were modeling about US$3.6b revenue and US$781.4m earnings by 2029 before this jetting news, so their narrative is already cooler. Use that gap to explore how new products might reshape expectations.
Explore another Nordson fair value estimate, including one that suggests as much as 7% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Nordson research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nordson. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nordson's overall financial health at a glance.
Looking for more Nordson style investment ideas?
If the Nordson story has sharpened your thinking about quality, cash generation and balance sheet strength, broaden that same lens across other companies using the Simply Wall St Screener. You can build a watchlist that lines up with your risk tolerance and income needs instead of relying on a single stock.
- For investors who care most about resilient business models and steadier return profiles, scan a 30 resilient stocks with low risk scores that already score well on our risk checks.
- If capital preservation and financial strength sit at the top of your checklist, focus your research on a list of solid balance sheet and fundamentals (24 results) and fundamentals to see which companies meet your quality bar.
- Those hunting for mispriced opportunities can start with a 35 high quality undervalued stocks that combine strong fundamentals with potentially attractive valuations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com