


- Assurant reported third quarter 2026 revenue of US$3,529.5 million and net income of US$275.2 million, with diluted EPS from continuing operations of US$5.49, alongside ongoing share repurchases under its existing buyback plan.
- The combination of higher year to date revenue and earnings versus 2025 and the completed repurchase of 2.5% of shares highlights how Assurant is using both operating performance and capital returns to shape its financial profile.
- The focus now turns to how Assurant's stronger earnings per share from continuing operations influences the existing investment narrative built around fee based protection.
Scan how Assurant’s earnings and buybacks compare to peers by jumping into our hand picked list of 35 high quality undervalued stocks.
Assurant Investment Narrative Recap
To own Assurant, an investor needs to be comfortable with a fee based protection model that relies on Global Lifestyle and Housing to convert partnerships into recurring earnings. The analyst consensus Narrative on Simply Wall St points to that mix as the core thesis. The latest quarter, with higher year to date revenue and net income versus 2025, supports that operational story rather than changing it.
In the shorter term, the key swing factor still appears to be execution in connected devices and housing, where AI and automation investments aim to keep expense ratios in check. The biggest risk remains concentration in lender placed insurance, where any tighter regulation or fee pressure could weigh on Global Housing margins even if group earnings hold up.
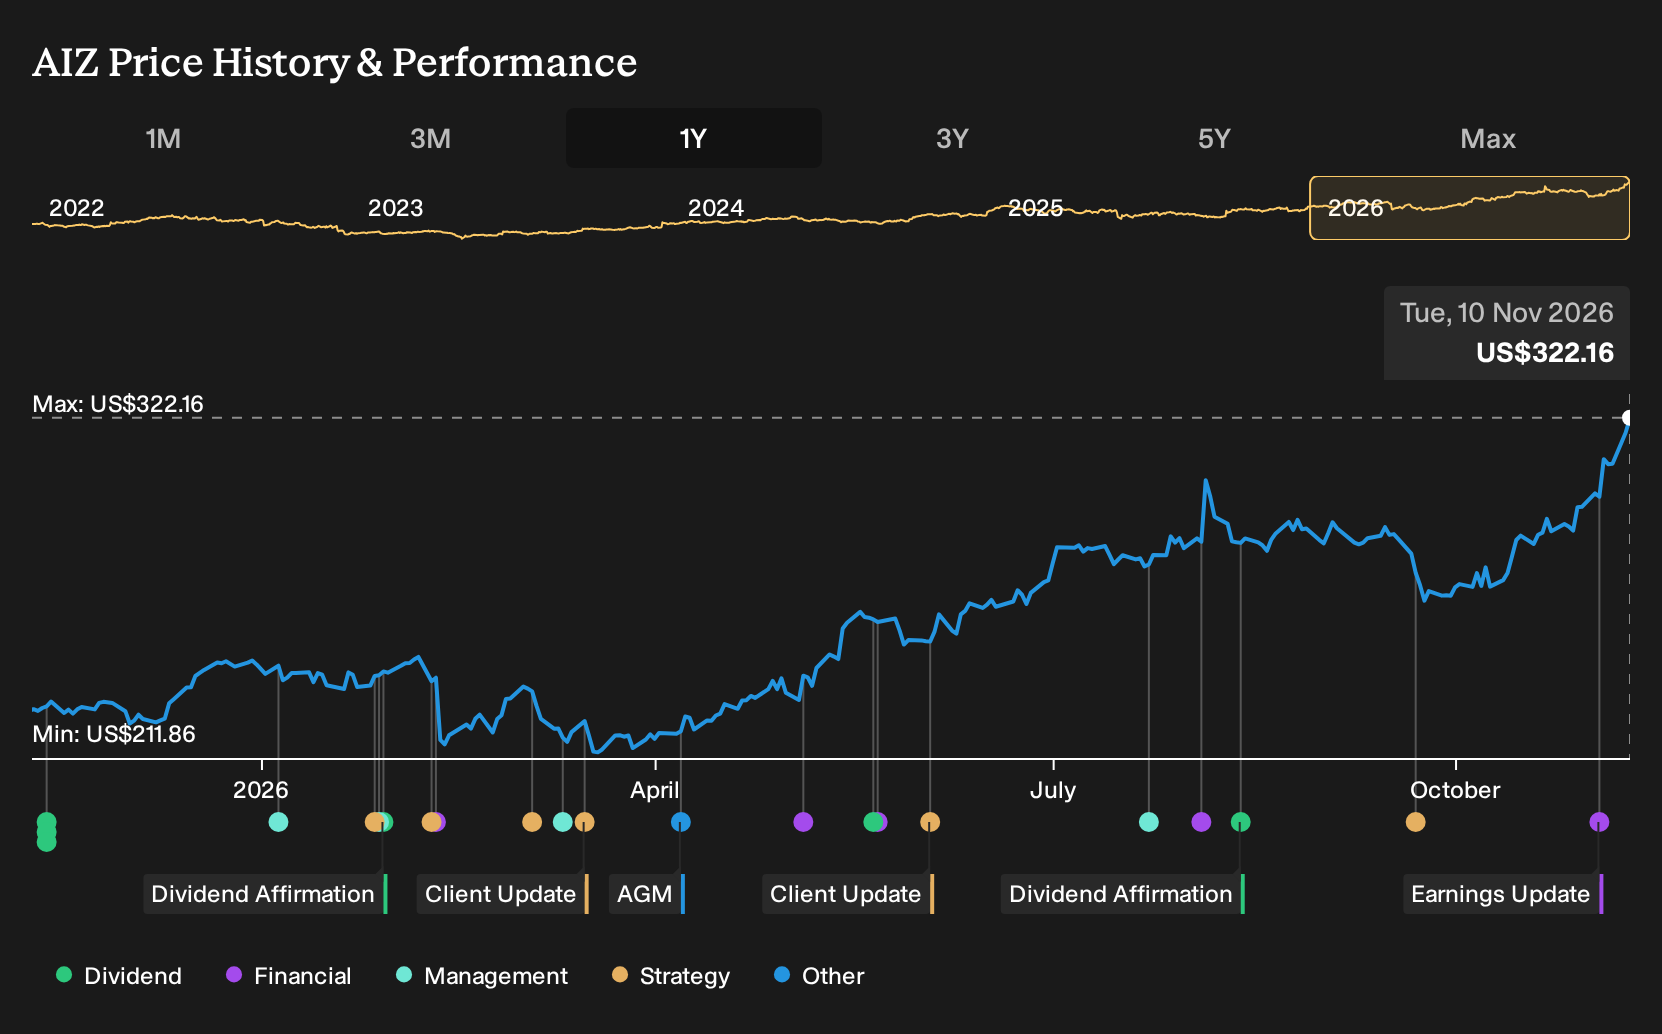
The most relevant update for this catalyst view is the completion of the buyback tranche. Assurant has repurchased 1,242,226 shares since November 2025, or 2.5% of the register, for US$305.11 million, including 376,000 shares between July and October 2026. Those figures help explain why diluted EPS from continuing operations reached US$5.49 in the third quarter.
For you as a shareholder, that combination of earnings and a lower share count ties directly into the EPS path that the analyst consensus Narrative on Simply Wall St describes. The repurchases also interact with valuation risk. If investors become more cautious about lender placed exposure or relative growth versus peers, a higher P/E multiple may be harder to sustain even with ongoing capital returns.
Assurant's current earnings are assessed at US$1.1b, and analysts collectively project earnings of US$1.3b on revenue of US$16.7b by 2029. This implies forecast revenue growth of 6.6% a year and an earnings increase of about US$0.2b from today.
Uncover why Assurant's fair value indicates a 5% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community for Assurant span roughly US$338 to about US$559, which already shows how far apart private investors can be before the latest earnings and buyback tranche. Use that spread, along with lender placed regulation risk and AI driven efficiency efforts, to test several sharply different viewpoints for yourself.
Explore another Assurant fair value estimate, including one that suggests up to 74% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Assurant research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Assurant. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Assurant's overall financial health at a glance.
Looking for more investment ideas beyond Assurant?
Once you have formed a view on Assurant, it can help to cross check that thesis against other opportunities with different risk and income profiles. The Simply Wall St Screener lets you do that quickly by narrowing the universe down to stocks that match what you care about most.
- If capital preservation is top of mind, start by scanning a curated set of companies with steadier risk profiles using the 30 resilient stocks with low risk scores.
- If you prefer dependable income, review a focused group of higher yielding payers through the 5 dividend fortresses.
- If you are hunting for less crowded ideas with strong fundamentals, broaden your watchlist with the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com