


Unicaja Banco (BME:UNI) is back in focus after reporting third quarter 2026 results, with net interest income of €399 million and net income of €182 million, both higher than the prior year.
That earnings beat comes on top of a strong run for Unicaja Banco, with a year-to-date share price return of 22.46% and a 1-year total shareholder return of 45.65%, even though the 90-day share price return has slipped 2.47%. This suggests that momentum has cooled recently after a multiyear total shareholder return that is more than 3x over 3 years and more than 4x over 5 years.
Compare Unicaja Banco's momentum and earnings story with other hand picked European banks posting solid fundamentals through our list of solid balance sheet and fundamentals (194 results)
Unicaja Banco now combines improving earnings with a powerful multi year share price run, yet a softer 90 day stretch raises a simple question. Are you looking at a quality franchise that is still reasonably priced, or one where expectations already do the heavy lifting?
Most Popular Narrative: 11% Overvalued
On the analyst consensus Narrative on Simply Wall St, Unicaja Banco’s fair value sits at €3.14 per share, below the latest €3.47 close. This frames the recent rally against a model that already incorporates strong profitability and fee income.
Growth in fee based income from mutual funds and off balance sheet products is now supported by mutual fund balances of more than €18b, double digit growth in non banking fees and a majority contribution of these activities to fee income. Together, these factors support a view that investors are paying for a business mix that could increasingly rely on fee revenues rather than spread income.
See why 3 investors see Unicaja Banco as 11% overvalued.
Result: Fair Value of €3.14 (OVERVALUED)
Still, if revenue growth undershoots the 6.1% annual assumption or the market applies a P/E lower than 13.4x, the Unicaja Banco premium case weakens quickly.
Find out about the key risks to this Unicaja Banco narrative.
Another View: Unicaja Banco Through The Cash Flow Lens
The first narrative frames Unicaja Banco as 11% overvalued at €3.14 based on earnings forecasts and a 13.4x P/E in 2029. A different lens tells a different story. The SWS DCF model values the shares at €3.73, with the current €3.47 price sitting about 7% below that estimate. Which signal should be given more weight: earnings multiples or long run cash flows?
For a closer look at how those long term cash assumptions are built and stressed, Look into how the SWS DCF model arrives at its fair value.
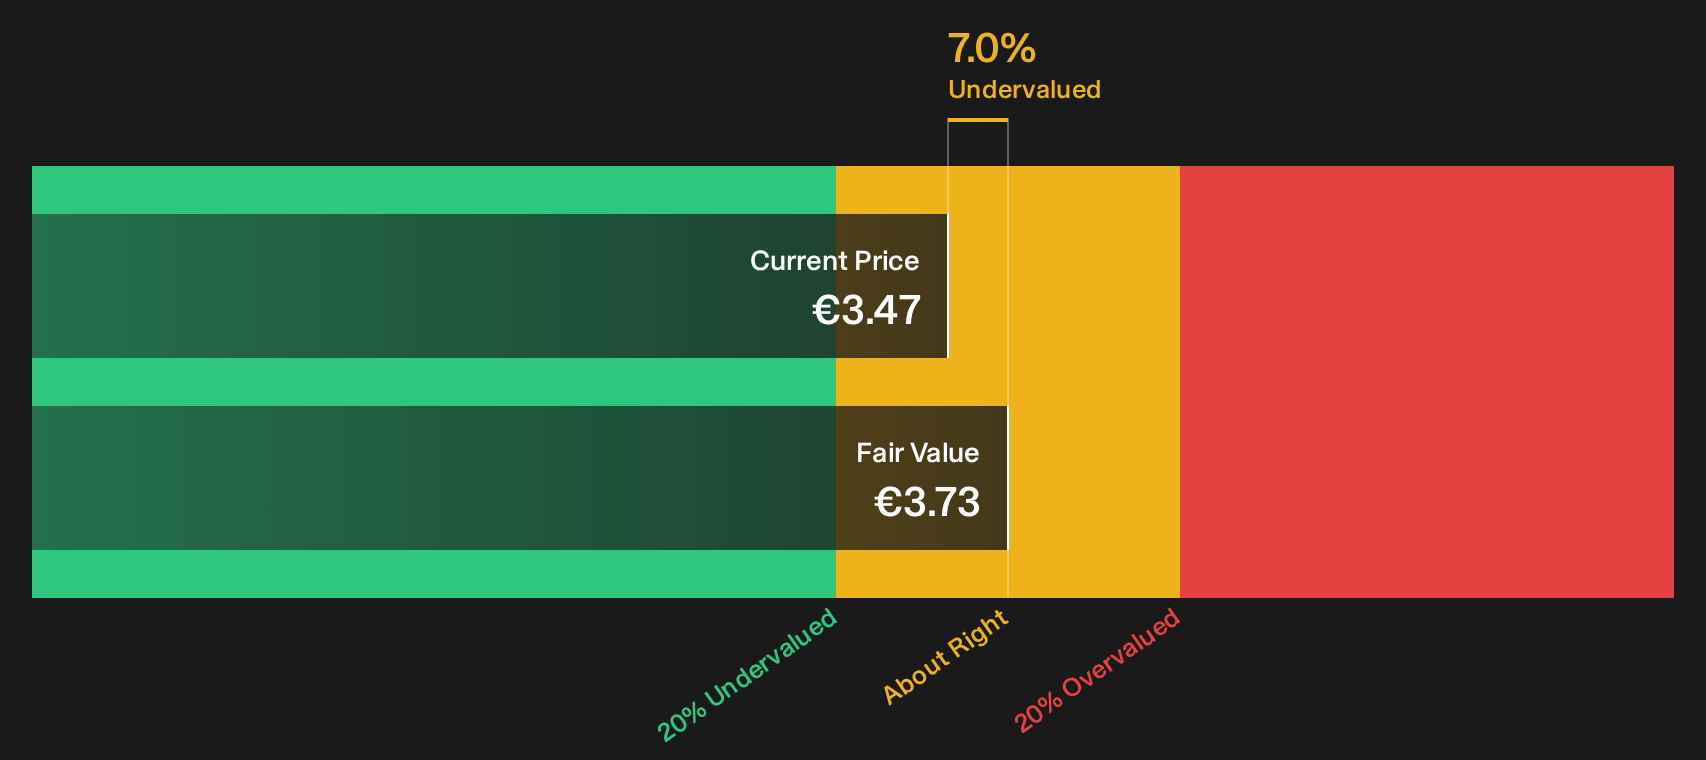
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Unicaja Banco for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 202 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Unicaja Banco so far, or a clear setup hiding in plain sight. Move quickly, review the full picture, then weigh the 2 key rewards and 2 important warning signs.
Looking for more Unicaja Banco style investment ideas?
Do not stop with one opportunity. Use the Simply Wall Street Screener to line up a few more ideas that match your style and risk tolerance.
- Target dependable compounders by scanning a curated 202 high quality undervalued stocks that combine quality fundamentals with pricing that still leaves room for upside.
- Build a steadier income stream by reviewing our 217 dividend fortresses that focus on higher yields backed by robust financial profiles.
- Protect your downside first and let upside take care of itself by zeroing in on 203 resilient stocks with low risk scores designed around lower risk scores and resilient business models.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com