


Diebold Nixdorf (DBD) just paired its latest quarterly report with a fresh US$250 million share repurchase plan, giving investors new numbers to parse and a capital return decision to interpret together.
At a share price of US$57.34, Diebold Nixdorf has seen short term pressure, with the 1 day share price return falling 4.6% and the 30 day share price return down 9.9%, yet the 3 year total shareholder return is still very large at about 2.5x. The mixed third quarter earnings numbers and the new US$250 million buyback are now being weighed together, and this can shift how investors think about both the company’s growth potential and its risk profile.
Contrast Diebold Nixdorf's mix of buybacks, earnings volatility, and turnaround potential with a hand picked group of companies in the 35 high quality undervalued stocks.
After a rapid three year rebound and a fresh US$250 million buyback on the table, the real puzzle now is whether the bigger upside for Diebold Nixdorf still lies ahead or is already in the rear view mirror.
Most Popular Narrative: 33% Undervalued
On the analyst consensus Narrative on Simply Wall St, Diebold Nixdorf screens as undervalued, with a fair value of $85 against a last close of $57.34. That framework ties the current price to explicit revenue, earnings and margin forecasts rather than a loose story.
Company-wide lean programs and operating expense reduction efforts, including over 200 identified cost actions, field technician software that cuts dispatch times and labor, consolidation of repair and service centers and an expected 1% to 2% OpEx decline in 2026, are designed to keep EBITDA, operating margin and free cash flow growth aligned with targets such as US$510 million to US$535 million adjusted EBITDA and US$255 million to US$270 million free cash flow guidance.
See why 3 investors see Diebold Nixdorf as 33% undervalued.
Result: Fair Value of $85 (UNDERVALUED)
Still, the story can break if service productivity improvements do not materialize, or if component and tax costs squeeze Diebold Nixdorf margins harder than analysts model.
Find out about the key risks to this Diebold Nixdorf narrative.
Another Take On Diebold Nixdorf’s Valuation
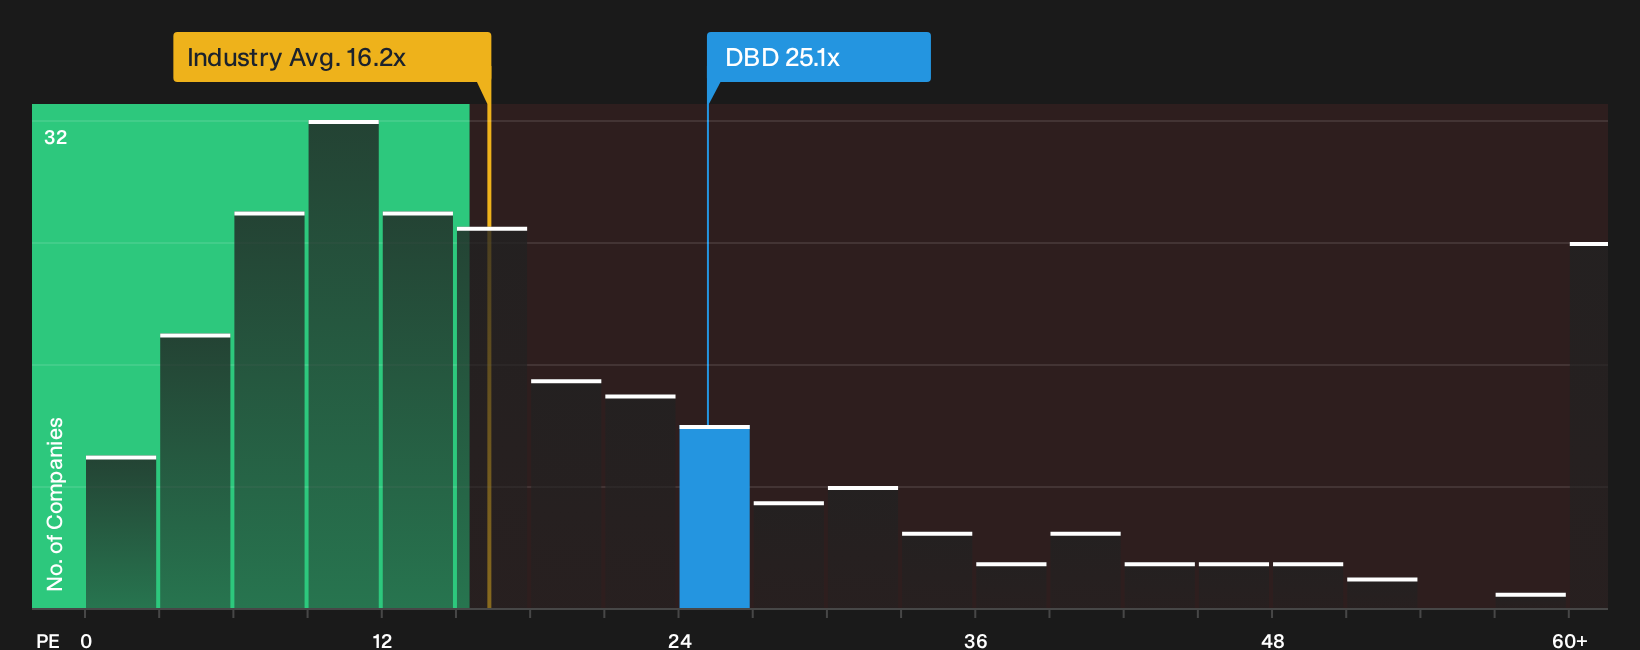
DCF work and analyst targets lean toward Diebold Nixdorf looking undervalued around US$57.34. The market’s simple P/E check tells a different story. DBD trades on roughly 25.1x earnings, which is richer than both the global tech group at 16.4x and its peer set at 21.3x.
The fair ratio sits much higher at 55.1x though, which implies the current multiple could move either closer to peers or drift toward that fair ratio over time. For an investor weighing that spread, the live question is whether this gap signals excess risk or a potential opportunity.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed signals around Diebold Nixdorf leave you undecided, review the data while it is current and form your own stance using the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Diebold Nixdorf?
Do not stop at Diebold Nixdorf. Broaden your watchlist with a few focused stock ideas that match clear goals on value, resilience and income.
- Target quality at a discount by scanning for companies that pair robust fundamentals with appealing valuations through the 35 high quality undervalued stocks.
- Prioritize resilience by filtering for businesses with stronger balance sheets and healthier financial footing using the list of solid balance sheet and fundamentals (24 results).
- Put cash flow to work by reviewing stocks that currently offer higher yields in the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com