


Liquidia (LQDA) is back in focus after reporting third quarter 2026 results that combined strong YUTREPIA commercial traction, a sweeping legal settlement with United Therapeutics, and fresh regulatory momentum for its pulmonary hypertension franchise.
That mix of legal clarity, YUTREPIA momentum, and fresh Fast Track news has fed directly into the recent rally, with Liquidia’s share price climbing 87.73% over the past 30 days and its 1-year total shareholder return at 85.03%, while the 3-year total shareholder return is roughly 7x and the 5-year figure is even higher. Short term momentum is clearly building on top of already very strong long term gains.
Scan how traders are pricing similar rare disease momentum stories by comparing Liquidia with a hand picked group of 36 healthcare AI stocks that are also tying technology to complex care.
Liquidia now appears to be a far stronger business than it was a year ago, yet the stock has already risen significantly. Are investors paying a premium, or still pricing in some skepticism?
Most Popular Narrative: 56% Overvalued
Liquidia last closed at $51.40 while the most popular bearish analyst Narrative on Simply Wall St anchors fair value at $33.00 using a 7.24% discount rate. This frames the recent rally as pricing in a lot of optimism already.
Although Liquidia is using YUTREPIA cash generation to support an expanded study portfolio, the plan to double R&D expense in the second half of 2026 and to increase it again in 2027 could outpace revenue growth and compress operating margins and earnings if new indications or L606 do not convert efficiently into future sales.
See why 2 investors see Liquidia as 56% overvalued.
Result: Fair Value of $33 (OVERVALUED)
Still, a few things could upset that 56% overvalued story, including sustained YUTREPIA adoption strength and Liquidia’s current cash position and EBITDA profile.
Find out about the key risks to this Liquidia narrative.
Another View: Liquidia Through The Cash Flow Lens
The bearish narrative pegs Liquidia at $33.00, yet our DCF model points in a very different direction. On that framework, LQDA at $51.40 trades about 69.3% below an estimated future cash flow value of $167.29. This frames the risk as a choice between paying up for volatility or passing on a large implied upside. Which story feels closer to how you see this business playing out?
To see how that long term cash flow view is built and where the sensitivities sit, take a moment to walk through the SWS model itself, step by step, via Look into how the SWS DCF model arrives at its fair value.
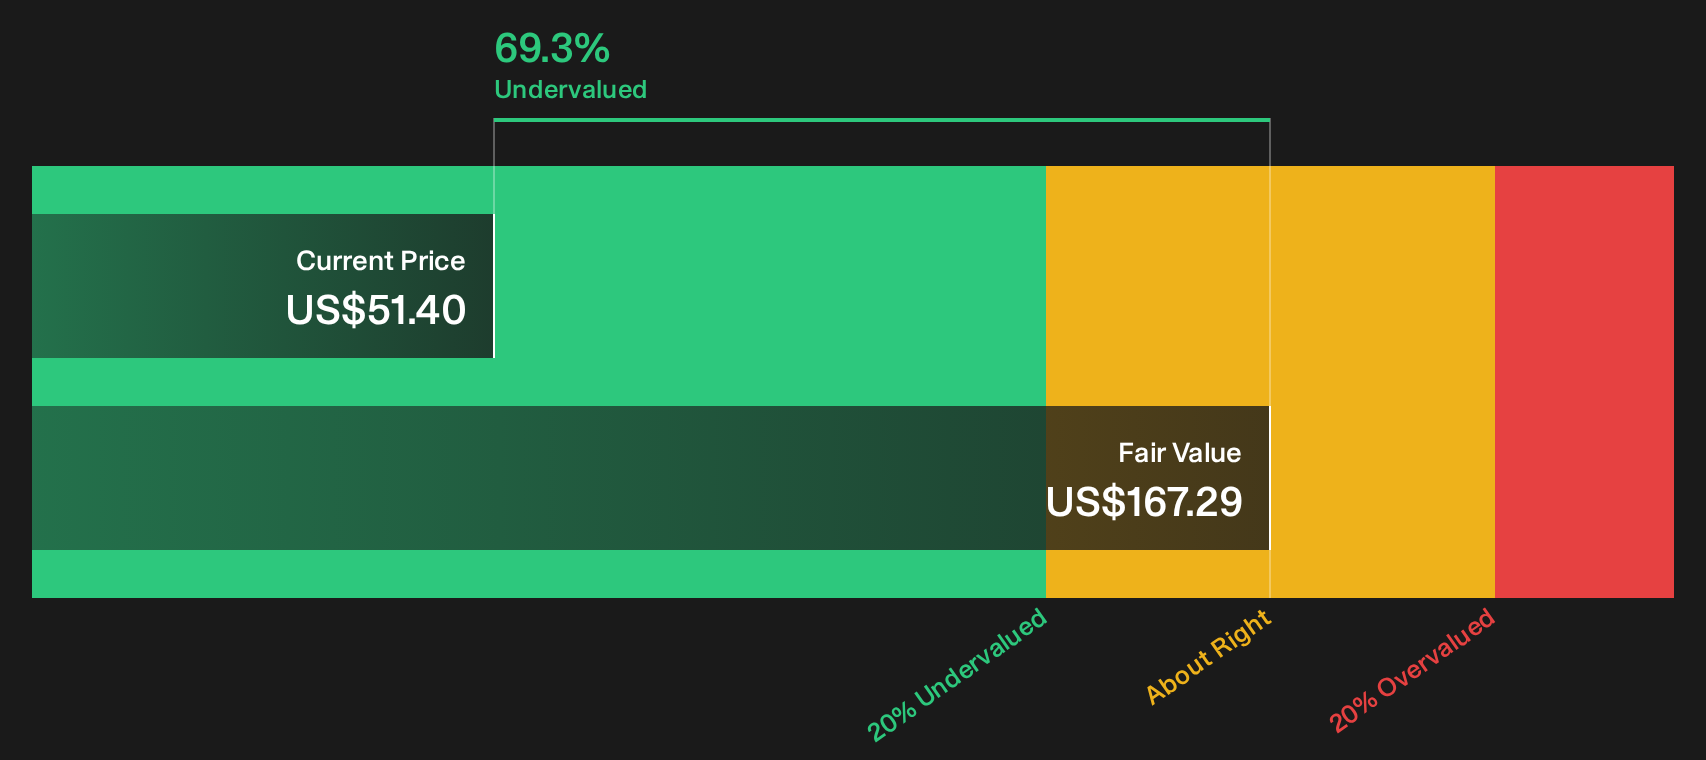
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Liquidia for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Liquidia is clearly split, so treat this as your prompt to move fast, review the evidence, and weigh up both the red flags and bright spots through the 2 key rewards and 3 important warning signs.
Looking for more Liquidia sized opportunities?
Before moving on, give yourself one more shot at fresh ideas by running a quick screen for other stocks that fit your risk level and return goals.
- Target steadier compounding potential by reviewing a curated set of 35 high quality undervalued stocks that pair quality fundamentals with attractive pricing.
- Strengthen your downside protection by scanning a list of solid balance sheet and fundamentals (24 results) that can better handle stress without constant refinancing risk.
- Stay ahead of the crowd by filtering for 20 high quality undiscovered gems before they sit on every analyst’s radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com