


- CorVel reported past second quarter results for the period ended September 30, 2026, with sales of US$267.13 million and net income of US$34.09 million, alongside basic and diluted EPS of US$0.67 from continuing operations.
- For the first six months of the fiscal year, CorVel posted sales of US$527.05 million and net income of US$66.31 million, which frames EPS of US$1.31 as a key reference point for how the business is currently converting revenue into profit.
- We will examine how CorVel's investment narrative aligns with this reported increase in sales and net income.
Compare CorVel's latest earnings power with peers by scanning our hand picked 20 high quality undiscovered gems that share strong fundamentals but may still be flying under most investors' radar.
What Is CorVel's Investment Narrative?
To own CorVel, you have to buy into a pretty simple idea. This is a niche healthcare services business that lives and dies on execution, data, and discipline. The latest quarter fits that story. Sales and net income for both the second quarter and first half of the year point to a model that is currently converting workers’ compensation and claims management demand into consistent profits, with EPS of US$0.67 for Q2 and US$1.31 for the six month period.
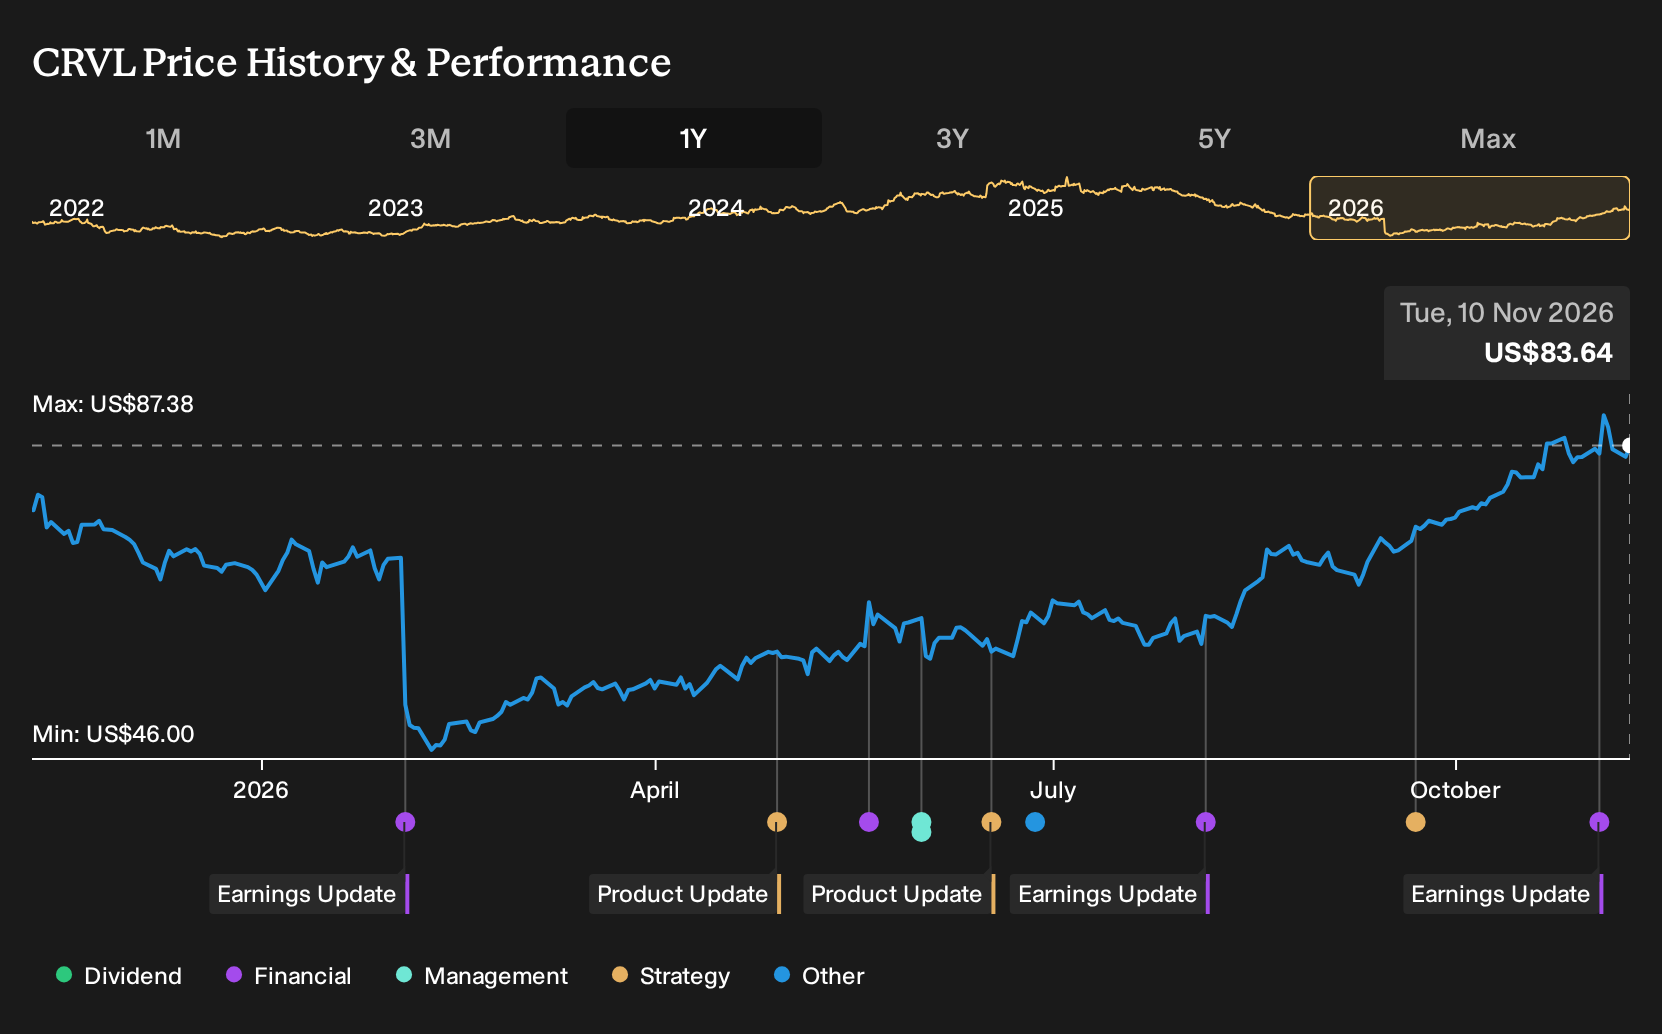
In the short term, the fresh earnings print speaks directly to the key levers that matter for shareholders. CorVel runs an asset light model, so capital intensity is not the main swing factor. The real swing factors are pricing power with insurers and employers, the stickiness of its technology driven services, and how tightly costs are held in check. The stock has moved higher over the past 90 days, and the reported growth in sales and net income supports that momentum rather than challenging it. At the same time, a P/E of 34.7x alongside recent insider selling indicates that the margin for disappointment is not wide.
Even so, there is one pressure point in the CorVel story that is easy to underestimate until you look closely at ...
There's only one way to know the right time to buy, sell or hold CorVel. Head to Simply Wall St's company report for the latest analysis of CorVel's Fair Value.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CorVel research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CorVel. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CorVel's overall financial health at a glance.
Looking For More Investment Ideas Beyond CorVel?
If CorVel has sharpened your thinking about quality and pricing power, it can be useful to line it up against a wider bench of potential opportunities using the Simply Wall St Screener.
- If you want income to play a bigger role in your portfolio, check out companies that feature in our 5 dividend fortresses and see which ones pair yield with staying power.
- For investors who care most about balance sheet strength, filter for stocks in the list of solid balance sheet and fundamentals (24 results) to focus on businesses that keep financial risk in check.
- When you prefer a smoother ride and lower volatility, narrow your watchlist using the 30 resilient stocks with low risk scores and concentrate on stocks with more resilient profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com