


Ionis Pharmaceuticals (IONS) reset expectations around its triglyceride drug TRYNGOLZA after a slower than hoped commercial ramp, trimming 2026 sales guidance while keeping broader revenue targets and cash flow timing in focus for investors.
The TRYNGOLZA reset landed on a stock that was already under pressure, with Ionis Pharmaceuticals’ share price down 49.5% over 90 days and 64.6% year to date. The latest 1-day drop of 9.1% signals momentum that is still fading despite recent earnings beats and reaffirmed 2026 revenue guidance.
Spot fresh setups by comparing Ionis Pharmaceuticals with a curated 35 high quality undervalued stocks that pairs strong balance sheets with cash generation potential.After Ionis Pharmaceuticals’ sharp reset and a share price near $28 against analyst targets in the high $70s and a deep intrinsic value gap, the real question is where fair value actually anchors this stock.
Most Popular Narrative: 66.5% Undervalued
On the analyst consensus Narrative on Simply Wall St, Ionis Pharmaceuticals screens as deeply undervalued, with a fair value of $84.13 against a last close of $28.19, which places the TRYNGOLZA reset inside a much bigger story about RNA medicines and royalties.
Partnered programs such as bepirovirsen approval in chronic hepatitis B and positive Phase 3 data for sefaxersen in IgA nephropathy point to growing royalty and milestone income that can supplement product sales and support net margin improvement without equivalent increases in operating expense. The decision by Biogen to advance diranersen into Phase 3 for early Alzheimer’s disease following Phase 2 data with around 26% slower cognitive decline and strong tau biomarker effects extends Ionis exposure to a large neurology opportunity that could materially influence long term royalty revenue and earnings power.
See why 20 investors see Ionis Pharmaceuticals as 66% undervalued.
Result: Fair Value of $84.13 (UNDERVALUED)
Still, the story around Ionis Pharmaceuticals can unravel quickly if further partnered trials disappoint or if legal actions tied to eplontersen escalate and distract leadership.
Find out about the key risks to this Ionis Pharmaceuticals narrative.
Another View: Multiples Paint A Tougher Picture For Ionis Pharmaceuticals
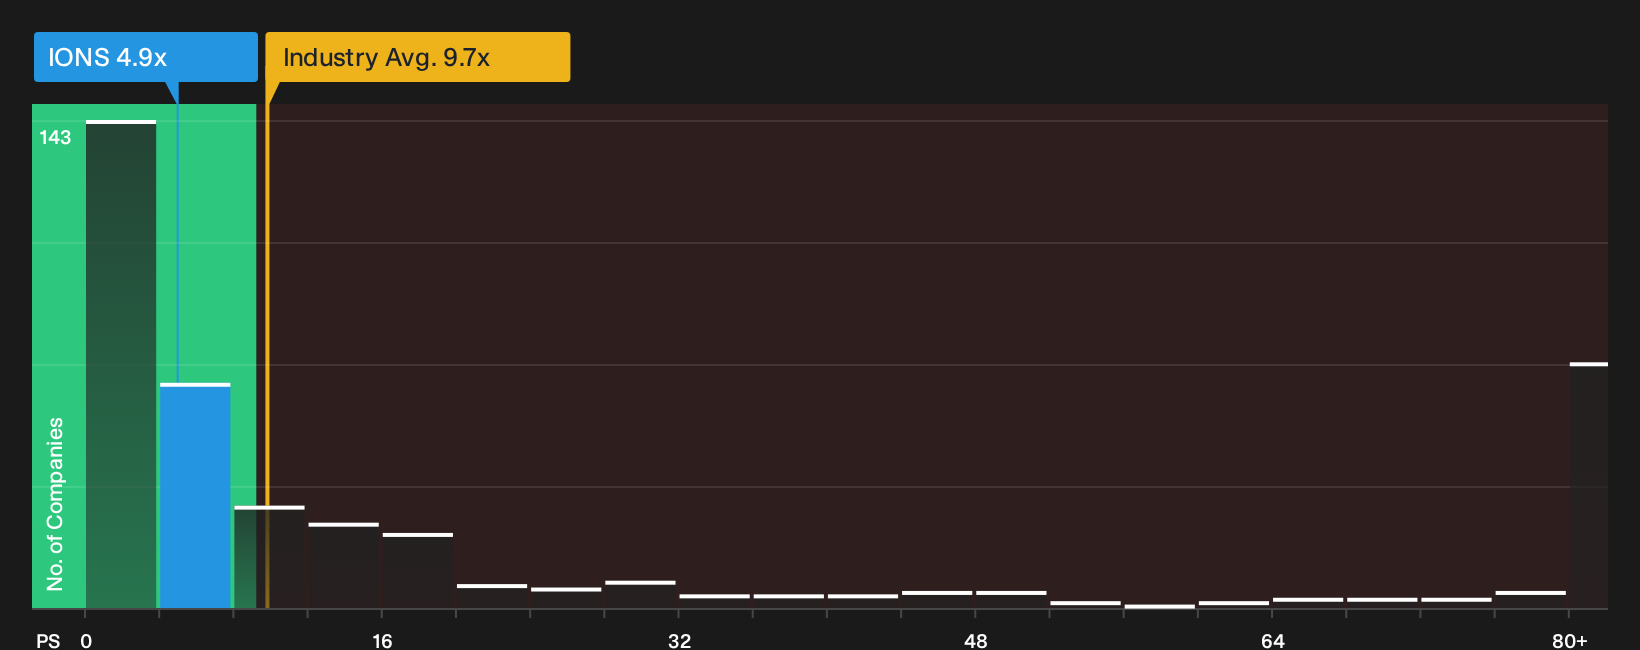
There is a sharp contrast once the fair value argument built on future cash flows is swapped for a simple sales multiple. Ionis Pharmaceuticals trades on a P/S of 4.9x, richer than its own fair ratio of 4.3x, yet below both the US Biotechs average of 9.7x and peer levels of 18.4x. That mix of slight overvaluation versus the fair ratio and a large discount to peers leaves a basic question. Is the market rightly cautious about execution risk or overlooking RNA assets that others prize more highly?
To pressure test that question against hard numbers, it helps to walk through a clean breakdown of what this pricing gap could mean for downside or upside risk in practice, then compare it with the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment may feel skewed after the TRYNGOLZA reset and sharp share price slide, so review the data yourself and thoroughly stress test the upside case with the 2 key rewards
Looking for more investment ideas beyond Ionis Pharmaceuticals?
If Ionis Pharmaceuticals has sharpened your focus on pricing, risk and balance sheet strength, use that momentum to widen your opportunity set with targeted screeners.
- Target resilient cash generators by scanning a list of solid balance sheet and fundamentals (24 results) that filters for strong finances and fundamentals before stories catch wider attention.
- Hunt for mispriced opportunities with a curated 20 high quality undiscovered gems that highlights quality businesses the broader market might still be overlooking.
- Lock in income ideas by reviewing a 5 dividend fortresses built around higher yield opportunities that still aim to keep resilience front and center.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com