


- ICL Group reported third quarter 2026 sales of US$1,910 million and net income of US$120 million, with earnings per share from continuing operations of US$0.09. The company also reported nine month sales of US$6,068 million and net income of US$383 million.
- The nine month figures show higher sales and net income than the same period a year earlier. This indicates that ICL Group’s operating performance and earnings power over the year to date attracted fresh attention from investors reviewing the business.
- Now the focus turns to how ICL Group’s higher year to date sales and net income might reshape the investment narrative for the stock.
What Is ICL Group's Investment Narrative?
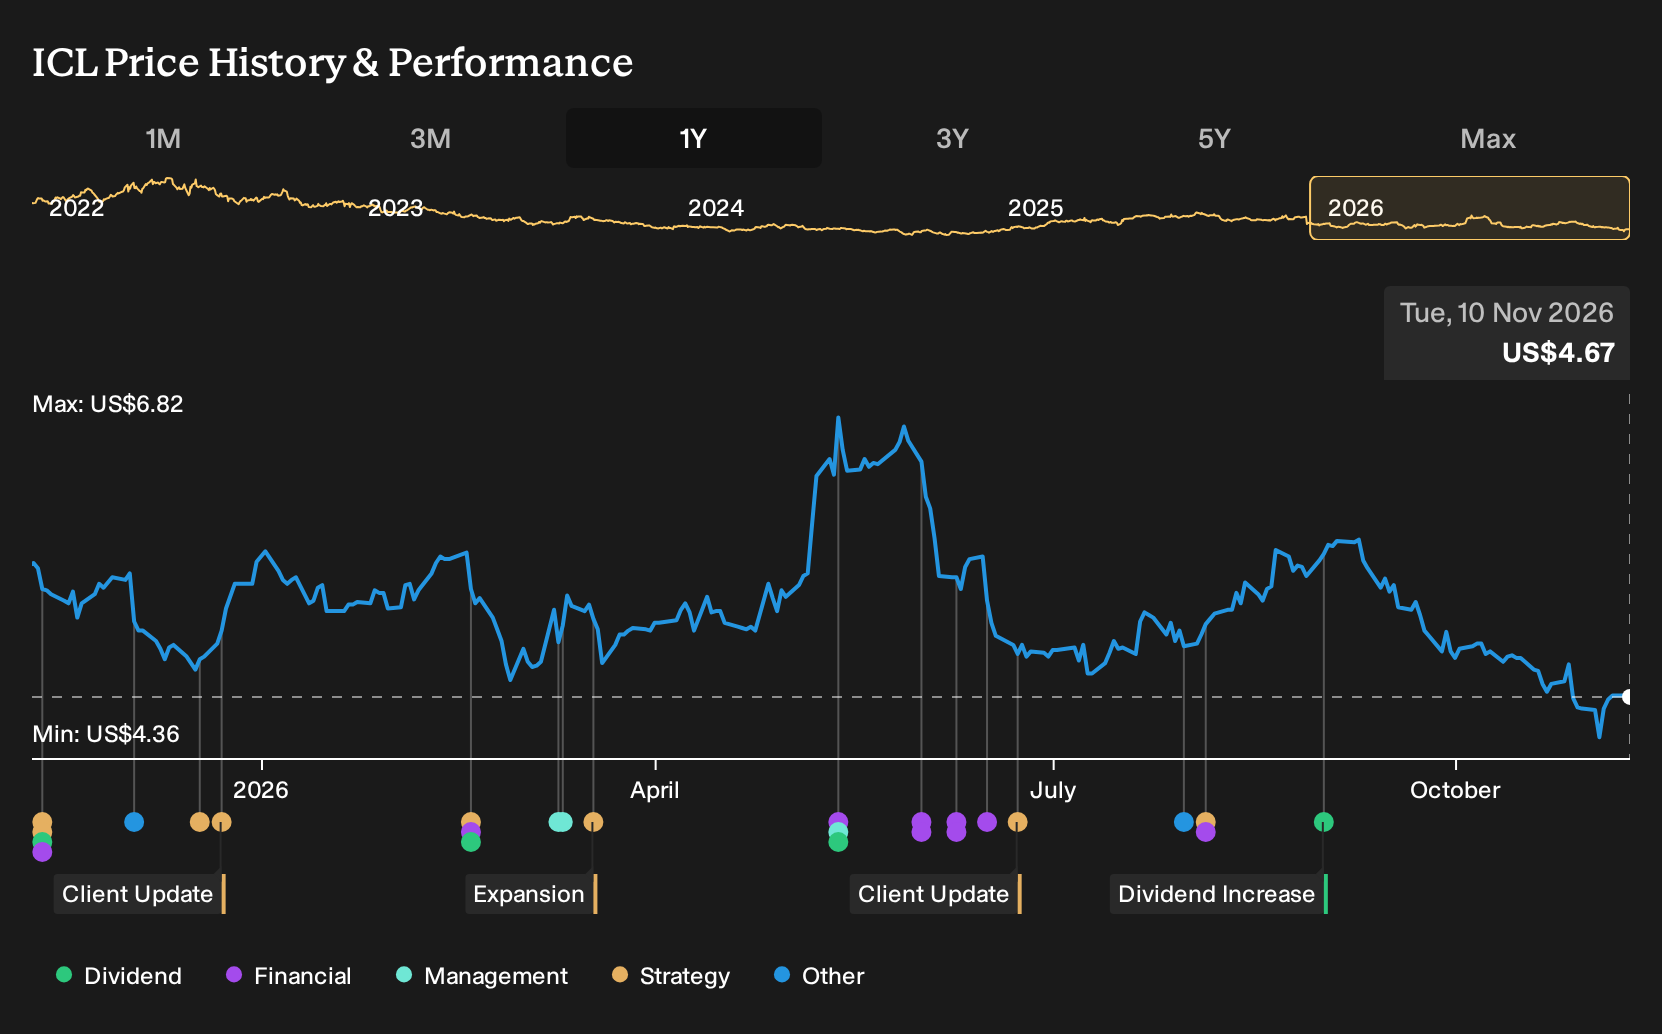
To own ICL Group, you need to be comfortable with a minerals and chemicals business where pricing, volumes and capital spending do a lot of the talking. The latest quarter slots into that picture as a steady print rather than a reset. Sales and net income for Q3 and the nine month period are modestly higher than a year earlier, but earnings per share for the quarter is flat at US$0.09. For a stock that has declined roughly 19% year to date, this kind of result tends to keep attention on execution rather than story telling.
The shorter term swing factors still look operational. Demand and pricing in potash, phosphate solutions and Growing Solutions matter most, along with how ICL Group manages a high debt load and an unstable dividend record. One off items and a history of earnings decline complicate the signal, even as the share price trades below some value estimates and analyst targets. This latest earnings update slightly improves the year to date picture but does not remove the need to watch how cash generation, capex and leverage interact over the next few quarters.
That said, the picture becomes less straightforward once you weigh one specific pressure point that still hangs over the equity story...
There's only one way to know the right time to buy, sell or hold ICL Group. Head to Simply Wall St's company report for the latest analysis of ICL Group's Fair Value.
Exploring Other Perspectives
ICL Group now sits under the microscope of two fair value estimates from the Simply Wall St Community, with views spanning roughly US$5.74 to US$8.51 per share. That spread reflects private investors using their own cash flow and earnings forecasts. Treat it as a prompt to compare several viewpoints, especially as these figures pre date the latest earnings release.
Explore another ICL Group fair value estimate, including one that suggests as much as 82% upside from the current price.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd. Trust your own research and judgment.
- A great starting point for your ICL Group research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for ICL Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ICL Group's overall financial health at a glance.
Looking For More ICL Group Style Investment Ideas?
If ICL Group has you thinking about balance sheets, income streams and valuation gaps, it can help to line it up against a wider field of businesses that share similar financial qualities. Use the Simply Wall St Screener to scan for stocks that match the traits you care about most, then build a watchlist that actually fits your approach.
- If resilience matters first, start with companies that combine financial strength and lower risk profiles through the 30 resilient stocks with low risk scores.
- For investors who care most about quality at a sensible entry price, focus on candidates with strong fundamentals that still look attractively valued using the 20 high quality undiscovered gems.
- If you want sturdier balance sheets alongside solid fundamentals, compare ICL Group with a broader list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com