


Corteva shares have slipped over the past month, even as attention around RNA-based crop protection technology keeps the business in industry conversations. With the stock now resetting after that short term decline, the open question is whether the current price sensibly reflects what the company is earning.
- The share price fell 8.1% over the past month, which puts fresh focus on whether Corteva's earnings profile lines up with where the stock now trades.
- Recent coverage of spray-induced gene silencing and RNA delivery in agriculture highlights Corteva's role in that niche, which can shape expectations for how quickly its earnings might grow relative to capital already invested in the business.
- The analysts covering Corteva have run their own numbers. See what analysts think Corteva's shares could be worth.
The issue now is whether Corteva's current share price is justified by the earnings investors are paying for today.
If you want to cross check Corteva against other potential ideas, a focused screen of 35 high quality undervalued stocks can be a useful next stop in your research process.
Does Corteva Look Pricey on Earnings?
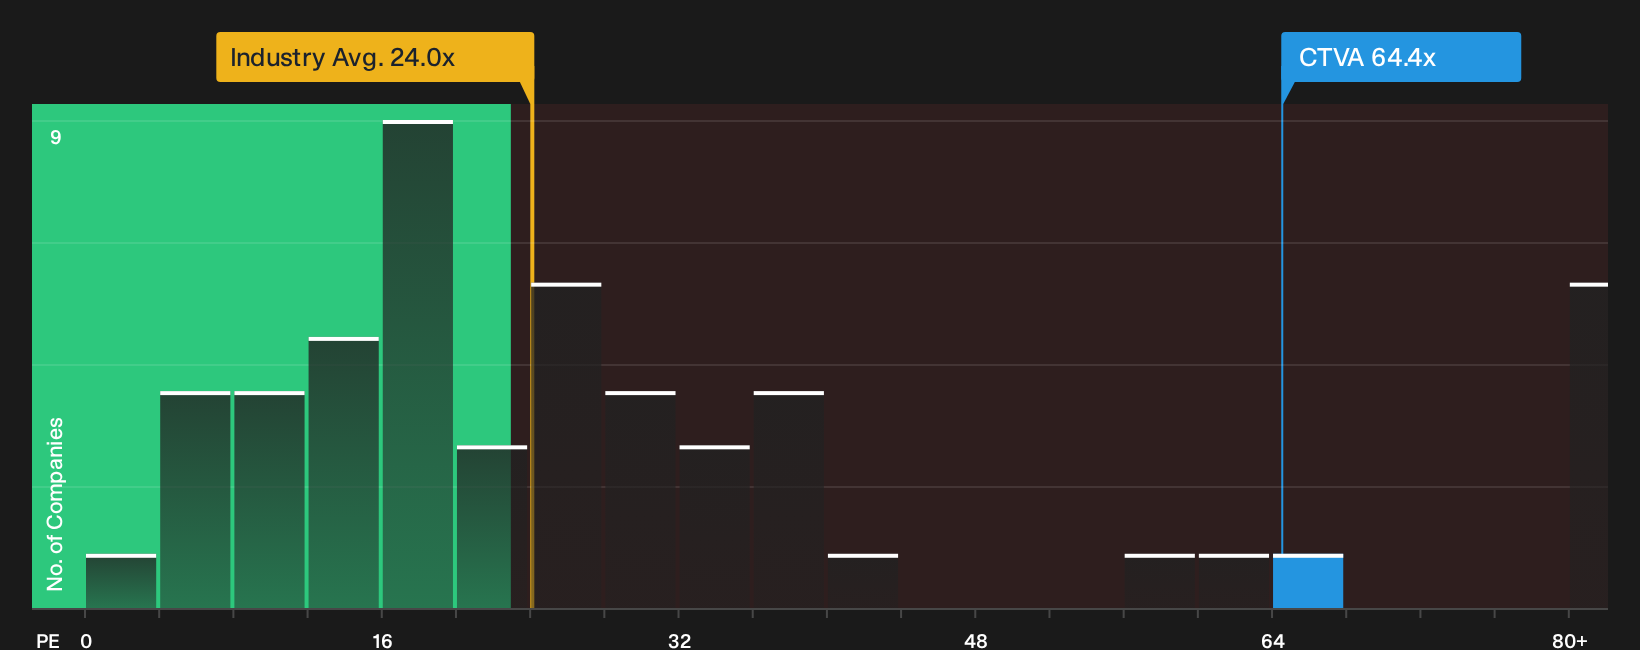
For a business like Corteva that is already profitable, the P/E ratio is a straightforward way to see how much investors are paying for each dollar of earnings. Corteva trades on a P/E of about 64.4x, compared with an average of roughly 24.0x for the wider Chemicals sector and 14.6x across direct peers. That gap signals investors are accepting a much richer sticker price than is typical for this industry.
Recent attention on RNA based crop protection and spray induced gene silencing has pushed Corteva into more specialist conversations. Yet even with that backdrop, the stock screens as overvalued relative to sector norms. The wide premium suggests the market is already incorporating strong expectations about the future of the business, so you would need to be comfortable that Corteva can justify that kind of earnings multiple over time before relying on this entry point as attractive. Explore the numbers behind Corteva's P/E valuation.
The Corteva Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle leaves off for Corteva by explaining which combinations of growth, profitability and earnings outcomes would need to hold for the stock to be worth materially more or meaningfully less than it is today. Each scenario links a fair value estimate to a clear storyline about Corteva's possible catalysts and pressure points, so you can monitor over time which version of events is actually unfolding on the Community page.
One of the top community narratives on Corteva: 64% overvalued
According to Bouden, an investor in the Simply Wall St Community, the current Corteva setup hinges on a multi year earnings recovery story.
"The case is therefore based on earnings normalisation and valuation support, with dividends providing an additional shareholder return component if payments continue…"
Discover why this Narrative puts Corteva at 64% overvalued.
One more Corteva angle worth checking before you move on
For Corteva, who sits in the driver’s seat and how that leadership is rewarded can shape every capital allocation choice you care about. See who runs Corteva and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com