


Meidensha (TSE:6508) has raised its full-year guidance and announced a sharply higher interim dividend, following stronger expectations in power infrastructure, field service engineering and EV-related operations.
Short term sentiment around Meidensha has swung around sharply, with the share price falling 38.10% over the past 30 days and declining 35.71% across 90 days. However, it still shows a 29.90% year to date share price return and a very large 3 year total shareholder return of 240.51%, which points to longer term momentum that recent volatility has not erased.
Scan for other power grid and electrification players showing similar guidance and dividend momentum by reviewing our curated 41 power grid technology and infrastructure stocks alongside Meidensha today.
For Meidensha, a 3 year return above 200% followed by a 38% slide in a month sets up a blunt question: Is the valuation still leaving meaningful upside on the table, or has most of the payoff already shown up in the share price?
Preferred P/E of 11.5x: Is it justified?
At recent prices, Meidensha trades on a P/E of 11.5x, which screens as good value against both peers and the broader JP Machinery group.
The P/E ratio compares the current share price to earnings per share and gives a quick sense of how much investors are paying for each unit of profit. For a mature industrial company like Meidensha in power infrastructure and mobility equipment, this is a straightforward way to line up expectations for future profitability across similar businesses.
Analysts indicate that earnings are forecast to grow 5.7% per year and revenue 5.8% per year, which is slower than the wider JP market on their numbers. That kind of mid single digit profile often lines up with a mid range earnings multiple, so the key question is whether the recent jump in profitability and higher net profit margins can justify something richer over time or whether the current valuation already reflects that progress.
Compared with the JP Machinery industry average P/E of 12x and a peer average of 13.2x, Meidensha is priced more cheaply on this earnings yardstick. The estimated fair P/E of 15.4x is materially higher than the current 11.5x, which indicates a level the valuation could move toward if the market eventually prices the stock in line with that implied ratio.
Explore the SWS fair ratio for Meidensha.
Result: Price-to-Earnings of 11.5x (UNDERVALUED)
Still, Meidensha faces real pressure points if project orders slow or capex budgets tighten, which could squeeze utilisation and challenge the current earnings profile.
Find out about the key risks to this Meidensha narrative.
Another View: Meidensha Through A Cash Flow Lens
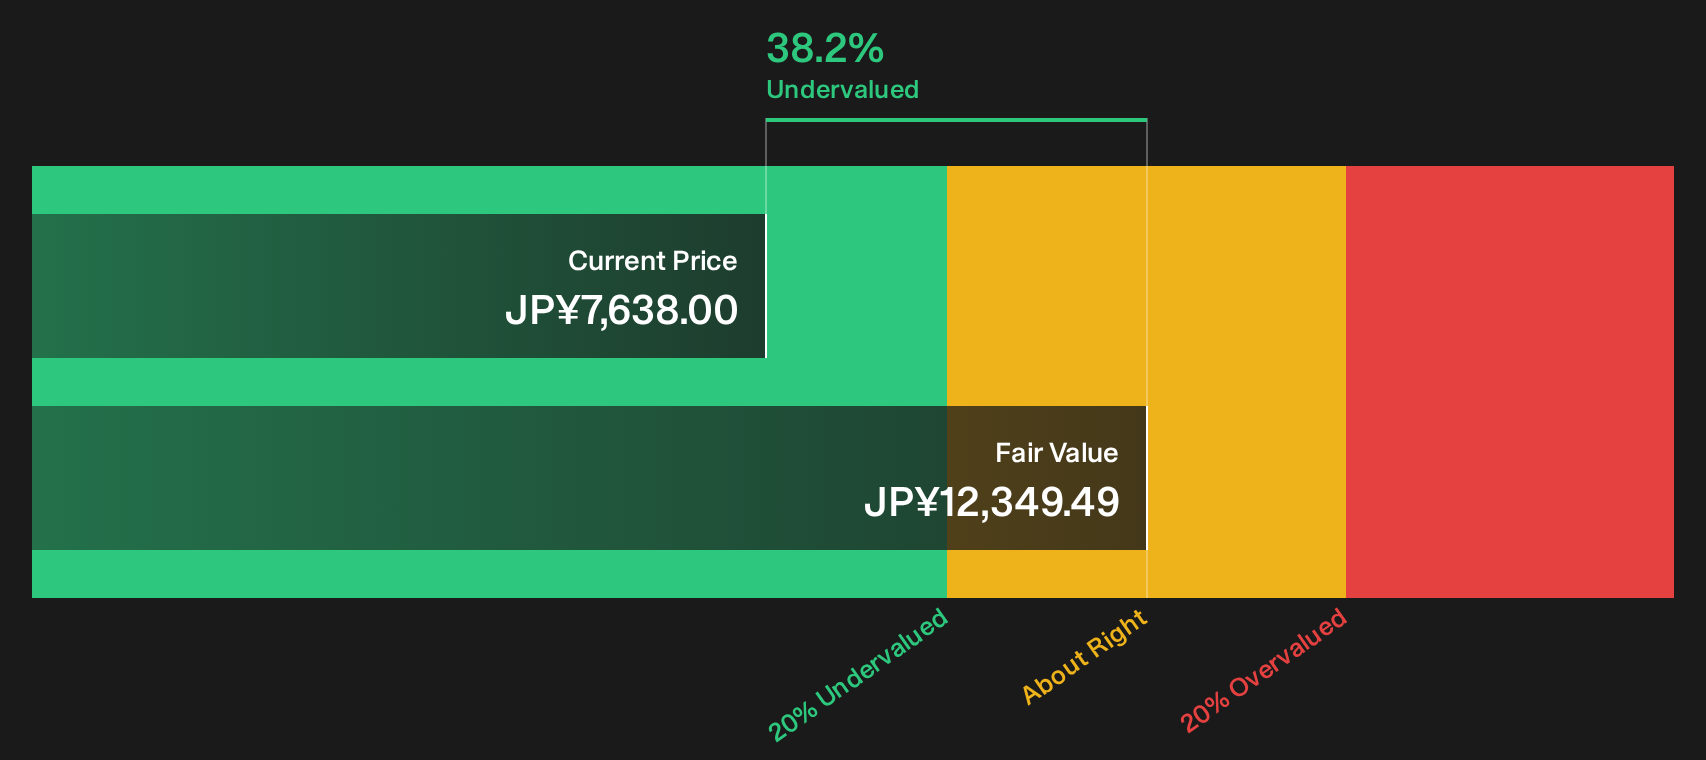
The first look at Meidensha used the 11.5x P/E to argue the shares appear inexpensive against peers. A different tool tells a similar story. Our DCF model puts future cash flow value at roughly ¥12,349 per share, compared with the current ¥7,638 price, which points to an undervalued profile.
That gap gives investors a very different yardstick than earnings multiples alone. It focuses on cash that could be generated over time rather than what was earned in the last year. The question is whether you trust the cash flow path baked into that model enough to lean on it when the share price is this volatile.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Meidensha for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 23 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals on Meidensha leave you undecided, quickly move from headline impressions to the underlying data and pressure test the thesis yourself with the full breakdown of 5 key rewards and 2 important warning signs
Looking for more ideas beyond Meidensha?
If Meidensha has sharpened your focus on pricing and quality, do not stop here. A broader watchlist can help you spot opportunities others skip.
- Target stronger balance sheets and steadier fundamentals by scanning companies in the list of solid balance sheet and fundamentals (23 results) that might complement a position like Meidensha.
- Hunt for mispriced opportunities by reviewing the 23 high quality undervalued stocks and see which businesses the market could be pricing too cautiously right now.
- Prioritise resilience and capital preservation by filtering for companies in the 19 resilient stocks with low risk scores before the next wave of investors turns their attention there.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com