


Union Pacific (UNP) is back in focus as fresh attention lands on two themes driving investor interest: new uses of artificial intelligence across rail operations and continued cash returns through dividends and buybacks.
Recent trading reflects that mood. Union Pacific’s share price is up 8.0% over the past month and has delivered a 29.6% year to date share price return. The 1 year total shareholder return of 36.6% points to momentum that has been building rather than fading.
Scan how AI themed momentum and shareholder payouts look across the rail and transport universe by comparing Union Pacific with a curated set of 30 resilient stocks with low risk scores.
Union Pacific now combines AI buzz, solid profitability and generous cash returns, all wrapped into a market value of about US$176.5b. After this run, are investors paying a fair price for that package, or stretching for it?
Most Popular Narrative: 9% Undervalued
Union Pacific is trading at a last close of $300.62 against the analyst consensus Narrative fair value of $329.88, which points to a roughly 9% valuation gap. The analyst consensus Narrative on Simply Wall St ties that upside to specific volume, margin and merger assumptions rather than just recent share price strength.
The proposed merger with Norfolk Southern, including targeted annual revenue synergies of US$1.8b and cost synergies of US$1b and a plan to resume share repurchases by year 2 after closing, would materially reshape the network footprint and could lift long term earnings and cash flow if executed as outlined.
See why 97 investors see Union Pacific as 9% undervalued.
Result: Fair Value of $329.88 (UNDERVALUED)
Still, the bullish Union Pacific narrative leans heavily on the Norfolk Southern merger clearing regulators, and on fuel and wage pressures not eroding margins faster than expected.
Find out about the key risks to this Union Pacific narrative.
Another View On What Union Pacific Is Worth
The analyst Narrative leans on earnings forecasts and a fair value of $329.88, while the SWS DCF model paints a cooler picture. On that cash flow view, Union Pacific at $300.62 screens as overvalued relative to an estimated future cash flow value of $265.65. Which lens do you trust more when real money is on the line?
Look into how the SWS DCF model arrives at its fair value.
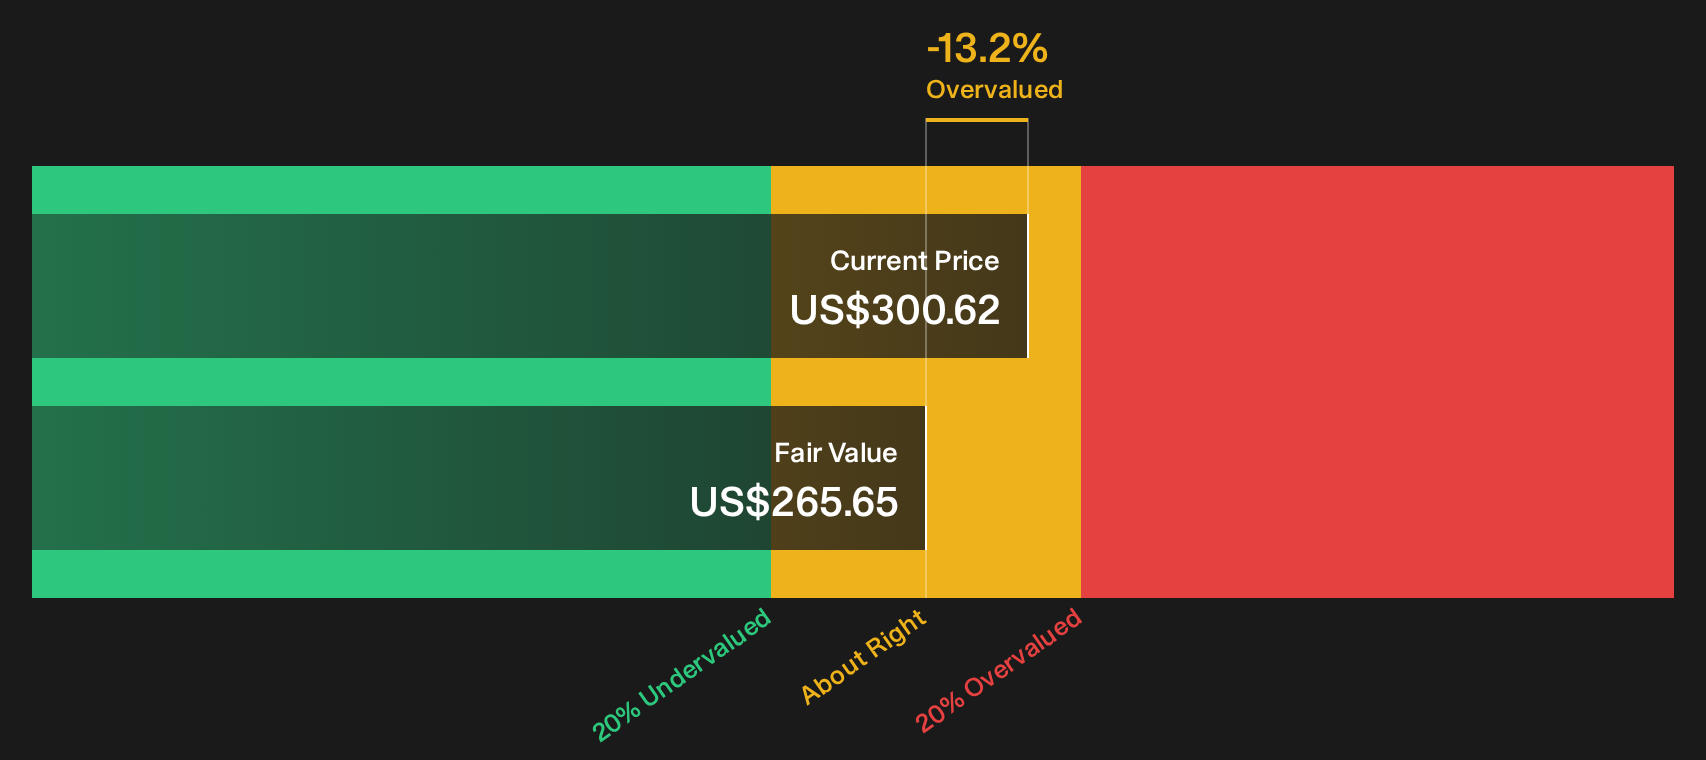
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Union Pacific for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Union Pacific currently reflects a combination of enthusiasm and uncertainty, so review the available data while sentiment is strong and form your own perspective with 5 key rewards and 1 important warning sign
Hunting For More Ideas Beyond Union Pacific?
If Union Pacific already sits on your radar, do not stop here. Broader opportunity sits in how you line up quality, value and income across the wider market.
Use these curated Simply Wall St screener ideas to pressure test your thinking, surface fresh candidates and spot gaps in your current watchlist before others move first.
- Target resilient balance sheets and steady fundamentals by reviewing a focused list of solid balance sheet and fundamentals (24 results). This can help anchor the risk side of your portfolio.
- Chase value with discipline and scan the 35 high quality undervalued stocks, which highlights companies combining robust cash flows with prices that look attractive on the numbers.
- Strengthen your income stream by assessing a hand picked set of 5 dividend fortresses. These concentrate on higher yields backed by financial staying power.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com