


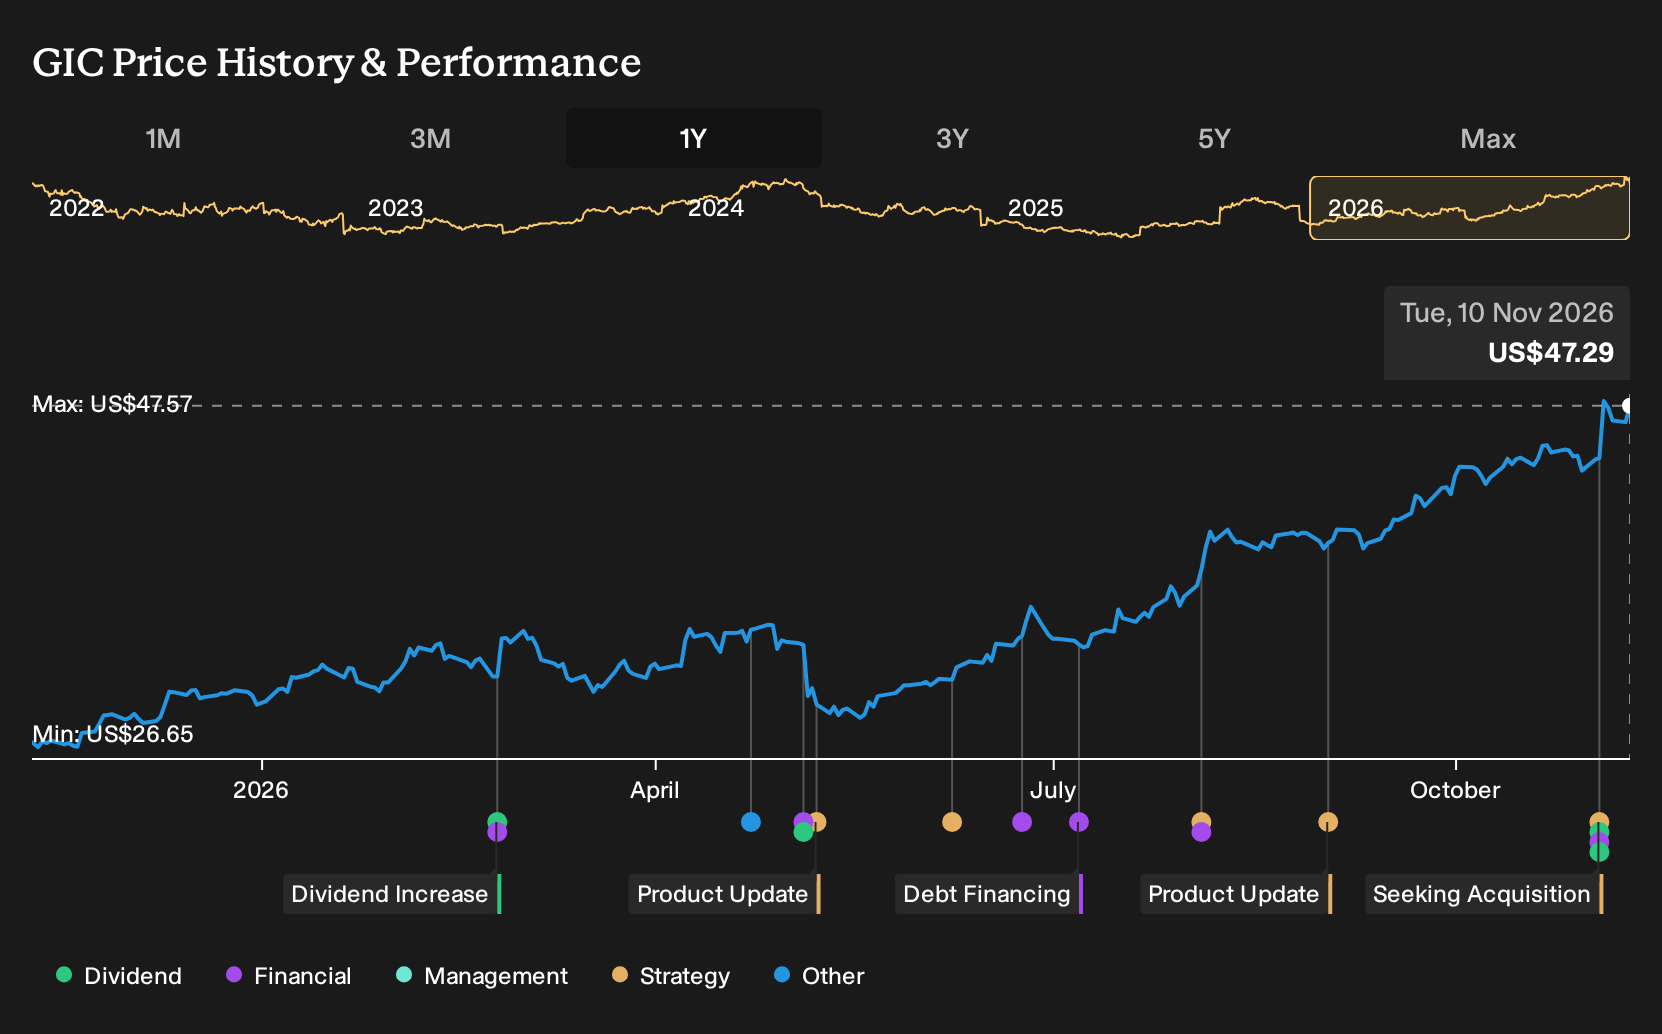
- Global Industrial reported third quarter 2026 sales of US$389.5 million and net income of US$24.6 million, alongside a regular US$0.28 dividend and a one off US$1.00 special dividend announced in early November 2026.
- The combination of higher earnings per share over both the quarter and nine month period and a special cash return to shareholders highlights management's focus on profitability, cash generation and balance sheet strength, while also discussing potential acquisitions.
- The focus now turns to how Global Industrial's latest profit performance and special dividend may reshape the existing investment narrative.
Scan the market for other companies that pair solid earnings and shareholder payouts with disciplined acquisition plans by checking our curated list of list of solid balance sheet and fundamentals (24 results)
Global Industrial Investment Narrative Recap
To own Global Industrial, an investor needs to be comfortable with a relatively steady distributor that leans on relationship led sales, digital channels and a broad MRO catalog. The analyst consensus Narrative on Simply Wall St centers on continued, but not rapid, growth and a focus on margins. The latest quarter fits that frame, with higher sales, earnings and EPS over both the quarter and nine month period.
The near term swing factor remains whether Global Industrial can keep net margins resilient while tariff pressure, freight costs and competitive pricing all stay in play. The main operational risk is that acquisition efforts or category expansion dilute returns on invested capital, especially given prior concerns that growth and ROIC have trailed industrial peers.
The clearest link to that catalyst set is the third quarter 2026 earnings update. Management reported US$389.5 million of quarterly sales, US$24.6 million of net income and US$2.04 of diluted EPS for the first nine months, along with comments about pursuing acquisitions to broaden capabilities and market reach.
For readers tracking execution, those numbers sit alongside a debt free balance sheet, previous operating cash flow of US$41.3 million in Q2 2026 and modest guided capex. That combination, together with a regular US$0.28 dividend and the one off US$1.00 per share payout, puts attention on how Global Industrial allocates excess cash between shareholder returns and any future deals.
Global Industrial's current earnings sit at US$90.8 million, with analysts forecasting earnings of US$98.7 million by 2029 and projecting revenues of US$1.7b in the same year. That view reflects 4.4% yearly revenue growth and an earnings increase of about US$7.9 million from earnings today.
Uncover how Global Industrial's fair value indicates a 4% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about US$45.5 and US$51.8 per share, which already shows how far opinions on Global Industrial can stretch. Those views were set before the earnings beat, special dividend and acquisition plans, so revisit multiple community takes if you want a fuller picture.
Explore another Global Industrial fair value estimate, including one that suggests up to a 10% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Global Industrial research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Global Industrial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Global Industrial's overall financial health at a glance.
Looking for more investment ideas beyond Global Industrial?
Once you have a view on Global Industrial, the next step is building a watchlist of other businesses that match the mix of earnings quality, balance sheet strength and shareholder returns that suits your approach. The Simply Wall St Screener can help you quickly filter the market down to a focused set of candidates.
- If you care most about quality at a reasonable price, start with companies that combine strong fundamentals and attractive valuations through our 35 high quality undervalued stocks.
- For income focused investors who want cash flows in hand rather than on paper, target steady payers and higher yields using the 5 dividend fortresses.
- Readers who put capital preservation first can zero in on financially resilient businesses with conservative profiles by working through the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com