


Scholar Rock Holding has ridden a powerful narrative this year around its muscle-targeted therapy for spinal muscular atrophy, capped by the U.S. launch of ISEMBYLD and a sharply higher share price. With the stock now near US$48, the question for investors is whether that level can be squared with the company’s book value compared with the wider pharmaceuticals and biotech industry.
- Over the past 3 years the share price has gained roughly 3.3x, which puts real pressure on the balance sheet story to explain how much of that move is supported by underlying net assets.
- The FDA approval and U.S. commercial rollout of ISEMBYLD, together with plans to expand access to around 50 countries and the US$205 million Priority Review Voucher sale, may support expectations for future funding capacity and capital intensity that feed directly into how investors view book value today.
- The analysts covering Scholar Rock Holding have run their own numbers. See what analysts think Scholar Rock Holding's shares could be worth.
The issue now is whether Scholar Rock Holding's current market price can be reconciled with its book value once set against the industry average.
Scholars looking at Scholar Rock Holding's 55.9% one year return and big book value question may also want a comparison set of 35 high quality undervalued stocks.
Is Scholar Rock Holding Getting Expensive on Book Value?
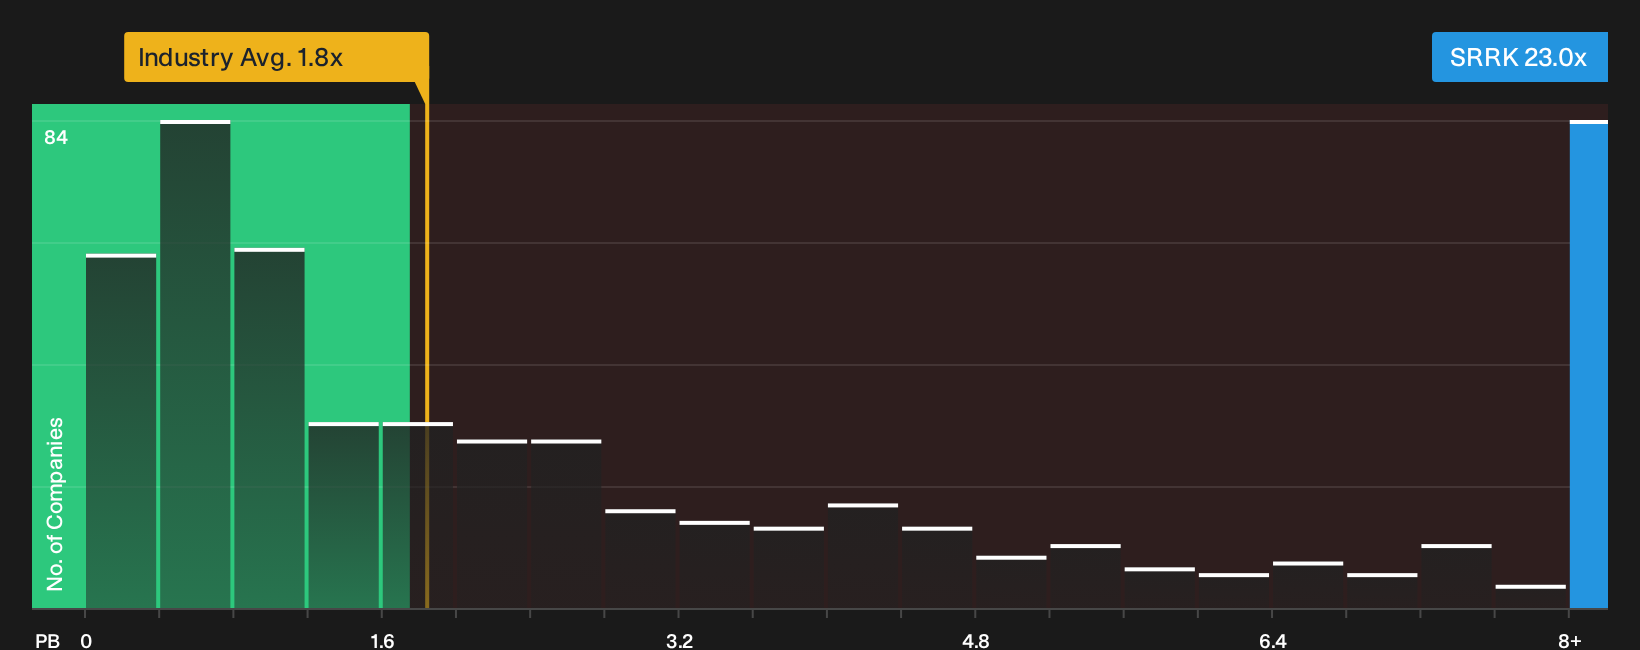
P/B fits Scholar Rock Holding because investors are weighing a research heavy pipeline against the hard equity on its balance sheet. On that score, the stock trades at about 23.0x P/B, far above the Biotechs sector average of roughly 1.8x. Even against closer peers, where the typical P/B comes in near 32.8x, the shares screen as richly priced rather than cheap on this metric.
Despite the recent FDA approval and launch of ISEMBYLD lifting interest in Scholar Rock Holding, the current P/B still embeds a hefty premium to the sector that assumes meaningful value creation relative to the existing equity base. The gap is large enough that the model is heavily penalising the company’s losses and risk profile, so the outcome reads more as a warning flag on how aggressively the equity is valued rather than as a precise estimate of what the shares should trade at. Explore the numbers behind Scholar Rock Holding's P/B valuation.
The Scholar Rock Holding Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the price to book puzzle leaves off for Scholar Rock Holding by spelling out which paths for growth, profitability and earnings would need to play out for the stock to look meaningfully higher or lower than today's market value. Rather than a single output from one model, each scenario sets out the key assumptions driving its fair value so you can compare those inputs with Scholar Rock Holding's actual results over time.
One of the top narratives on Scholar Rock Holding: 32% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Scholar Rock Holding focuses on developing muscle-targeted therapies for rare and severe neuromuscular diseases, led by its apitegromab program for spinal muscular atrophy..."
Discover why this Narrative puts Scholar Rock Holding at 32% undervalued.
One more angle on Scholar Rock Holding that could reshape the story
Before you move on from Scholar Rock Holding, it is worth asking who is steering the business and how their pay lines up with the risks and rewards you have just been weighing. See who runs Scholar Rock Holding and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com