


Third quarter earnings and guidance reset frame Flowserve’s latest move
Flowserve (FLS) just delivered third quarter results showing higher sales but lower profitability, then trimmed its 2026 sales growth outlook because of slower customer activity in the Middle East.
Flowserve’s share price has pushed higher over 2026, with a 21.07% year to date share price return and a 24.93% one year total shareholder return. The 18.51% one month share price move suggests momentum held up around the guidance cut.
Scan how Flowserve compares with other industrial players that are resetting expectations after earnings by reviewing our hand-picked list of list of solid balance sheet and fundamentals (24 results)
After a sharp move over the past month and a softer profit print, Flowserve now sits in a grey zone. Is most of the upside already captured? Or does the recent reset leave more room ahead on valuation?
Most Popular Narrative: 6% Undervalued
Flowserve closed at $85.66 against a fair value from the analyst consensus Narrative on Simply Wall St of $91.20. This points to a modest gap between price and that modelled estimate while anchoring expectations to detailed earnings and margin forecasts.
Ongoing work under the Flowserve Business System, including 80/20 portfolio actions, footprint realignment and commercial discipline, is aimed at pushing adjusted operating margin from the roughly 16% expected in 2026 toward the stated 20% target for 2030. This would directly support earnings and free cash flow.
See why 39 investors see Flowserve as 6% undervalued.
Result: Fair Value of $91.20 (UNDERVALUED)
Still, the Flowserve narrative depends heavily on Middle East activity stabilising and on successful integration of the US$490 million Trillium deal.
Find out about the key risks to this Flowserve narrative.
Another View: Flowserve’s Rich Earnings Multiple
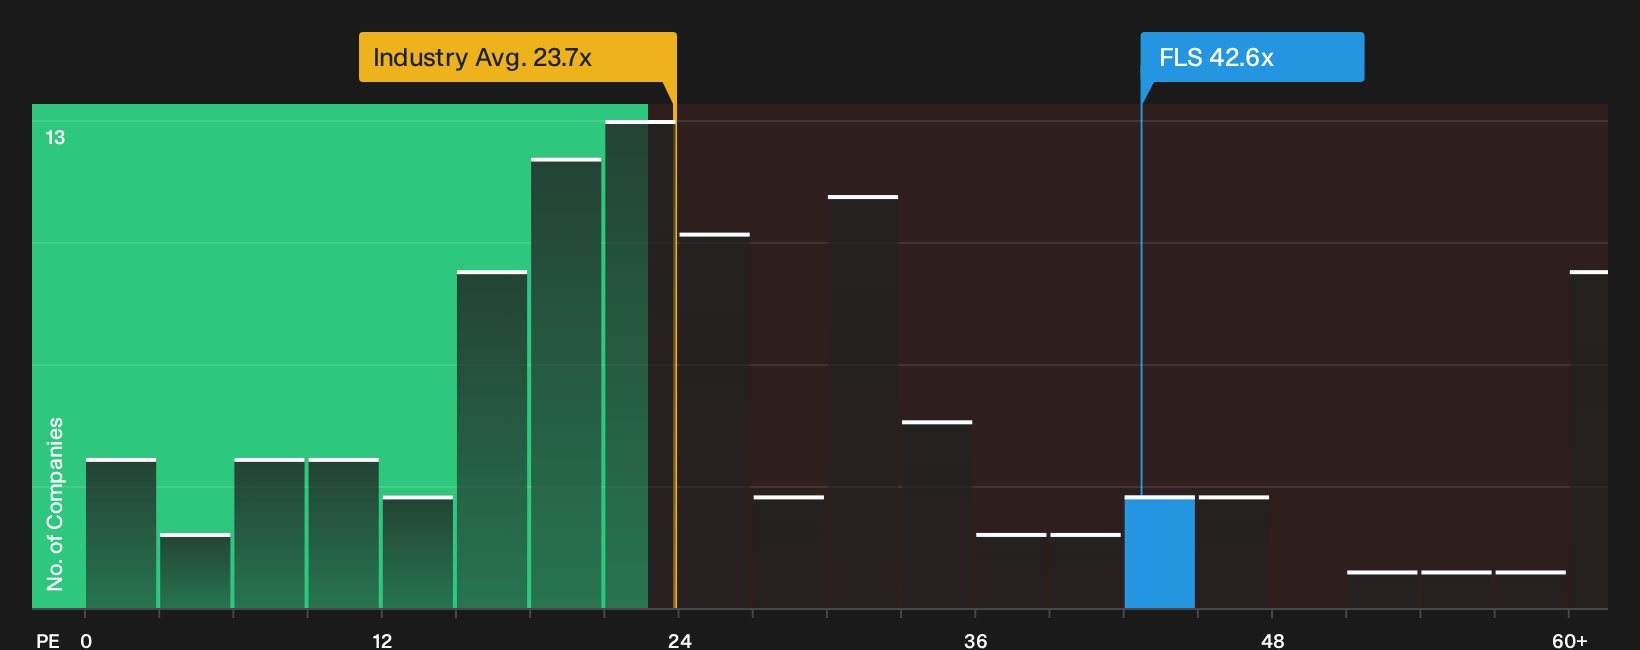
The SWS DCF model points to Flowserve trading at a discount to an estimated future cash flow value of $105.28, which supports the idea of upside from $85.66. The picture changes when you look at earnings. The current P/E of 42.6x sits above the Machinery industry on 24.1x, above peers on 22.3x, and even ahead of a fair ratio of 40.7x that the market could move toward. That kind of premium can either reflect confidence in the earnings ramp, or set a tighter margin for error if those forecasts slip.
To see how this richer earnings multiple stacks up against cash flow based fair value, and where the valuation stress points might be, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Flowserve’s valuation can be confusing at first glance. Move quickly, scrutinise the underlying data, and weigh both sides of the story with 2 key rewards and 3 important warning signs
Looking for more Flowserve style investment ideas?
You have already done the work on Flowserve. Do not stop there when a few focused screens can quickly surface fresh opportunities that fit your style.
- Target potential mispricings by scanning a curated 35 high quality undervalued stocks that filters for quality fundamentals as well as appealing entry points.
- Prioritise resilience by reviewing a 30 resilient stocks with low risk scores that concentrates on businesses with sturdier balance sheets and calmer risk profiles.
- Get ahead of the crowd by combing through a 20 high quality undiscovered gems that highlights underfollowed companies with strong underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com