


- Crown Holdings recently reported quarterly revenue of $3.71b, up 15.9% year on year, with earnings per share also above analyst forecasts.
- The stronger than expected revenue and earnings suggest that recent operational execution and demand for packaging supported Crown Holdings' latest results.
- We will now look at how Crown Holdings' stronger than expected revenue growth shapes the broader investment narrative for the business.
Scan how Crown Holdings' strong quarter compares with peers by lining up its packaging rebound against our curated list of 35 high quality undervalued stocks.
Crown Holdings Investment Narrative Recap
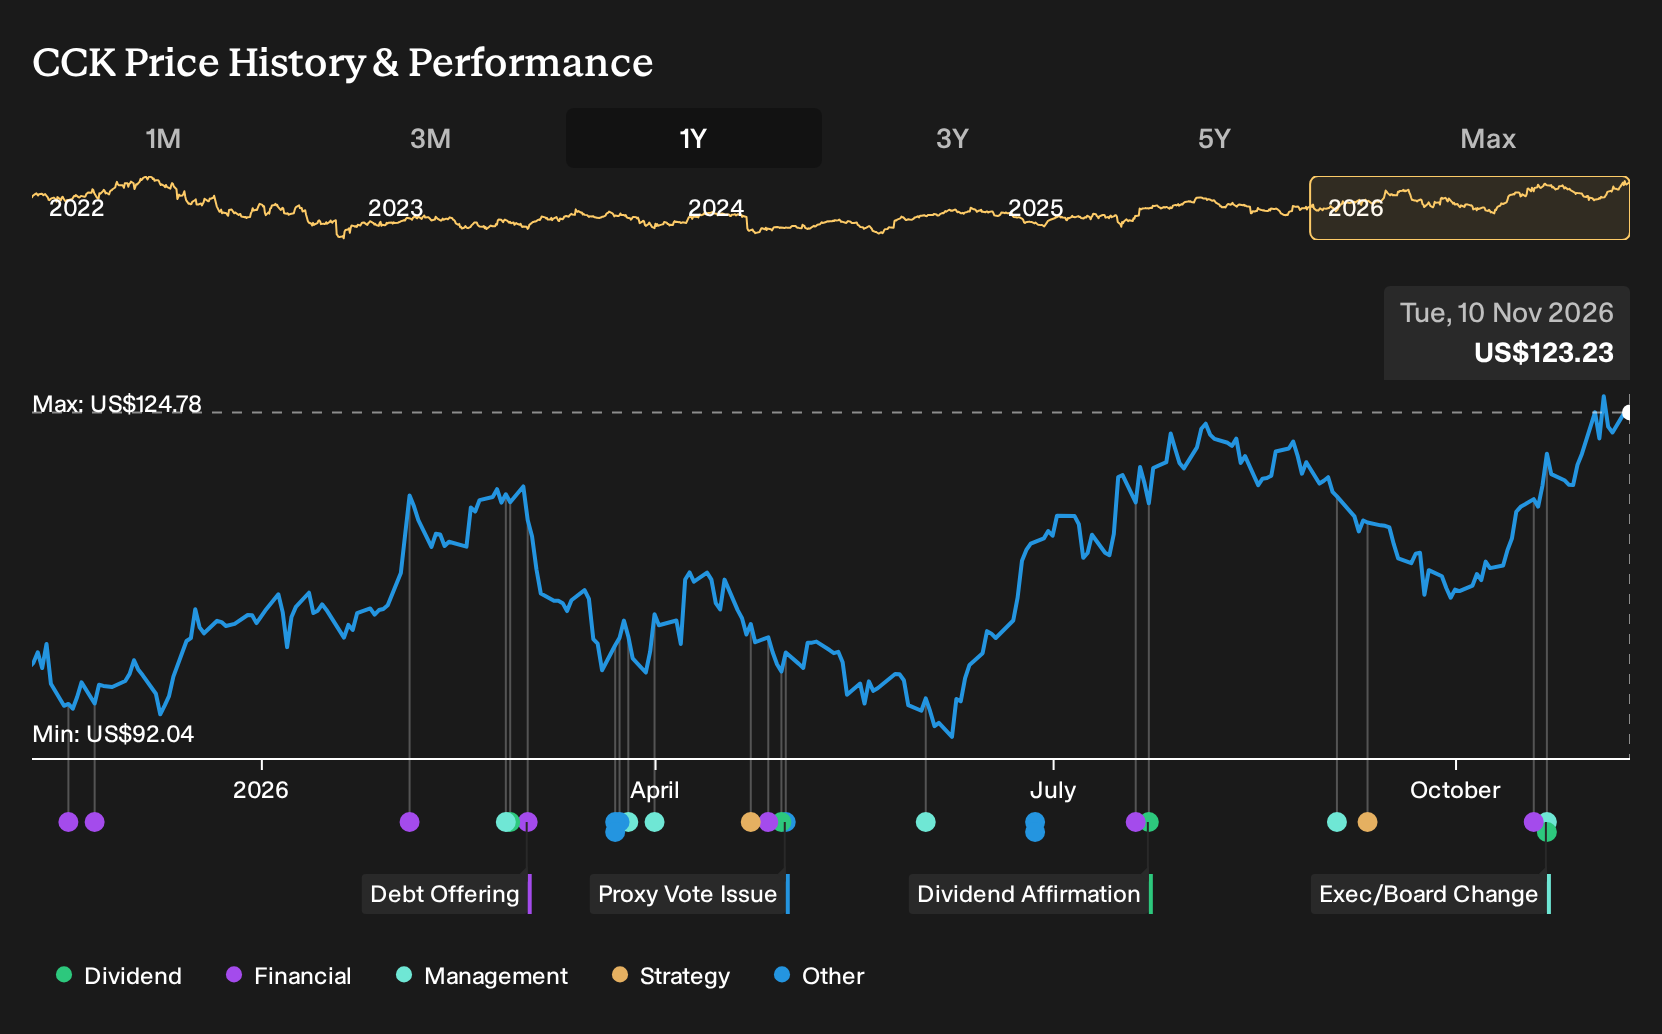
For an investor to own Crown Holdings, there needs to be confidence that demand for beverage cans and transit packaging keeps translating into healthy cash generation and that new capacity in regions such as Brazil, Greece, Spain and India is executed cleanly. The latest quarter, with revenue of US$3.71b up 15.9% year on year and earnings ahead of forecasts, supports that operational story rather than changing it.
The near term swing factor is how quickly recent volume strength normalises once temporary events, including things like major sporting tournaments, roll off from North America. On the risk side, higher freight, energy and industrial gas costs, along with Brazil softness, remain important watchpoints for margins even after this strong print.
The analyst consensus Narrative on Simply Wall St highlights several catalysts that frame this quarter. Management is investing about US$550m of 2026 capex into Brazil, Greece, Spain and a 2.2b can facility in India, with roughly 70% of that Indian volume under long term commitments. Those projects are central to the idea that Crown Holdings can continue serving demand for metal cans as customers look for recyclable packaging.
This investment program also sets a clear execution test. Construction timing, ramp up efficiency and how quickly these plants contribute to operating income all influence whether recent revenue strength flows through to cash generation in the way analysts expect. Any delay or cost overrun would matter for a business already carrying a high level of debt and facing input cost pressure.
Crown Holdings' current analyst narrative points to revenue of US$14.4b and earnings of US$937.0m by 2029, which aligns with a 2.9% yearly revenue growth assumption and an earnings increase of about US$153.0m from the US$784.0m reported today.
Uncover why Crown Holdings' fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community range from US$76 to more than US$386.3b, highlighting how widely opinions on Crown Holdings can differ. These figures predate the latest quarterly update, while risks around temporary can demand and higher freight and energy costs give you more angles to weigh. Explore these contrasting views and decide where you sit within that range.
Explore 3 other Crown Holdings fair value estimates, including one that suggests as much as 38% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Crown Holdings research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Crown Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Crown Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Crown Holdings?
Once you are comfortable with your view on Crown Holdings, it can help to widen the lens and line it up against other businesses that fit different risk and return profiles. The Simply Wall St Screener lets you filter by quality, balance sheet strength and dividend profile so you can build a watchlist that matches how you like to invest.
- If resilience matters most to you, start with a group of companies that score well on financial stability through our 30 resilient stocks with low risk scores.
- If you are hunting for strong balance sheets and cleaner fundamentals, narrow the field quickly using a list of solid balance sheet and fundamentals (24 results).
- If you want to cast the net wider for lesser known opportunities, scan a 20 high quality undiscovered gems that might deserve a spot on your radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com