


Avnet (AVT) is back in focus after first quarter results on November 4, 2026, showed sales of US$10.72b and net income of US$282.17m, alongside fresh guidance for the current quarter.
Despite the strong first quarter update, Avnet’s recent share price has cooled. The 30 day share price return is down 14.35% and the 90 day share price return is down 12.55%. This comes after a year to date share price gain of 72.48% and a 1 year total shareholder return of 86.17%, which suggests earlier momentum has eased while longer term holders have still seen substantial value creation.
Scan how Avnet’s earnings surprise compares with other potential breakouts by reviewing our curated list of 35 high quality undervalued stocks.
After a surge in earnings and guidance, followed by a sharp pullback in the share price, the key issue for Avnet now is simple. Does the current valuation still leave enough upside to justify the risk you take on from here?
Most Popular Narrative: 23.5% Undervalued
Against Avnet’s last close of $85.10, the analyst consensus Narrative on Simply Wall St anchors fair value at $111.25 and frames the current pullback as a discount that rests on specific growth, margin and risk assumptions.
Improving operating leverage and capital efficiency are now more visible, with adjusted operating income reported to be growing about 2.6x faster than sales, SG&A as a percentage of gross profit trending toward a sub 60% target and return on working capital reaching 19%, which together create room for further operating margin expansion and support for adjusted EPS growth.
See why 11 investors see Avnet as 24% undervalued.
Result: Fair Value of $111.25 (UNDERVALUED)
Still, the Avnet story can break if pressure on gross margins from Asia and memory exposure proves permanent, or if the recent share price surge unwinds sharply.
Find out about the key risks to this Avnet narrative.
Another View: Cash Flows Tell A Tougher Story
Avnet may screen as attractively priced on earnings, with a P/E of 12.4x against an estimated fair ratio of 33x and a peer average of 17.5x, yet the SWS DCF model paints a very different picture. On that cash flow view, an $85.10 share price sits well above an estimated future cash flow value of $23.50. That gap points to valuation risk if earnings quality and growth assumptions do not hold up over time.
Before leaning on either framework, it is worth seeing how the cash flow model is built and where your own expectations differ from the inputs the model uses. Look into how the SWS DCF model arrives at its fair value.
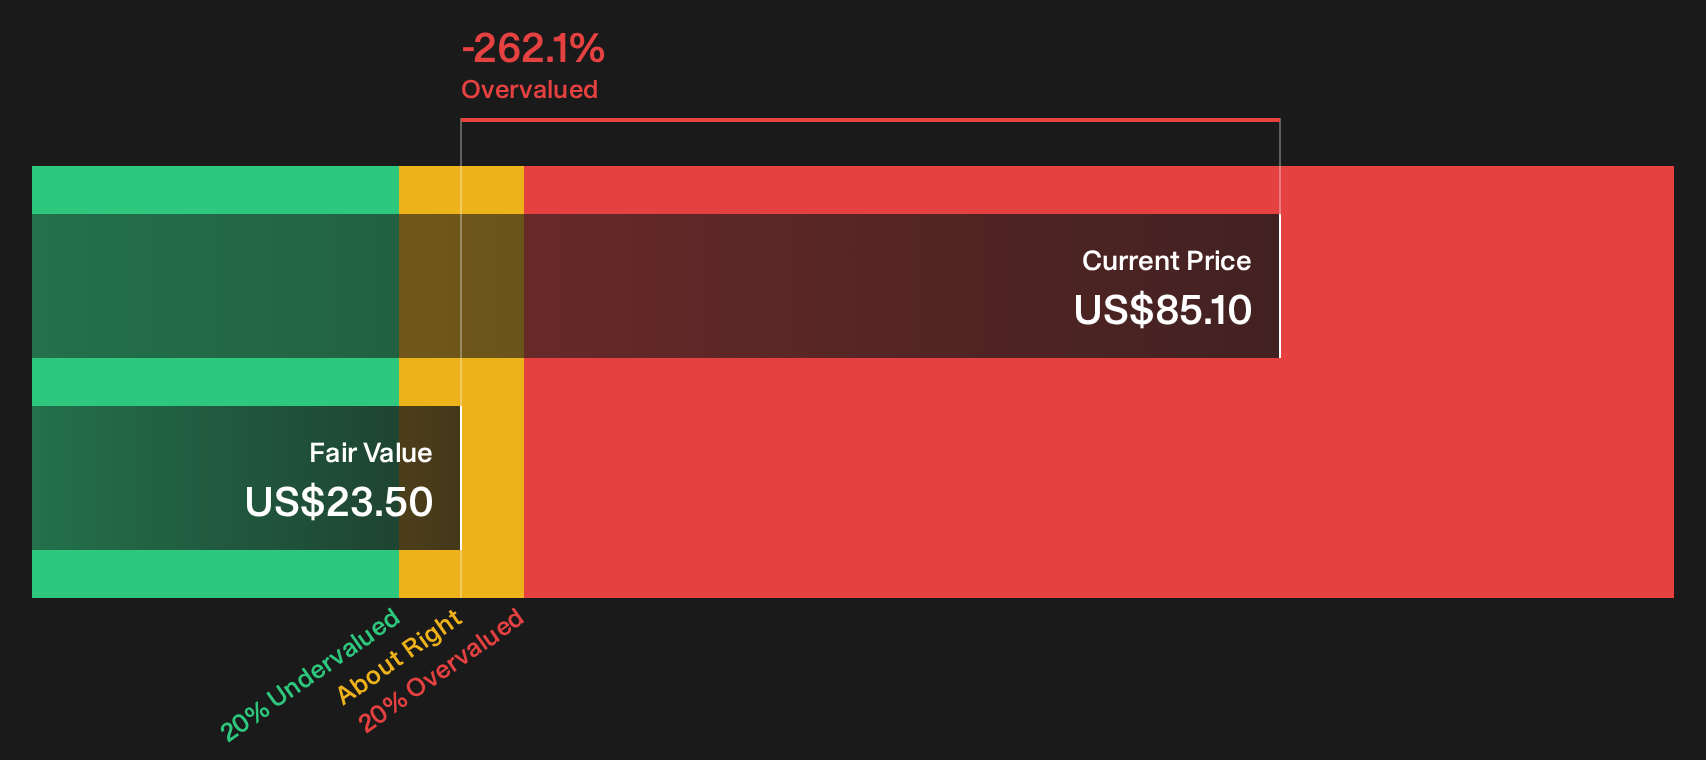
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Avnet for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed feelings about the mood of this Avnet story so far. Move quickly, compare the potential upside with the risks, and pressure test the thesis using the full picture of 5 key rewards and 2 important warning signs
Looking for more investment ideas beyond Avnet?
If Avnet’s setup has your attention, do not stop there. Use the same structured approach across fresh opportunities that match your risk appetite and income goals.
- Target steadier compounding by reviewing a curated pool of resilient companies in our 30 resilient stocks with low risk scores.
- Hunt for rising return potential by scanning a focused selection of 20 high quality undiscovered gems that pair quality fundamentals with market neglect.
- Build a sturdier core portfolio by filtering for balance sheets that can handle shocks using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com