


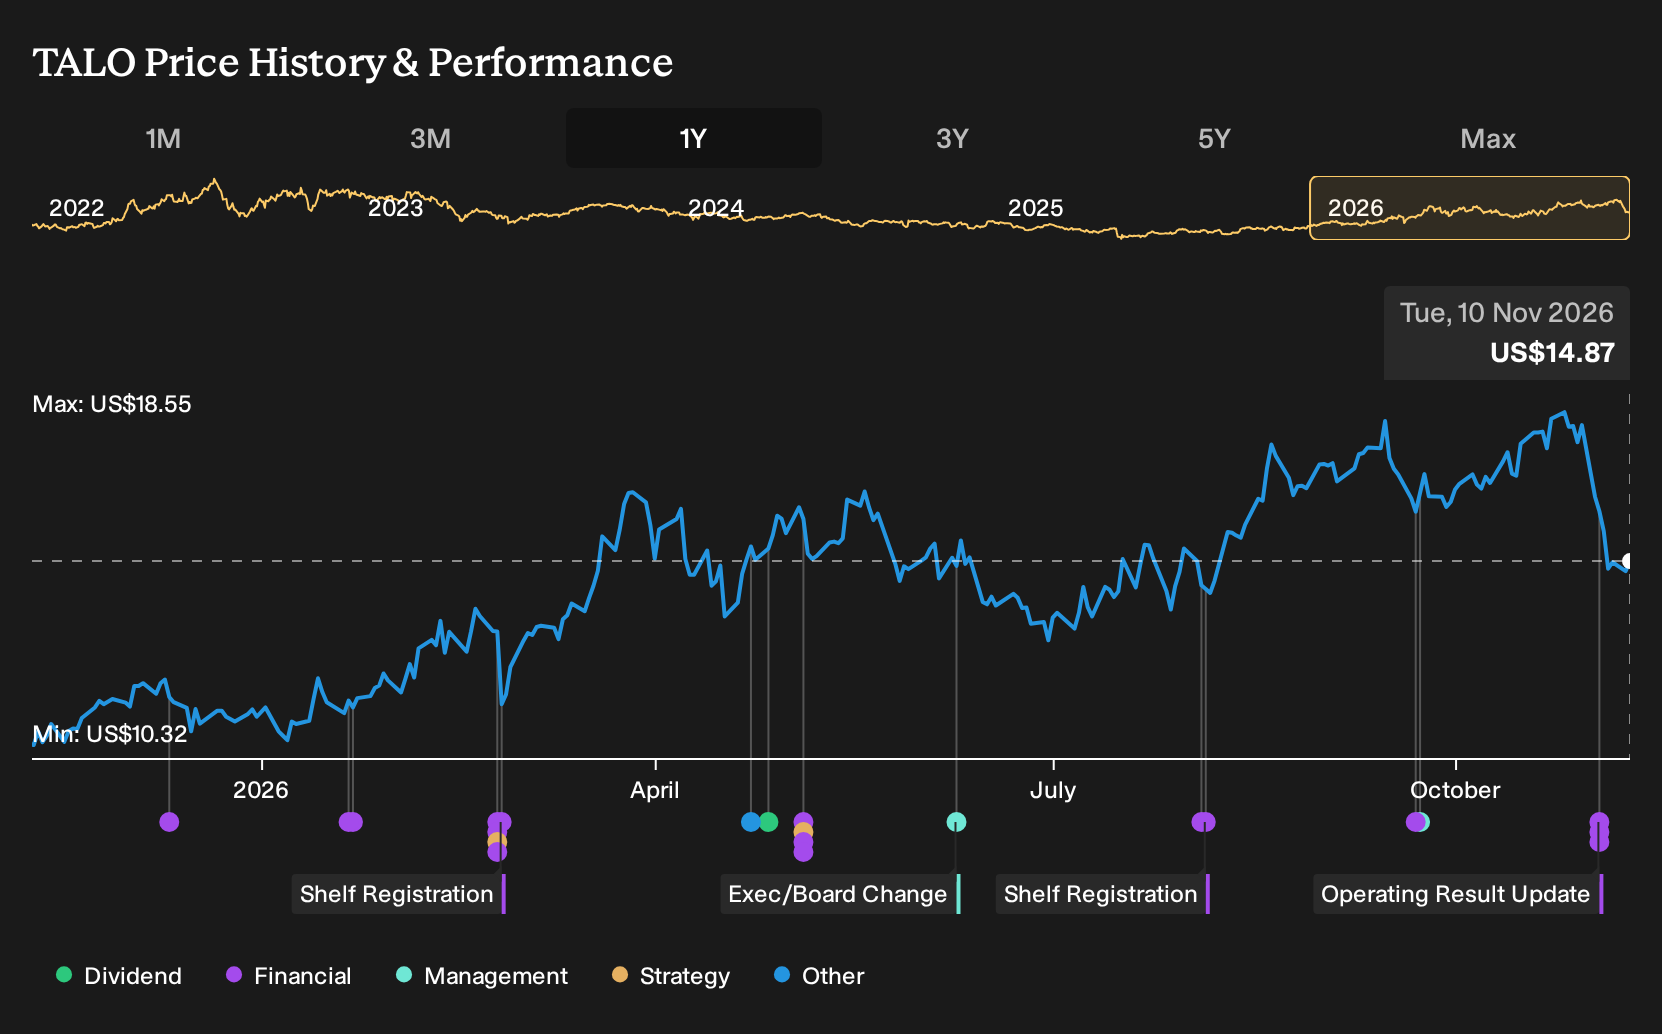
- Talos Energy raised its full year 2026 production guidance on November 3, 2026, and reported third quarter average net daily output of 91.5 MBoe/d with US$596.0 million in revenue and a reduced quarterly net loss of US$81.2 million.
- The combination of higher expected 2026 production volumes and rising year to date revenue alongside smaller losses indicates that Talos Energy is pushing more barrels through its Gulf asset base while still working through profitability challenges.
- We will now examine how Talos Energy's higher 2026 production guidance could reshape the existing investment narrative built around efficiency gains.
Talos Energy Investment Narrative Recap
Talos Energy appeals to investors who think scaling Gulf of Mexico production and squeezing out operating efficiencies can eventually support more durable cash generation. The higher 2026 production guidance backs that operating scale idea, but the business is still reporting losses, so the key short term catalyst remains clear progress on turning higher volumes into better unit economics.
The biggest risk is that heavier activity in the Gulf simply amplifies exposure to weather, regulatory obligations and high capital and decommissioning costs without a clear pay off in free cash flow. If cost discipline or project execution slip, the higher production outlook alone may not change the risk profile much.
The analyst consensus Narrative on Simply Wall St highlights Talos Energy's US$100 million per year efficiency push and Optimal Performance Plan as core to the thesis. In that context, the updated 2026 production guidance is the announcement that really matters because it indicates that the operational base those cost programs are being applied to is now expected to be larger.
That combination of more barrels and an ongoing savings plan sets up a clear operational test. Investors will want to see whether third quarter trends, including US$596.0 million of revenue and a smaller quarterly net loss of US$81.2 million, can extend into 2026 as volumes move toward the new 92.5 to 94.5 MBoe/d range without capex, abandonment and weather related costs eroding the benefit.
What The Forecasts Assume For Talos Energy
Talos Energy's current analyst narrative leans heavily on a specific earnings path. The consensus view points to revenue expanding at about 4.5% per year over the next three years and profits swinging from a reported loss of US$405.0 million today to forecast earnings of US$73.3 million by 2029. That shift implies an earnings improvement of about US$478 million, driven by a move in profit margins from a loss of 20.5% to a modest positive level of 3.2% in the same period.
Talos Energy's narrative projects US$2.3b revenue and US$73.3 million earnings by 2029. That scenario assumes 4.5% yearly revenue growth and an earnings increase of about US$478 million from current earnings of a US$405.0 million loss.
The 2029 framework in the report then ties those earnings back to the current share price through a specific valuation lens. To line up with the analyst targets, Talos Energy would be trading on a P/E multiple of 57.6x applied to those US$73.3 million of profits, compared with a reported current P/E of 7.5x on a loss-making base and a stated US Oil and Gas industry multiple of 12.4x. That is a steep step up in implied earnings quality and market confidence, which means any shortfall in profit delivery could have an outsized impact on how the stock is priced.
Consensus numbers in the report are also far from tight. Forecast earnings for 2029 range from a loss of US$10.2 million to a profit of US$381.0 million, which signals that analysts do not yet agree on how the Na Kika and Coulomb assets, Gulf of Mexico projects and cost programs will translate into the bottom line. For you as an investor, the spread between those earnings scenarios matters more than the single consensus point, because it highlights how sensitive Talos Energy's value case is to execution outcomes over the next few years.
On the revenue side, the path to that US$2.3b figure relies on steady compounding rather than a sudden jump. A 4.5% annual growth rate over several years is not extreme by itself. However, pairing it with a margin swing from a loss of 20.5% to a profit margin of 3.2% is a much bigger lift. That combination effectively asks Talos Energy to keep scaling production, hold discipline on capital and operating costs and manage Gulf specific risks without letting decommissioning and weather related expenses dilute the benefits of higher volume.
The report also layers in share count assumptions that feed into future earnings per share. Analysts expect the number of shares outstanding to shrink by 1.78% each year over the next three years, which would amplify any improvement in net income at the per share level. That links back to the existing buyback activity and suggests the earnings per share path in the Simply Wall St model depends not only on operating progress but also on continued capital returns.
Uncover why Talos Energy's fair value indicates a 45% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Bullish analysts frame Talos Energy’s higher 2026 production guidance as fuel for a stronger free cash flow story. Their pre news models already pencilled in revenue of about US$2.5b and earnings of roughly US$376.8 million by 2029, far above consensus. That reflects a much more optimistic view. You can treat this gap in expectations as a prompt to compare several viewpoints and decide which earnings path feels more realistic if guidance and recent quarterly results start to reshape those forecasts.
Explore 3 other Talos Energy fair value estimates, including one that suggests potential upside of up to 529% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Talos Energy research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Talos Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Talos Energy's overall financial health at a glance.
Looking for more investment ideas beyond Talos Energy?
Once you know where Talos Energy fits in your portfolio, it can help to line it up against other opportunities using the Simply Wall St Screener. That way you can compare different risk and return profiles side by side instead of treating this stock in isolation.
- If capital preservation sits high on your list, check out companies with steadier risk profiles through the 30 resilient stocks with low risk scores that might better match a more cautious approach.
- If you want income on top of potential price moves, scan for payouts with our focus on higher yielding opportunities using the 5 dividend fortresses and see which ones fit your return targets.
- If balance sheet strength matters most to you, start with businesses that pair solid finances with underlying fundamentals by running the list of solid balance sheet and fundamentals (24 results) and compare them directly to Talos Energy.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com