


Mosaic has jumped back onto investor screens after a sharp recent rebound in the share price, which puts fresh focus on whether the current US$22.99 level can be squared with the revenue the business is generating. With a mixed share price record over different time frames and a recent swing in sentiment around the stock, the key issue now is how that market enthusiasm lines up with its sales base.
- Over the past 5 years, Mosaic shareholders have seen the stock fall 29.7%. This makes the current rebound an important test of what investors are now willing to pay for each dollar of its sales.
- The company recently reported a net loss driven largely by cost pressure in its phosphate operations. This can affect how investors think about the quality and durability of the revenue that underpins any sales based valuation.
- The analysts covering Mosaic have run their own numbers. See what analysts think Mosaic's shares could be worth.
The stock's next move may depend on whether Mosaic's current market value looks sensible when stacked up against the sales the business is producing today.
If you are weighing Mosaic against other ways to play this theme, it can help to compare how the market is pricing a wider group of 35 high quality undervalued stocks.
Is Mosaic a Bargain on Sales?
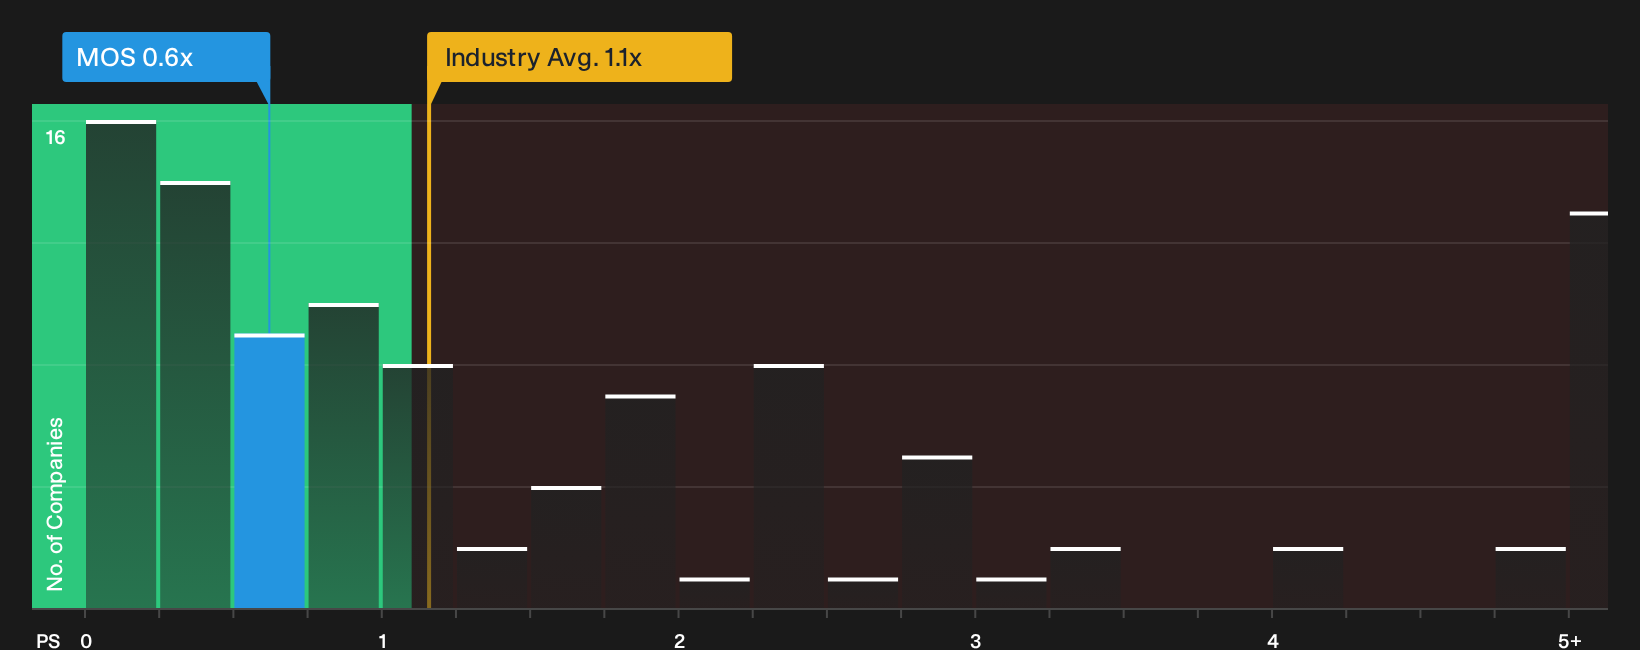
For Mosaic, a P/S lens fits because the fertilizer group is currently reporting losses, so sales give a cleaner anchor than earnings. On this measure, the stock trades on a P/S of 0.6x, against a Chemicals sector average of about 1.1x and a wider peer group closer to 1.5x. That places Mosaic at a marked discount to both its industry and more focused comparables on headline revenue.
Because the modeled fair P/S for Mosaic already bakes in its risk profile, margins and size, sitting below that mark points to the shares screening as undervalued on this framework. The recent Q3 2026 loss in phosphate and the stock’s sharp rebound have not closed that gap, so the market still prices each dollar of Mosaic’s sales below what this tailored yardstick suggests might be reasonable, leaving room for investors to judge whether the discount reflects temporary or more persistent concerns. Explore the numbers behind Mosaic's P/S valuation.
The Mosaic Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Mosaic's P/S puzzle leaves off. They spell out which paths for future growth, profitability and earnings would need to play out for the share price to look meaningfully higher or lower than today. Each scenario ties a fair value estimate to a clear story about Mosaic's possible catalysts and key risks, so you can track over time which version of events appears to be taking shape on the Community page.
Bulls and bears looking at Mosaic today are reading the same sulfur and phosphate story, yet drawing very different conclusions about what the current price reflects.
Bull case: 11% undervalued
This is how the analyst consensus Narrative on Simply Wall St frames the upside skew.
"The current valuation implies the share price does not fully reflect the potential cash flow from a tighter global phosphate market, a steady potash cash engine and growth in higher return specialty products…"
Discover why this Narrative puts Mosaic at 11% undervalued.
Bear case: 32% overvalued
The bearish analyst Narrative on Simply Wall St sees more strain than opportunity in the same setup.
"The numbers imply that Mosaic's share price embeds a rich valuation for a company guiding to phosphate production cuts, higher idle costs and a planned full year cash flow shortfall relative to capex and dividends in 2026…"
Explore why this Narrative puts Mosaic at 32% overvalued.
Before you finish on Mosaic, there is one more check worth your attention
Price can look appealing while other metrics quietly raise questions about resilience and balance sheet strength, so it is worth seeing which specific red flags our research has picked up before you make your own call. Take a closer look at 3 warning signs (2 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com