


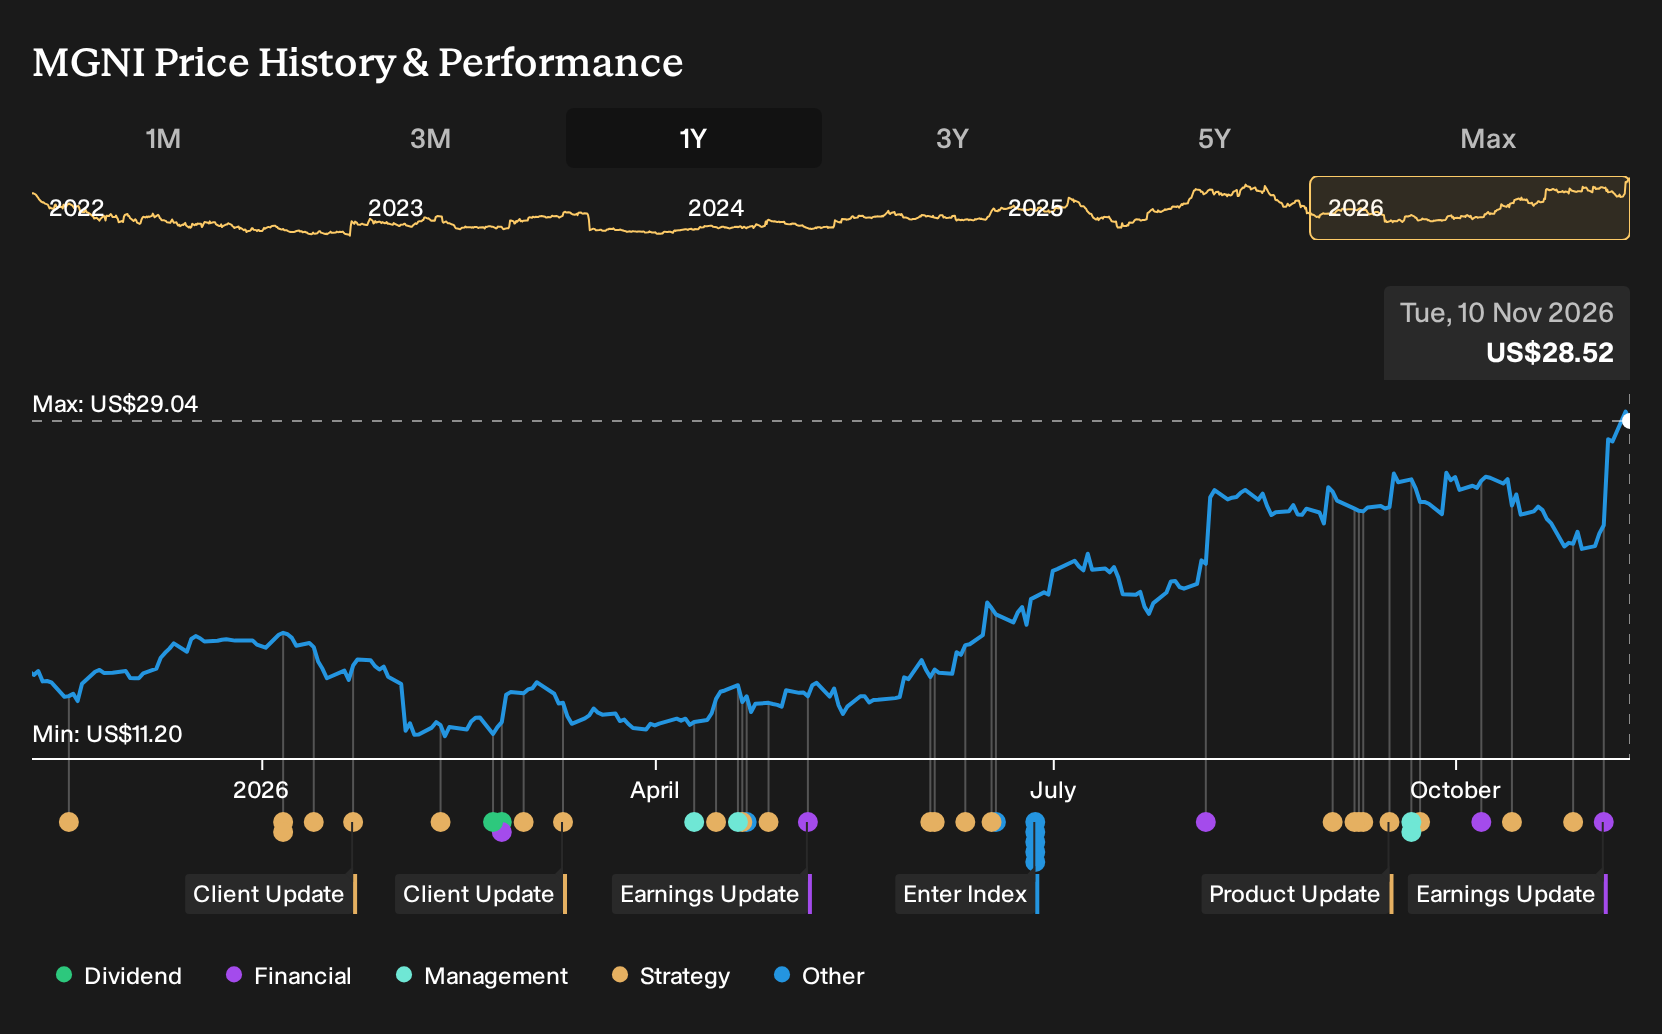
- Magnite reported third quarter 2026 sales of US$204.2 million and net income of US$34.01 million, alongside new CTV focused partnerships with Comscore and Gracenote that integrate Proximic’s Predictive Audiences and Gracenote’s content graph into the SpringServe platform.
- The Comscore and Gracenote agreements embed audience intelligence and privacy compliant targeting directly into Magnite’s CTV ad serving infrastructure, which affects how publishers package inventory and how advertisers reach high intent viewers across formats such as pause ads and seasonal campaigns.
- This article examines how Magnite’s investment narrative is influenced by this earnings performance and the deeper SpringServe CTV integrations.
Scan how Magnite’s CTV push compares with peers by zeroing in on hand-picked 53 AI infrastructure stocks benefiting from the same surge in data driven ad delivery and streaming demand.
Magnite Investment Narrative Recap
To stay invested in Magnite, you need to believe the shift of ad budgets into CTV and programmatic continues to matter more than the drag in weaker channels like web display. The analyst consensus Narrative on Simply Wall St focuses on Magnite turning its CTV footprint, commerce media ties and AI tooling into durable share gains and healthy contribution ex TAC.
The latest quarter, with US$204.2 million in sales and US$34.01 million in net income, supports a story of a business that is currently scaling while staying profitable. The biggest near term swing factor remains how tightly large CTV streamers and agency groups commit to Magnite, while the key risk is any pullback in ad budgets or tougher terms from those same partners.
The expanded Comscore integration appears closely connected to that thesis. Proximic’s Predictive Audiences now live directly inside Magnite’s SpringServe video platform, so publishers can combine their own viewership data with contextual signals and package highly specific CTV inventory, including pause ads and seasonal segments, without relying on user identifiers.
For investors, that matters because it turns SpringServe into more of an operating system for high intent connected TV campaigns. This aligns with the catalysts described in the analyst consensus Narrative on Simply Wall St. Execution risk lies in demonstrating that these richer data tools translate into durable spend from large streaming clients before macro or DV+ headwinds dilute the impact.
Magnite's analyst narrative points to US$983.5 million in revenue and US$159.4 million in earnings by 2029, anchored on forecasts of 8.7% yearly revenue growth and an earnings decline of US$21.4 million from US$180.8 million today.
Uncover how Magnite's fair value points to a 12% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One bearish twist you might want to weigh is how much Magnite can rely on CTV to offset softer DV+ web volumes. The most cautious analysts were modelling only 5.9% annual revenue growth and earnings of about US$61.5 million by 2029 before this news, which is far below consensus. That gap shows how sharply opinions differ and why it can help to explore several narratives that may shift as the new CTV data and earnings sink in.
Explore 3 other Magnite fair value estimates, including one that suggests as much as 19% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own research and judgment.
- A great starting point for your Magnite research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Magnite. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to evaluate Magnite's overall financial health at a glance.
Looking For More Investment Ideas Beyond Magnite?
Once you have formed a view on Magnite, it can help to cross check your thesis against other stocks with different risk profiles and balance sheet setups. The Simply Wall St Screener gives you a quick way to line up potential alternatives without spending hours trawling through raw filings.
- If capital preservation sits high on your list, focus on companies with steadier risk characteristics by scanning a set of 30 resilient stocks with low risk scores that may suit a more defensive approach.
- If you prefer to pay less for quality, filter for stronger fundamentals at undemanding prices by reviewing a curated 35 high quality undervalued stocks that might complement or contrast your Magnite view.
- If you are hunting for under the radar potential, broaden your watchlist with a targeted 20 high quality undiscovered gems that could bring fresher ideas into your research pipeline.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com