


Kadant (KAI) just put fresh numbers on the table, reporting third quarter results, updating its full year outlook, and laying out expectations for the upcoming quarter in early November.
The fresh outlook focuses on a stock that has just climbed 15.13% on a 1 month share price basis, even though the 3 month share price return is down 10.25%. This leaves Kadant at US$299.83 with a 1 year total shareholder return of 14.13%, indicating solid, but not explosive, momentum building after a softer stretch.
Scan how Kadant’s earnings momentum compares to other industrial operators with resilient balance sheets by reviewing our curated list of list of solid balance sheet and fundamentals (24 results)
So is Kadant’s sharp 1 month rebound mostly the market catching up to healthier earnings and guidance, or is it more about a mood shift that the current valuation still needs to justify?
Most Popular Narrative: 17.1% Undervalued
Kadant’s analyst consensus Narrative on Simply Wall St anchors fair value at about $361.67 per share, compared with the recent close of $299.83. This frames the current rebound against a valuation that still prices in a discount while relying on detailed earnings and revenue forecasts.
The aging installed base that Kadant supports is leading customers to spend more on maintenance and upgrades even when facilities are not running at peak utilization. Record aftermarket parts revenue of US$214.2m in Q2 2026 across segments points to a larger pool of recurring service activity that can support future revenue and earnings quality.
See why 0 investors see Kadant as 17% undervalued.
Result: Fair Value of $361.67 (UNDERVALUED)
Still, the bullish Kadant story weakens quickly if lower gross margins from mix and acquisition costs persist, or if Europe’s challenging project environment continues to hinder backlog conversion.
Find out about the key risks to this Kadant narrative.
Another View: What Kadant’s P/E Is Telling You
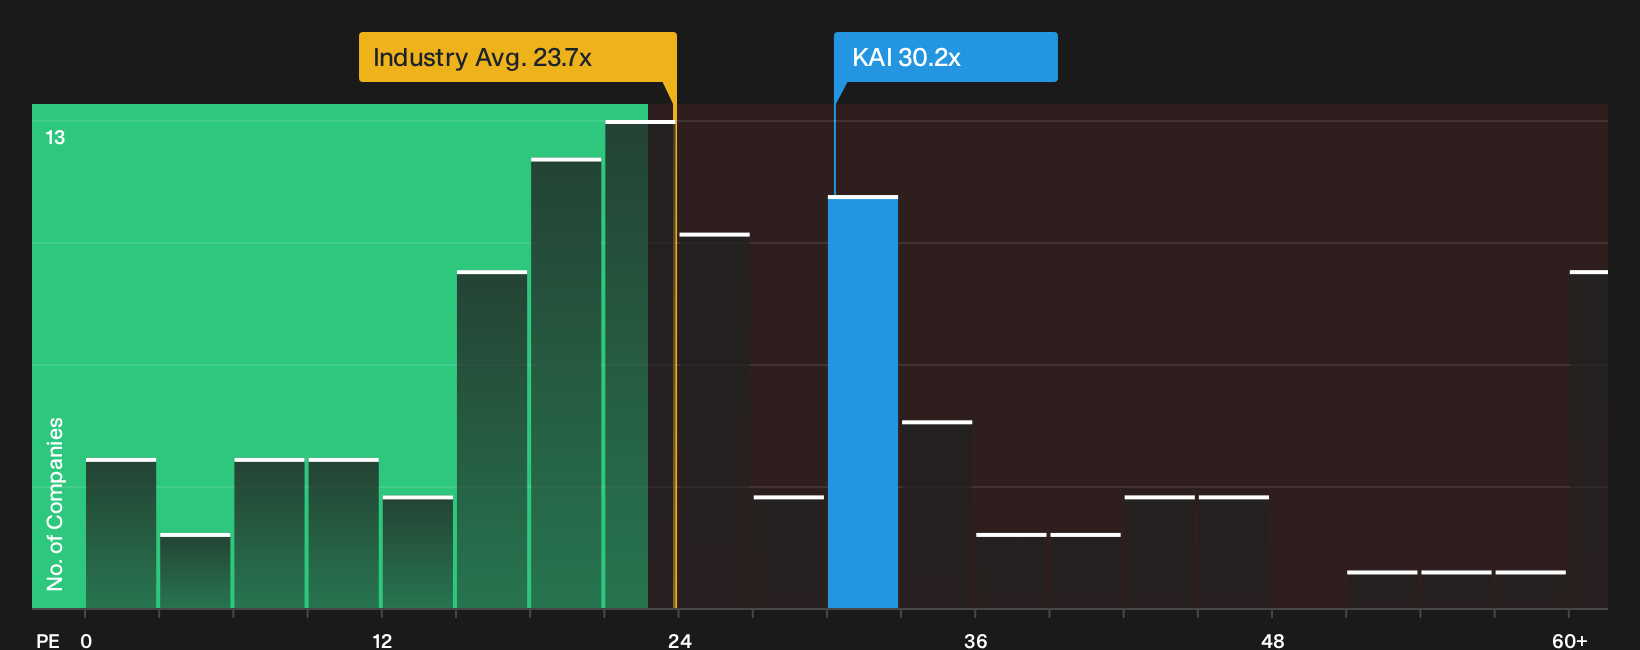
The DCF based fair value points to Kadant trading about 5.9% below an estimated future cash flow value, yet the earnings multiple sends a different message. The stock changes hands at a P/E of 30.2x, compared with 24.1x for the US Machinery industry and 20.8x for peers, while the fair ratio is 22.6x.
That gap means investors are currently paying a premium price for each dollar of Kadant earnings even though the fair ratio suggests the P/E could move closer to 22.6x over time. The key question is whether the aftermarket story and backlog are strong enough to keep justifying that richer tag, or if the multiple eventually does the adjusting instead.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling encouraged by the tone so far, or still unsure where Kadant really sits on your watchlist today? Act while the numbers are fresh in mind and pressure test the bullish angles for yourself by reviewing the 3 key rewards.
Looking for more investment ideas beyond Kadant?
If Kadant has sharpened your focus today, do not stop there. Widen your watchlist with a few targeted stock pools sourced directly from the Simply Wall St Screener.
- Target potential mispricing and sift for companies where quality and value intersect by reviewing the 35 high quality undervalued stocks.
- Build a sturdier portfolio backbone and filter for payouts that may complement your total return plan using the 5 dividend fortresses.
- Reduce unwanted portfolio surprises and zero in on companies with stronger financial resilience through the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com