


- Fuyo General Lease reported half year results for the period to September 30, 2026, with sales of ¥392,249 million, net income of ¥20,274 million, and basic earnings per share from continuing operations of ¥224.7.
- The sharp step up in net income relative to the prior half year indicates a notable change in profitability and operating leverage for Fuyo General Lease.
- The key question now is how Fuyo General Lease's much higher half year net income reshapes the existing investment narrative investors have been using.
Scan how Fuyo General Lease's sharp earnings shift compares with peers by reviewing our curated list of 72 high quality undiscovered gems that could be pricing in similar inflection points.
What Is Fuyo General Lease's Investment Narrative?
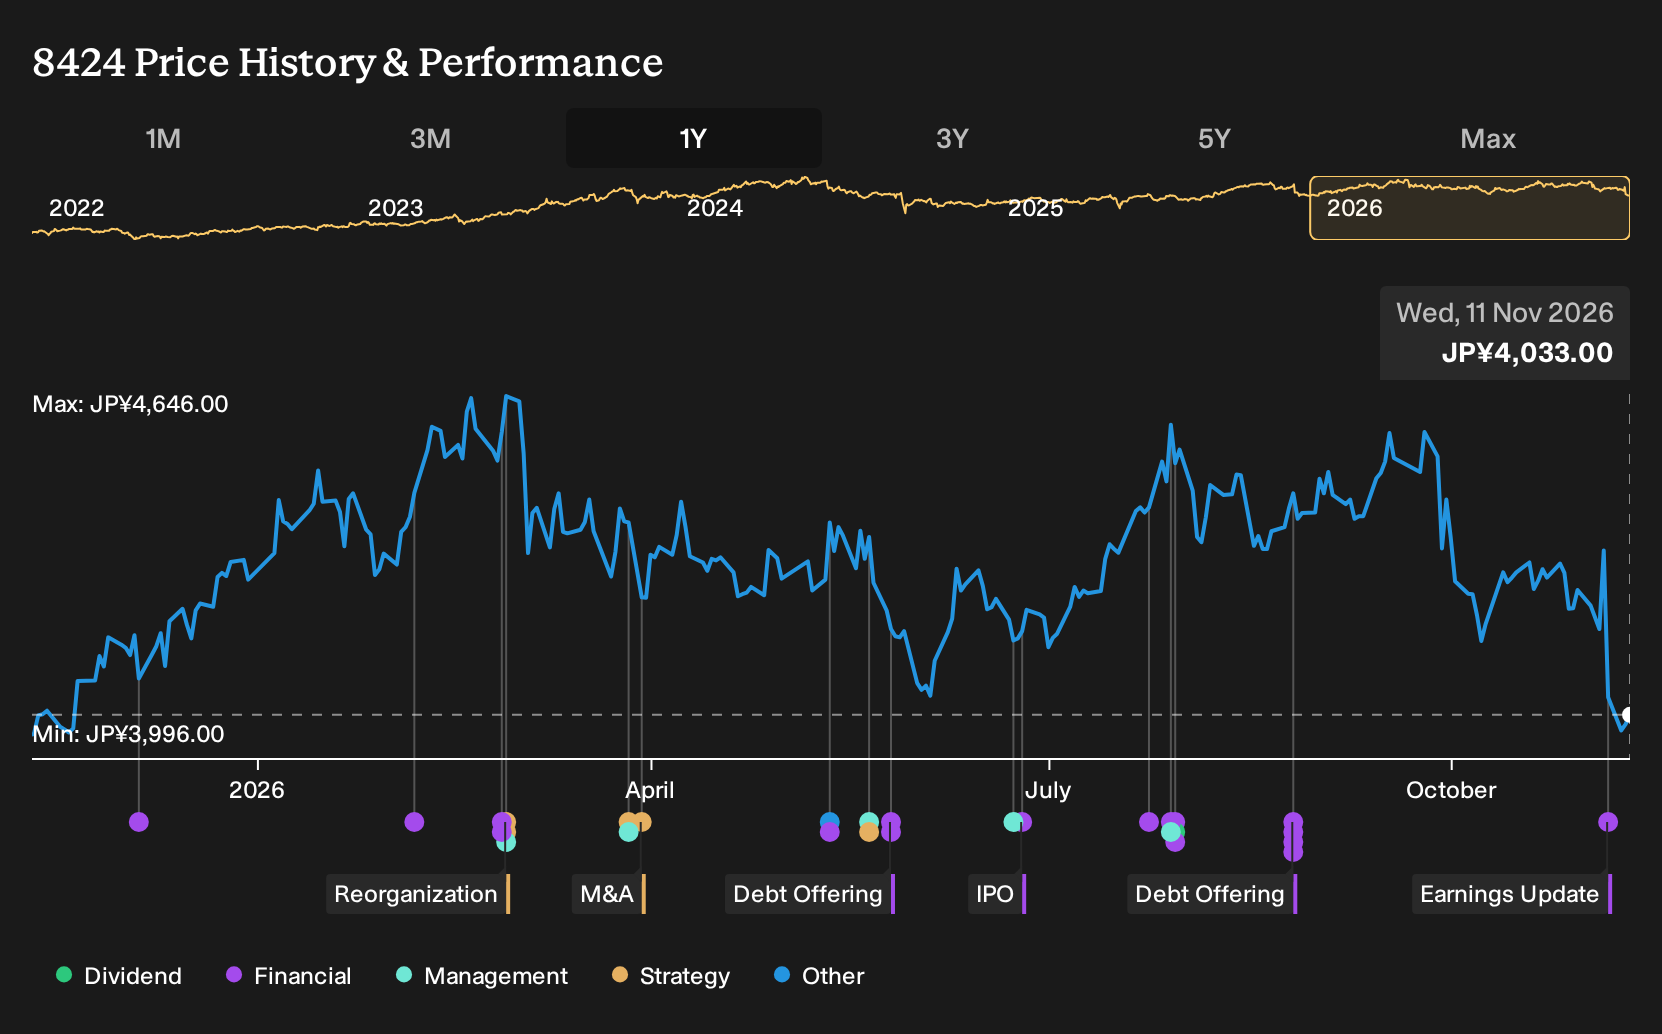
To own Fuyo General Lease, you need to be comfortable with a capital intensive finance model where balance sheet strength and disciplined risk control do as much work as headline earnings. The latest half year numbers, with sales of ¥392,249 million and net income of ¥20,274 million, point to powerful operating leverage in the current set up. In the short term, that kind of profit jump can support confidence in demand, pricing and underwriting, even as the share price has slipped around 10% over the past three months and trades on a P/E of 9.8x that screens as good value versus peers.
Execution risk has not gone away though. Debt is described as not well covered by operating cash flow and 100% of funding comes from higher risk borrowing, which matters when the dividend yield of 4.26% is not well covered by free cash flows. Forecasts that call for earnings growth and revenue contraction over the next few years make this latest earnings beat feel more like a test of how repeatable the current return profile really is for Fuyo General Lease rather than a clean reset of the risk picture.
Even so, there is a structural pressure point in this model that could become hard to ignore if ...
There's only one way to know the right time to buy, sell or hold Fuyo General Lease. Head to Simply Wall St's company report for the latest analysis of Fuyo General Lease's Fair Value.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Fuyo General Lease research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Fuyo General Lease. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fuyo General Lease's overall financial health at a glance.
Looking For More Investment Ideas Beyond Fuyo General Lease?
If the latest move in Fuyo General Lease has you reassessing where fresh capital might work hardest, it can help to compare it with a wider field of potential opportunities using filters that match your risk and income preferences.
- If capital preservation matters most to you, you could focus on companies that pair resilience with measured risk profiles by starting with a curated set of 19 resilient stocks with low risk scores.
- For investors looking for quality at a reasonable price, you can target stronger fundamentals that still look attractively priced through a broad sweep of 23 high quality undervalued stocks.
- Income focused portfolios can be built out further by scanning for yields that aim to balance payout and stability, using a hand picked universe of 29 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com