


nLIGHT (LASR) stepped into the spotlight after third quarter 2026 results showed revenue of US$73.76 million and a loss of US$7.18 million, alongside fresh fourth quarter guidance and a sharp share price reaction.
That earnings surprise has come on top of a sharp short term rebound, with nLIGHT’s 7 day share price return of 20.51% and 30 day gain of 14.35% partly offsetting a 90 day decline of 17.04%, while the 3 year total shareholder return of around 3x suggests momentum that has built over a longer stretch.
Scan how nLIGHT’s latest move compares with other defense focused contractors by reviewing the curated 30 resilient stocks with low risk scores, which combines resilient balance sheets with measured risk profiles.
After that surge and with nLIGHT trading below both analyst targets and some intrinsic value models, the gap between price and paper estimates has widened. How much of that spread still points to upside, and how much reflects risk repricing?
Most Popular Narrative: 46% Undervalued
On the analyst consensus Narrative on Simply Wall St, nLIGHT screens as materially undervalued, with a fair value of $82.13 against the last close at $44.00, and that gap is tied directly to defense laser and sensing contracts rather than broad tech optimism.
Analysts expect nLIGHT to keep benefiting from multi-year directed energy and sensing programs, with defense remaining the main driver of revenue and mix shift. The main factor that must go right is successful execution on large U.S. laser weapon and sensing contracts while managing the exit from legacy cutting and welding revenue and Chinese supply chain risk.
See why 16 investors see nLIGHT as 46% undervalued.
Result: Fair Value of $82.13 (UNDERVALUED)
Still, supply chain scrutiny that pushed about US$17 million of revenue out of Q3 2026 and the ongoing losses leave this nLIGHT narrative exposed if disruptions persist.
Find out about the key risks to this nLIGHT narrative.
Another View On nLIGHT’s Valuation
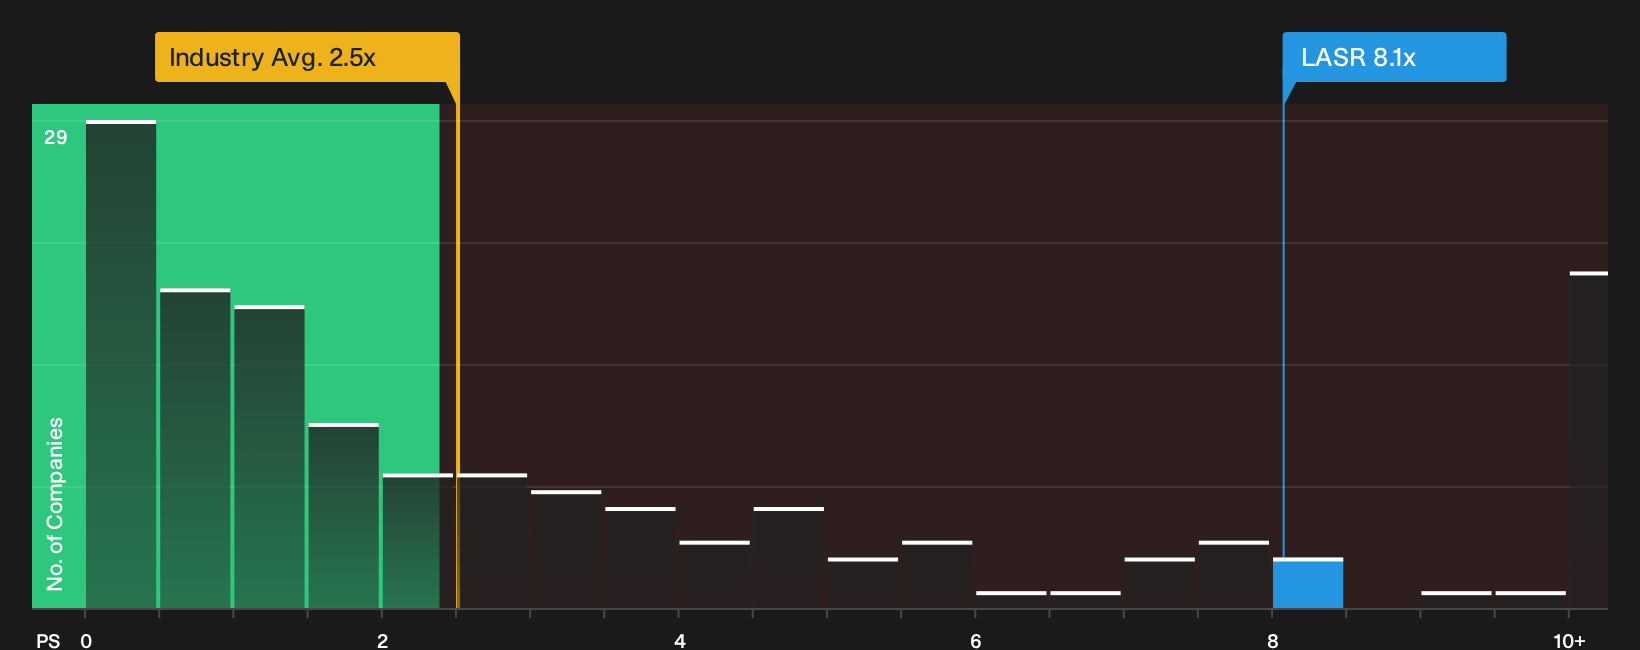
The story looks very different when you shift from the fair value estimate to simple P/S math. nLIGHT changes hands at about 8.1x sales, compared with 2.5x for the wider US Electronic industry, 4.5x for peers, and a fair ratio of 1.7x that the market could eventually lean toward. That kind of gap raises a practical question for you as an investor. Is the premium a price you are comfortable paying for the directed energy narrative, or a valuation risk you would rather avoid?
To see how those P/S signals stack up in more detail, including where the ratio sits relative to peers and the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on nLIGHT is mixed, with optimism and concern pulling in different directions. Treat this as a prompt to stress test the numbers yourself and sharpen your own view using the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond nLIGHT?
If nLIGHT has sharpened your focus on opportunities, do not stop here. The wider market still holds plenty of ideas you will want on your radar.
- Target potential mispricings by scanning for quality companies trading below their implied worth through the 35 high quality undervalued stocks.
- Build a steadier income stream by reviewing companies in the 5 dividend fortresses that combine higher yields with disciplined payout histories.
- Strengthen your shortlist with financially robust candidates by running the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com