


Uranium Energy (UEC) has moved into the spotlight after committing a US$12 million investment to Paraguay’s uranium sector, just as the country faces impeachment proceedings and a banking crisis.
At a share price of US$7.17, Uranium Energy has seen short term momentum fade, with the 30 day share price return down 21.98% and the year to date move lower by 45.31%. However, the 5 year total shareholder return of 46.93% still points to a very different long haul experience.
Scan 17 nuclear energy infrastructure stocks to see which peers are also trying to turn nuclear infrastructure headlines, such as Uranium Energy's Paraguay move, into long term portfolio drivers.
Optimists see Uranium Energy using Paraguay as a launchpad, while sceptics focus on political risk, recent share price declines and ongoing losses. Which side does the valuation math lean toward next?
Most Popular Narrative: 72% Undervalued
Against a last close of $7.17 for Uranium Energy, the most popular bullish analyst Narrative on Simply Wall St anchors on a Fair Value of $25.96 using a 7.24% discount rate. It frames the gap as a bet on vertical integration and conversion capacity.
Expansion of United States Uranium Refining & Conversion Corp with a 63 person technical team, an NRC docket in place and a Class 4 cost estimate targeted for mid 2027 creates room for Uranium Energy to earn future fees from conversion services that could influence revenue and earnings mix once the facility is operational.
Use of roughly 12 million pounds per year of licensed processing capacity across Sweetwater, Irigaray and Hobson gives Uranium Energy headroom to connect new wellfields and satellite mines. This can change the volume of pounds that flow through the plants and affect revenue scale and fixed cost absorption.
See why 14 investors see Uranium Energy as 72% undervalued.
Result: Fair Value of $25.96 (UNDERVALUED)
Still, the bullish Uranium Energy story depends on execution. Persistent losses and any reset in the premium valuation could quickly flip this narrative on its head.
Find out about the key risks to this Uranium Energy narrative.
Another View: Uranium Energy On Cash Flows
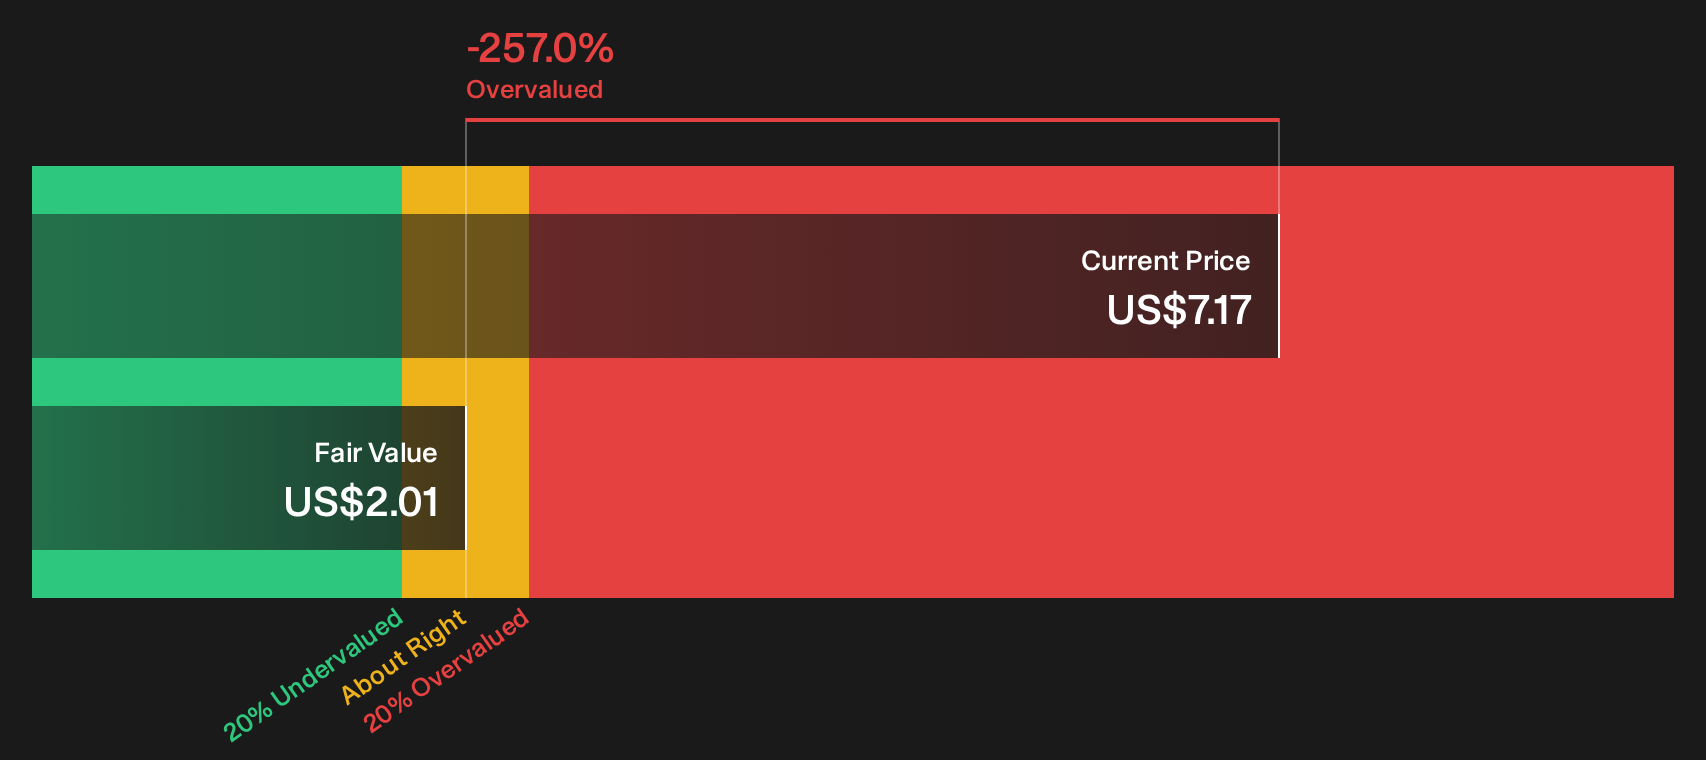
The bullish narrative pegs Uranium Energy at a Fair Value of $25.96, yet the Simply Wall St DCF model points in the opposite direction. On that cash flow lens, UEC at $7.17 trades above an estimated future cash flow value of $2.01, which flags valuation risk rather than a safety margin. Which story do you trust when the price already leans rich on this framework?
Our DCF model spells out the gap in detail, including the discount rate assumptions and cash flow path that produce that $2.01 figure. Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Uranium Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and caution around Uranium Energy leaves you undecided, move quickly to review the numbers and examine the upbeat case yourself. To see what is driving that optimism, start with the 1 key reward.
Looking for more investment ideas beyond Uranium Energy?
If Uranium Energy has your attention, do not stop here. Broaden your watchlist with fresh ideas that line up with the type of opportunities you want.
- Target potential bargain opportunities early by reviewing the 20 high quality undiscovered gems that combine solid fundamentals with quieter headlines.
- Strengthen portfolio resilience by focusing on companies with robust finances using the list of solid balance sheet and fundamentals (24 results) that filters for balance sheets built to handle stress.
- Dial down volatility risk by checking the 30 resilient stocks with low risk scores that highlights resilient businesses with lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com