


Texas Pacific Land (TPL) is back in focus after its latest update, as record oil and gas royalty production, double digit revenue and net income growth, and a new dividend affirmation sharpen investor attention.
Despite the strong Q3 headlines, Texas Pacific Land’s recent trading tells a different story, with the share price down 23.9% over the past 30 days and 19.9% over 90 days, while the 5 year total shareholder return of 102.4% points to a much stronger long-run record.
Scan Texas Pacific Land’s latest move against a curated group of royalty and resource owners by checking the 20 high quality undiscovered gems, which analysts often watch for under-the-radar momentum.
Texas Pacific Land just paired record royalties with a sharp share price slide. Strong business, weaker stock chart. The real tension now is simple: Are investors finally getting a reasonable entry price or still paying up?
Most Popular Narrative: 38% Undervalued
On the analyst consensus Narrative on Simply Wall St, Texas Pacific Land’s fair value sits at $443, well above the last close of $274.63. That gap frames a view where recent price weakness contrasts sharply with expectations for future cash flows, built on detailed earnings and revenue forecasts.
The main thing that has to go right is that Texas Pacific Land turns its strong surface, water and produced water position into durable earnings from infrastructure, desalination and power or data center uses, while managing environmental and political scrutiny.
Current figures and recent share price moves together imply that the market prices Texas Pacific Land as a premium royalty and surface platform, even though this narrative views the stock as undervalued and still exposed to commodity and activity swings.
See why 34 investors see Texas Pacific Land as 38% undervalued.
Result: Fair Value of $443 (UNDERVALUED)
Still, if Permian drilling activity shifts or Texas data center and power projects face longer permitting delays, the bullish Texas Pacific Land narrative could easily cool.
Find out about the key risks to this Texas Pacific Land narrative.
Another View: Texas Pacific Land Through The P/E Lens
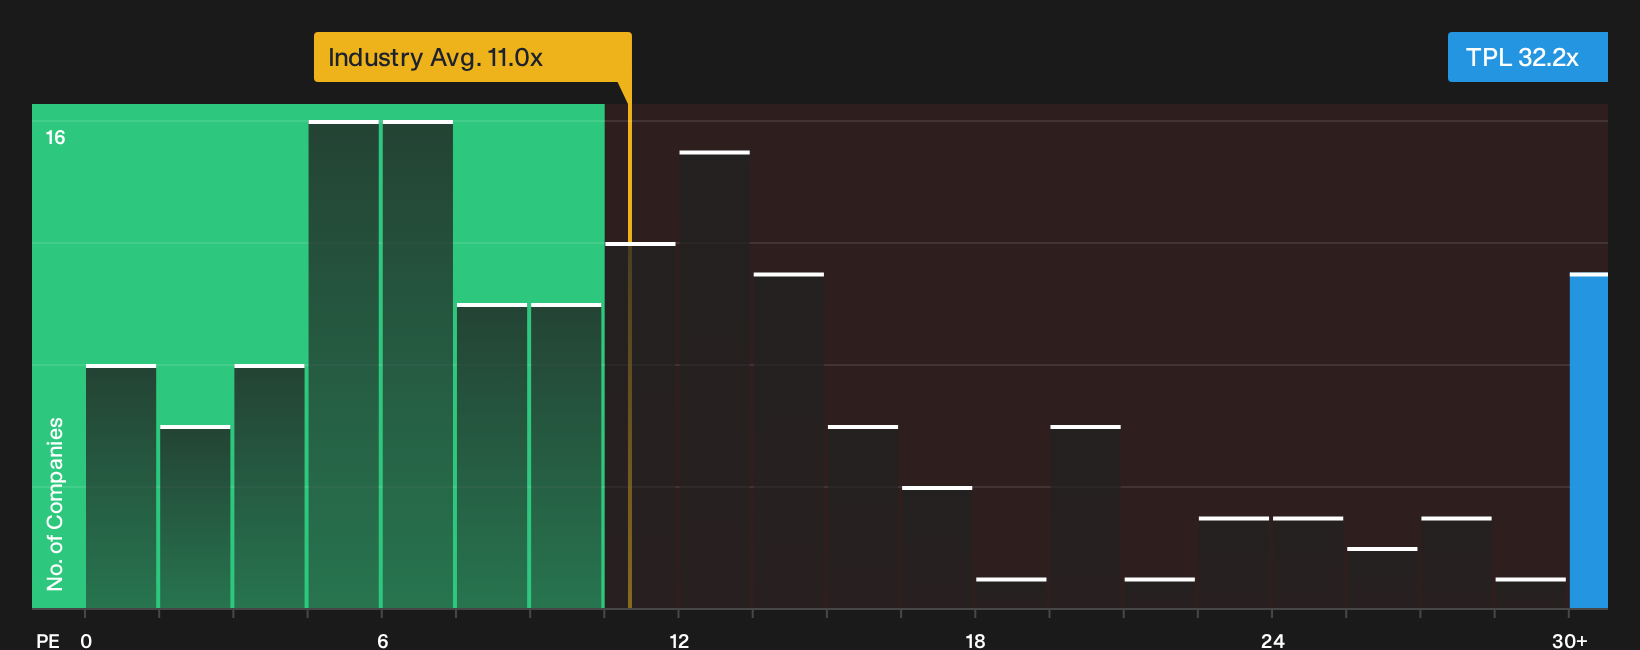
There is a catch. On a simple earnings multiple, Texas Pacific Land trades on a P/E of 32.2x, while the US Oil and Gas industry sits near 11x and the stock’s own fair ratio is 17.6x. That pricing leaves far less room for disappointment if forecasts or sentiment shift.
To see how the current tag compares with the underlying numbers and what might need to change for the market to move closer to that fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Does the cautious tone in this Texas Pacific Land update match your own read of the situation, or does it feel too optimistic or too harsh? Act while the data is fresh and decide where you land by weighing the 3 key rewards and 1 important warning sign.
Looking for more Texas Pacific Land style investment ideas?
If Texas Pacific Land has sharpened your focus on quality and price, do not stop here. Use fresh data, widen your watchlist, and keep your edge.
- Target resilient balance sheets by scanning companies with strong cash positions and low leverage through the list of solid balance sheet and fundamentals (24 results).
- Zero in on potential value opportunities by reviewing the 35 high quality undervalued stocks that combine quality fundamentals with pricing that trails underlying metrics.
- Prioritize stability and income by assessing companies in the 5 dividend fortresses that pair higher yields with robust financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com