


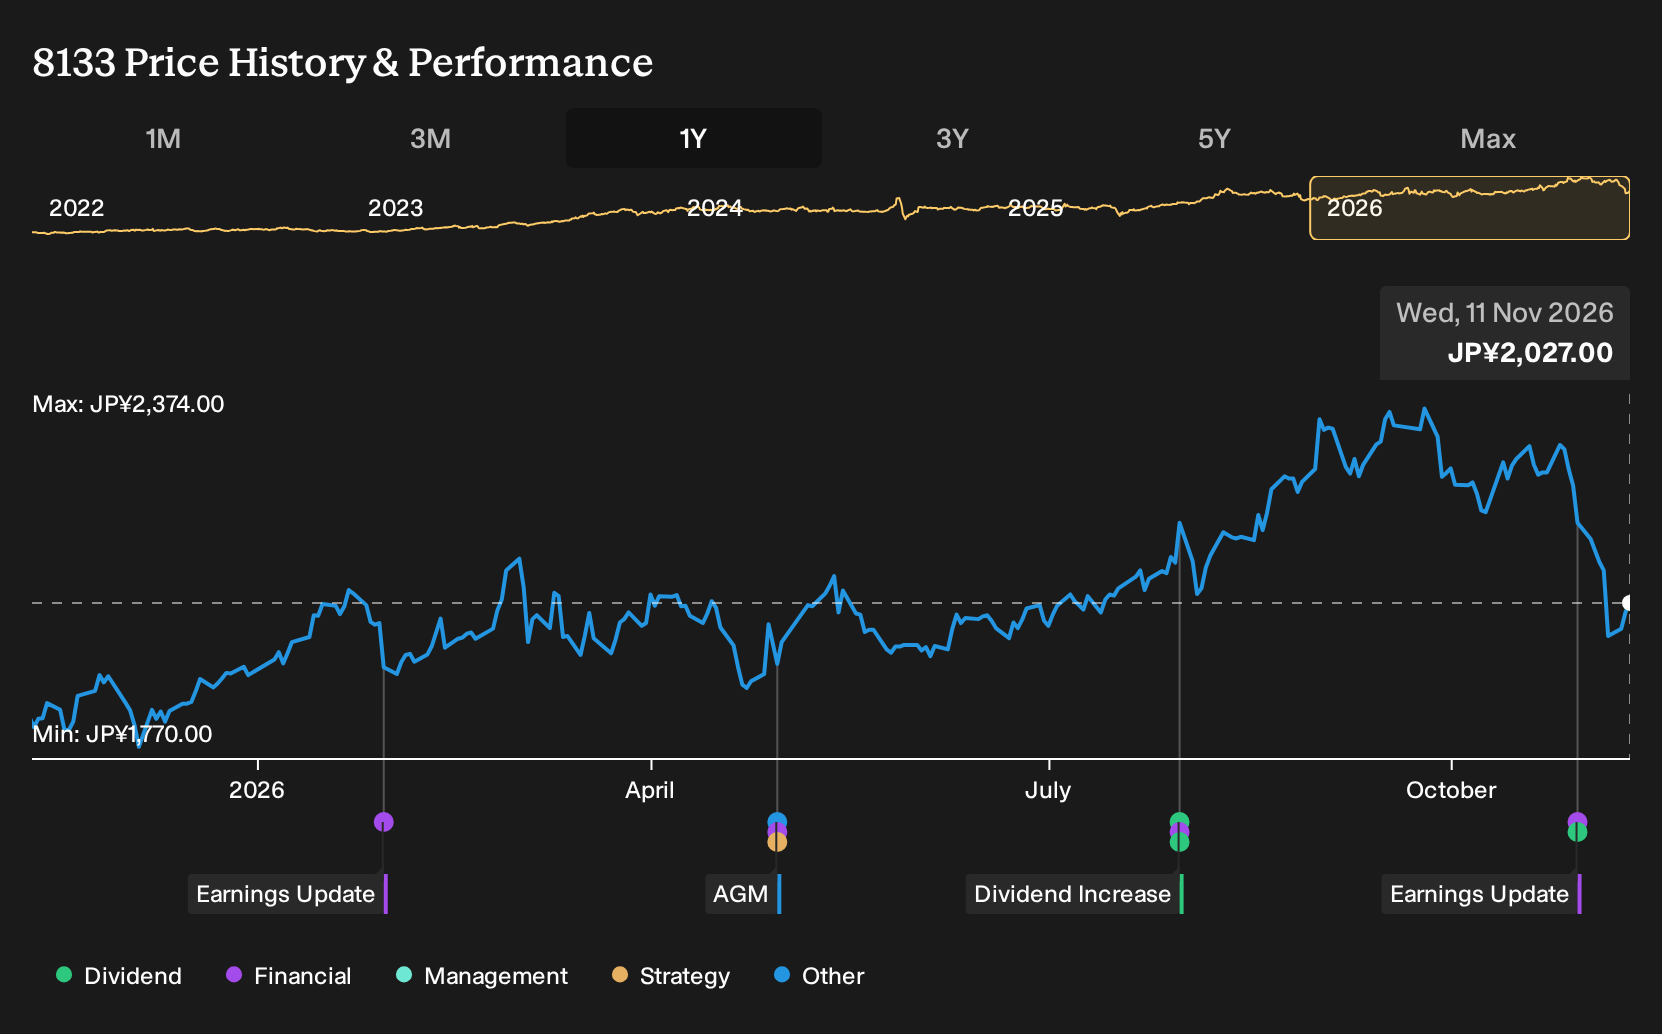
- Itochu Enex reported half year sales of JPY 476,283 million and net income of JPY 14,586 million, with basic earnings per share from continuing operations of JPY 129.17, alongside a second quarter-end dividend of JPY 34.00 per share payable on December 4, 2026.
- The combination of higher half year profitability versus a year earlier and a larger interim dividend reflects management’s current emphasis on returning cash while the underlying business scales.
- The focus now turns to how Itochu Enex's stronger earnings profile and increased dividend may influence the broader investment narrative.
What Is Itochu EnexLtd's Investment Narrative?
To own Itochu EnexLtd, you need to be comfortable with a fairly traditional energy and fuel distribution business that is trying to push earnings efficiency, not just chase volume. The half year print, with ¥476,283 million in sales and ¥14,586 million in net income, plus a higher interim payout of ¥34.00 per share, points to a management team leaning into cash generation and shareholder returns. That matters for the nearer term because it signals confidence in current operations rather than a need to hoard capital.
The bigger question for you is how durable that earnings profile looks across its four segments, from Car Life to Power and Utility, given the capital heavy nature of fuel infrastructure and power assets. Recent earnings growth, stronger net profit margins and a dividend that screens as reliable help offset share price weakness over the past 1 to 3 months. Yet the lack of forward guidance, the relatively new board and management team, and reliance on higher risk funding sources together create a backdrop where...
There's only one way to know the right time to buy, sell or hold Itochu EnexLtd. Head to Simply Wall St's company report for the latest analysis of Itochu EnexLtd's Fair Value.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Itochu EnexLtd research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Itochu EnexLtd. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Itochu EnexLtd's overall financial health at a glance.
Looking For More Investment Ideas Beyond Itochu EnexLtd?
If the earnings and dividend profile at Itochu EnexLtd has caught your attention, it can help to put it in context by scanning other companies with clear income or quality angles. Use the Simply Wall St Screener to build a wider watchlist that matches your own preferences rather than relying on a single stock story.
- For investors who want income with resilience, start with a curated set of businesses that currently screen as 29 dividend fortresses.
- If value is your priority and you are hunting for quality at a sensible price, filter the market through our 23 high quality undervalued stocks to see what else fits your checklist.
- When balance sheet strength is non negotiable, focus on companies in the list of solid balance sheet and fundamentals (23 results) and see which ones deserve a place on your radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com