


Valued at $20.6 billion by market cap, First Solar, Inc. (FSLR) is a prominent solar technology company specialising in the design, manufacturing, and sale of photovoltaic (PV) solar modules. Headquartered in Tempe, Arizona, the company is the world's largest manufacturer of thin-film solar modules and the largest PV module manufacturer in the Western Hemisphere.
Shares of this renewable giant have underperformed the broader market over the past year. FSLR has declined 33.6% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 10.1%. However, in 2026, FSLR stock is down 30.7%, compared to the SPX’s 9.9% rise on a YTD basis.
Narrowing the focus, FSLR has also trailed the Invesco Solar ETF (TAN). The exchange-traded fund has dipped about 17.7% over the past year and 11.4% in this year.
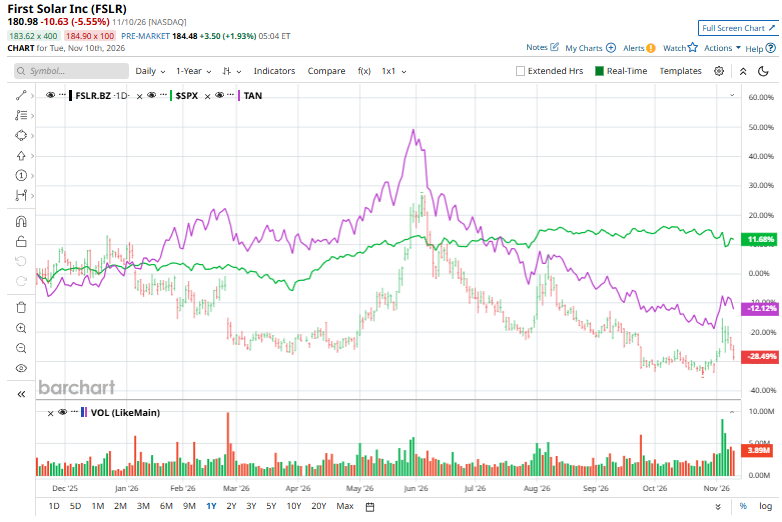
On Nov. 10, First Solar shares fell 6.5% in afternoon trading as hotter-than-expected October 2026 inflation data heightened concerns that the Federal Reserve could keep interest rates elevated for longer. Rising Treasury yields weighed on equities broadly, particularly growth-oriented stocks, as higher borrowing costs and discount rates pressured valuations.
For the current fiscal year, ending in December, analysts expect FSLR’s EPS to grow 24.3% to $17.66 on a diluted basis. The company’s earnings surprise history is mixed. It beat the consensus estimate in two of the last four quarters while missing the forecast on another occasion.
Among the 35 analysts covering FSLR stock, the consensus is a “Moderate Buy.” That’s based on 22 “Strong Buy” ratings, three “Moderate Buys,” eight “Holds,” and two “Strong Sells.”
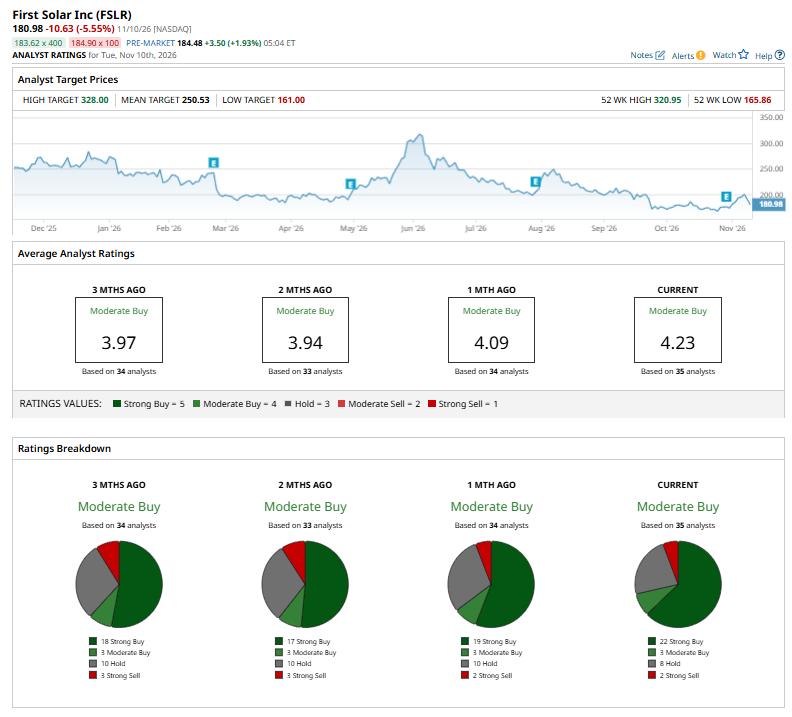
This configuration is more bullish than a month ago, with 19 analysts suggesting a “Strong Buy.”
On Nov. 10, UBS lowered its price target on First Solar to $295 from $330 while maintaining a “Buy” rating. The revision reflects a lower valuation multiple in line with the broader solar industry peer group. The firm also trimmed its 2026 adjusted EPS estimate by 3%, citing weaker-than-expected third-quarter results, lower anticipated module shipments, and higher R&D spending.
The mean price target of $250.53 represents a 38.4% premium to FSLR’s current price levels. The Street-high price target of $328 suggests a notable upside potential of 81.2%.
On the date of publication, Kritika Sarmah did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.