


Zillow Group has seen its stock fall sharply over the past year, and the drop has refocused attention on a simple question for investors who still follow the story. Is the current share price adequately supported by the sales the business is generating today and what it may reasonably add over time?
- The share price has declined 58.9% over the past 12 months, which puts the spotlight squarely on whether the revenue base can justify even this lower level.
- Recent headlines around net losses, a large legal settlement tied to the shuttered Zillow Offers venture, and a housing market that management describes as one of the toughest in a generation can all influence how durable and valuable the company’s sales mix looks.
- There is a second opinion on Zillow Group worth weighing. See what analysts think Zillow Group's shares could be worth.
For investors, the debate is whether Zillow Group's current market value still lines up with what its sales suggest the business is worth.
If you want to test the same question you are asking about Zillow Group against a broader set of opportunities, scan through the 35 high quality undervalued stocks
Is Zillow Group Still Cheap on Sales?
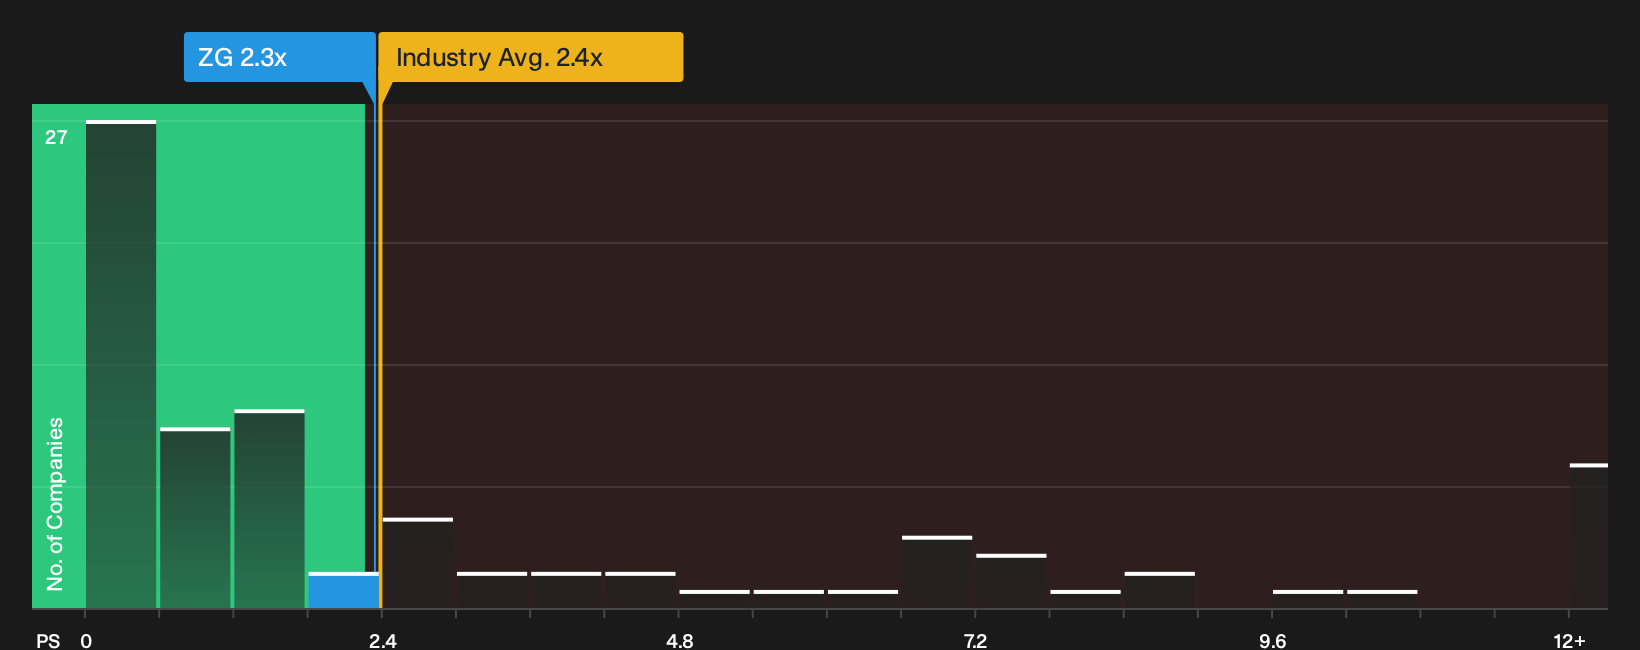
P/S is often a useful yardstick for Zillow Group because the business is still leaning heavily on revenue scale and mix rather than consistent profits. On this measure, the stock trades on a P/S of 2.3x, which is slightly below the Real Estate sector average of 2.4x and above the peer group level around 1.2x. That leaves Zillow Group priced richer than similar stocks on sales, but not dramatically out of line with the broader industry.
The Fair Ratio model, which blends the company’s own growth outlook, margins, size and risk profile, suggests the current 2.3x is below where Zillow Group might typically trade on its revenue base, so the shares screen as undervalued on this framework. Because the recent $212.5m settlement and net losses have weighed on sentiment, this discount on P/S implies investors are still treating the latest setbacks as more important than the long term revenue potential tied to the platform. Explore the numbers behind Zillow Group's P/S valuation.
The Zillow Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this P/S discussion on Zillow Group leaves off by spelling out which combinations of future growth, margins and earnings would need to play out for the stock to look meaningfully higher or lower than today's valuation. Rather than focusing on a single multiple or model output, each narrative sets out the assumptions that underpin its own view of fair value so you can track those inputs against actual results as they are reported, and they sit on Simply Wall St's Community page.
One of the top narratives on Zillow Group: 35% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The shift toward integrated, end-to-end digital transaction ecosystems is enabling Zillow to capture more ancillary services revenue, reducing dependence on advertising and expanding top-line growth…"
Discover why this Narrative puts Zillow Group at 35% undervalued.
One more piece of the Zillow Group puzzle worth checking
Before you stop at the revenue and multiples, it is worth asking who is steering Zillow Group and how their pay packets line up with the outcomes you care about as a shareholder. See who runs Zillow Group and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com