


Stoke Therapeutics has delivered a very large share price gain over the past three years, which puts fresh attention on whether the current US$27.21 level still lines up with the strength of its balance sheet. With the stock now well above where many long-term holders first bought in, the question is how that market value stacks up against what the company’s book value can reasonably support.
- Over the past three years, Stoke Therapeutics has produced a very large total return, which raises the stakes on whether the current valuation is adequately backed by its net assets.
- The business model relies heavily on R&D investment and future cash generation, which can influence how much weight investors put on its existing equity base versus expectations for future value creation.
- The analysts covering Stoke Therapeutics have run their own numbers. See what analysts think Stoke Therapeutics's shares could be worth.
For investors, the debate is whether Stoke Therapeutics' recent share price level is justified by the company’s book value when set against the broader industry average.
If this question about Stoke Therapeutics and its book value has you rethinking how you compare price to balance sheet strength, it can help to widen the lens using solid balance sheet and fundamentals stocks screener (24 results).
Does Stoke Therapeutics Look Pricey on Book Value?
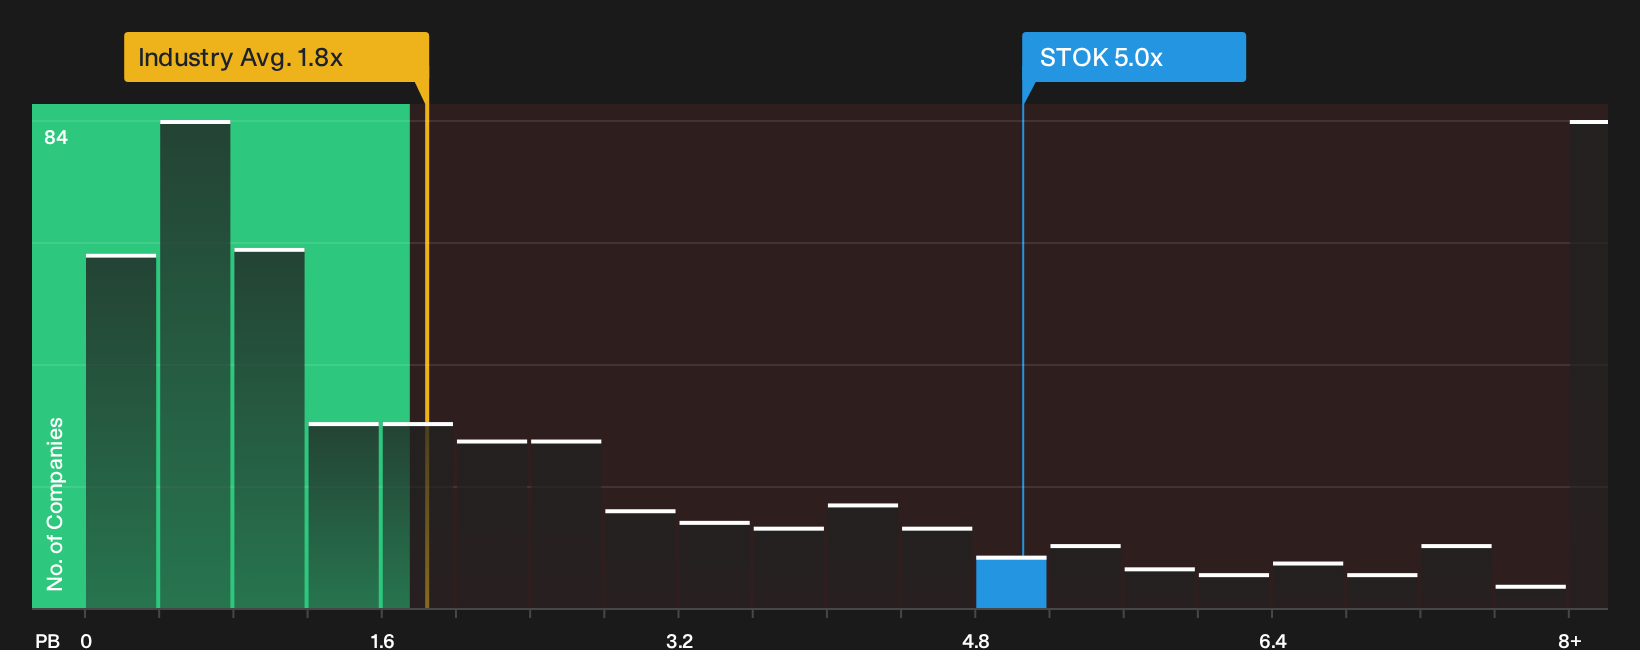
P/B suits Stoke Therapeutics because the business is still loss making, so the share price is easier to compare with the value of its equity on the balance sheet than with earnings. On that yardstick, the stock trades on a P/B of about 5.0x, which is well above the Biotechs industry average of roughly 1.8x.
Set against peers that cluster nearer 2.4x book, Stoke Therapeutics carries a sizeable premium that points to the market paying up relative to the sector’s asset backing. For you as a shareholder, that means more of the US$27.21 price is tied to expectations about future research outcomes and eventual cash generation rather than the current book value. This gap to both the industry and peer benchmarks signals the shares screen as overvalued on this single measure. It therefore becomes important to test whether the pipeline, risk profile and funding position really justify that kind of mark up before leaning on this ratio. Explore the numbers behind Stoke Therapeutics's P/B valuation.
The Stoke Therapeutics Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Stoke Therapeutics valuation puzzle leaves off by spelling out which paths for growth, profitability and earnings would need to play out for the stock to sit meaningfully above or below today's price on the Community page. Each scenario links its implied number to a clear stance on how Stoke Therapeutics' growth, future margins and key risks might evolve, which you can track against fresh results or clinical updates over time.
One of the top narratives on Stoke Therapeutics: 55% undervalued
This Narrative is the bullish analyst Narrative on Simply Wall St, built on the most optimistic analyst price target and forecasts, not one person's view.
"Bullish analysts expect Stoke Therapeutics to turn zorevunersen’s multi year seizure reduction and Vineland-3 gains, plus a lean rare disease commercial model, into a durable Dravet syndrome franchise..."
Discover why this Narrative puts Stoke Therapeutics at 55% undervalued.
Stoke Therapeutics' next question is what the red flags are actually pointing to
Before you anchor on any valuation view for Stoke Therapeutics, it helps to know that independent checks have already flagged areas of concern that deserve a closer look. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com