


Pursuit Attractions and Hospitality (PRSU) just posted third quarter earnings, reporting higher revenue and net income than a year ago, and reaffirmed its full year 2026 revenue guidance of about US$485 million.
The share price of Pursuit Attractions and Hospitality closed at US$55.53. That level reflects a 30 day share price return of 4.89% and a 90 day gain of 19.21%, set against a much stronger year to date rise of 66.21% and a 3 year total shareholder return of 75.17%. This points to momentum building over time despite a recent 1 day pullback of 2.99% and a softer 7 day move.
Scan how Pursuit Attractions and Hospitality stacks up against other consumer names with strong recent share price momentum by reviewing the hand picked 20 high quality undiscovered gems.
Pursuit Attractions and Hospitality has surged this year, yet the share price has cooled over the past week. Does that recent pause offer a reasonable entry? Or is patience the better move before reassessing valuation?
Most Popular Narrative: 11% Undervalued
Against the last close at $55.53, the analyst consensus Narrative on Simply Wall St points to a fair value of about $62.29 when discounting future earnings at 8.93%. That implies Pursuit Attractions and Hospitality screens as modestly undervalued on those assumptions.
Continued expansion into iconic, high-demand travel destinations such as Costa Rica, together with new and upgraded experiences like the Jasper SkyTram rebuild and Banff Gondola enhancements within a more than US$300 million project pipeline through 2030, is expected to add new capacity and price points that can support higher revenue and adjusted EBITDA.
See why 0 investors see Pursuit Attractions and Hospitality as 11% undervalued.
Result: Fair Value of $62.29 (UNDERVALUED)
Still, the Pursuit Attractions and Hospitality story can be knocked off course if climate related disruptions hit key destinations, or if high capital projects face delays and cost pressure.
Find out about the key risks to this Pursuit Attractions and Hospitality narrative.
Another View: Pricing Power Cuts Both Ways For Pursuit Attractions and Hospitality
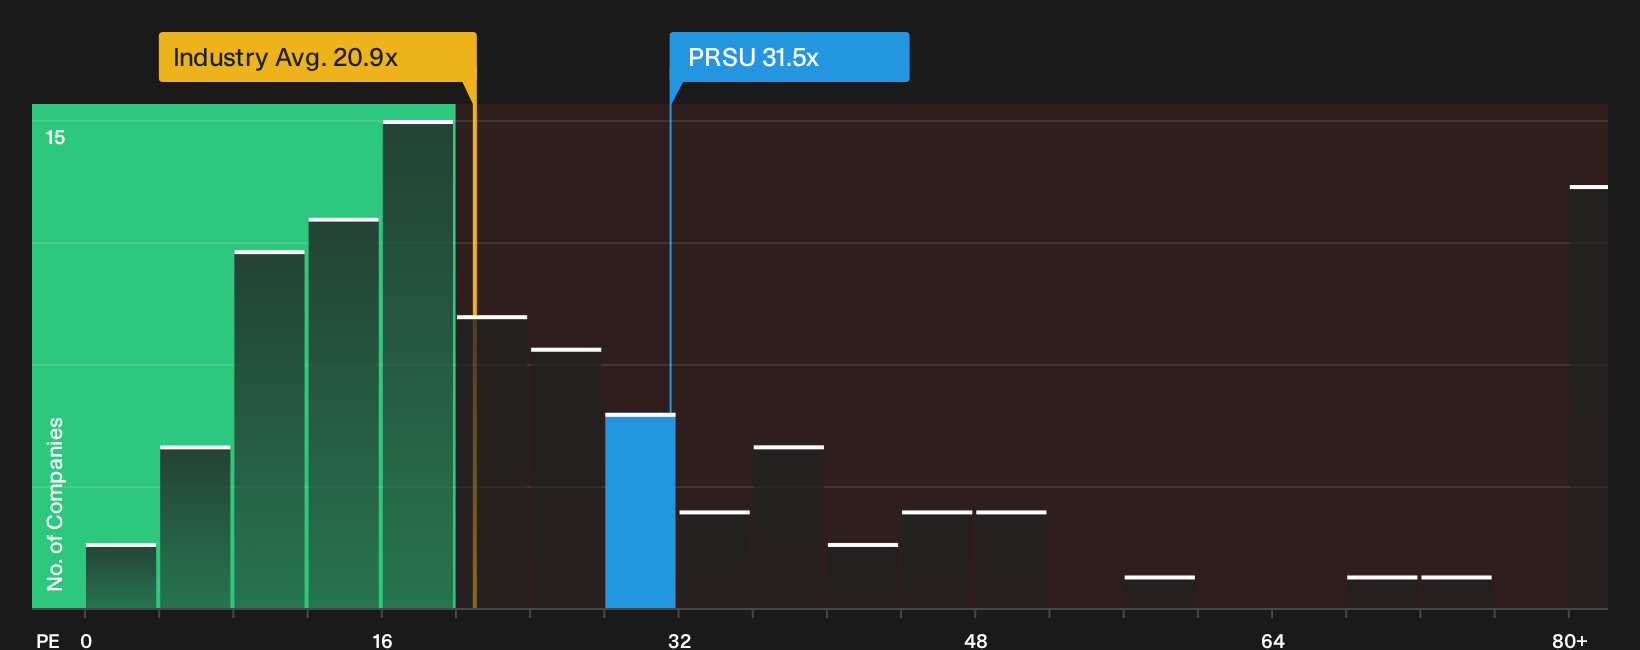
The fair value narrative leans on discounted future earnings, yet the current market tag on Pursuit Attractions and Hospitality tells a different story. At a P/E of 31.5x, the stock trades well above the US Hospitality sector at 20.4x and the estimated fair ratio of 16.5x. That gap leaves less room for error if earnings or travel demand soften. Are you comfortable paying a premium valuation for a business that analysts expect to grow revenue and profit more slowly than the wider US market?
To see how this premium earnings multiple stacks up against both peers and the fair ratio, and what that might mean for valuation risk, have a look at the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed signals around Pursuit Attractions and Hospitality leave you on the fence, move quickly to check the data and pressure test your own thesis. To see what optimists are focusing on in the current setup, take a closer look at the 2 key rewards.
Looking for more investment ideas beyond Pursuit Attractions and Hospitality?
Do not stop your research with Pursuit Attractions and Hospitality. Broaden your watchlist with focused stock ideas filtered by balance sheet strength, value, and risk profile.
- Target robust financial footing by scanning companies with resilient balance sheets and solid fundamentals using the list of solid balance sheet and fundamentals (24 results).
- Hunt for value opportunities that pair quality fundamentals with attractive pricing by reviewing the 35 high quality undervalued stocks.
- Prioritise resilience in choppy markets and keep potential drawdowns in check by focusing on the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com