


Mohawk Industries (MHK) just paired a fresh open ended US$500 million share repurchase authorization with a broad business review, including possible divestitures of weaker units and ongoing restructuring efforts.
The new review and buyback come after a sharp 28.5% 1 month share price return and a 38.6% share price gain year to date. The 3 year total shareholder return of 74.9% contrasts with a 5 year total shareholder return that is still down 15.4%, suggesting momentum has picked up only more recently as Mohawk Industries focuses harder on profitability and capital returns.
Capitalize on Mohawk Industries' renewed focus on efficiency by comparing it with a curated 35 high quality undervalued stocks that share an emphasis on cash generation and disciplined capital returns.Recent buying could be investors re rating Mohawk Industries on cleaner execution and cash returns, or it could be sentiment overshooting the fundamentals. The valuation work now needs to separate one from the other.
Most Popular Narrative: 1.7% Overvalued
At a last close of $151.73 against an analyst consensus fair value of $149.13, the Simply Wall St analyst consensus Narrative frames Mohawk Industries as only slightly ahead of its modeled worth, with the valuation resting heavily on execution of cost programs and product mix upgrades.
Ongoing cost savings and productivity gains that management expects to exceed US$200 million in 2025, with further benefits of roughly US$50 million to US$60 million in 2026 and about US$60 million in 2027, provide a multi year tailwind for earnings power and cash flow.
See why 8 investors see Mohawk Industries as 2% overvalued.
The narrative uses an 8.91% discount rate and assumes Mohawk Industries can steadily lift margins from 4.6% to 5.5%. It also assumes revenue edges up to $11.9b and earnings to $656.4m by 2029, with a P/E of 14.2x on those earnings bringing the modeled value back to $149.13 today. That leaves the share price only slightly above the fair value line, so your own view on how credible those growth, margin and buyback assumptions are will likely matter more than the current 1.7% gap between price and the Narrative estimate.
Result: Fair Value of $149.13 (OVERVALUED)
Still, the narrative can crack if flooring demand stays weak for longer, or if higher input costs squeeze Mohawk Industries' margins and cash generation more than expected.
Find out about the key risks to this Mohawk Industries narrative.
Another View: Mohawk Industries Through The P/E Lens
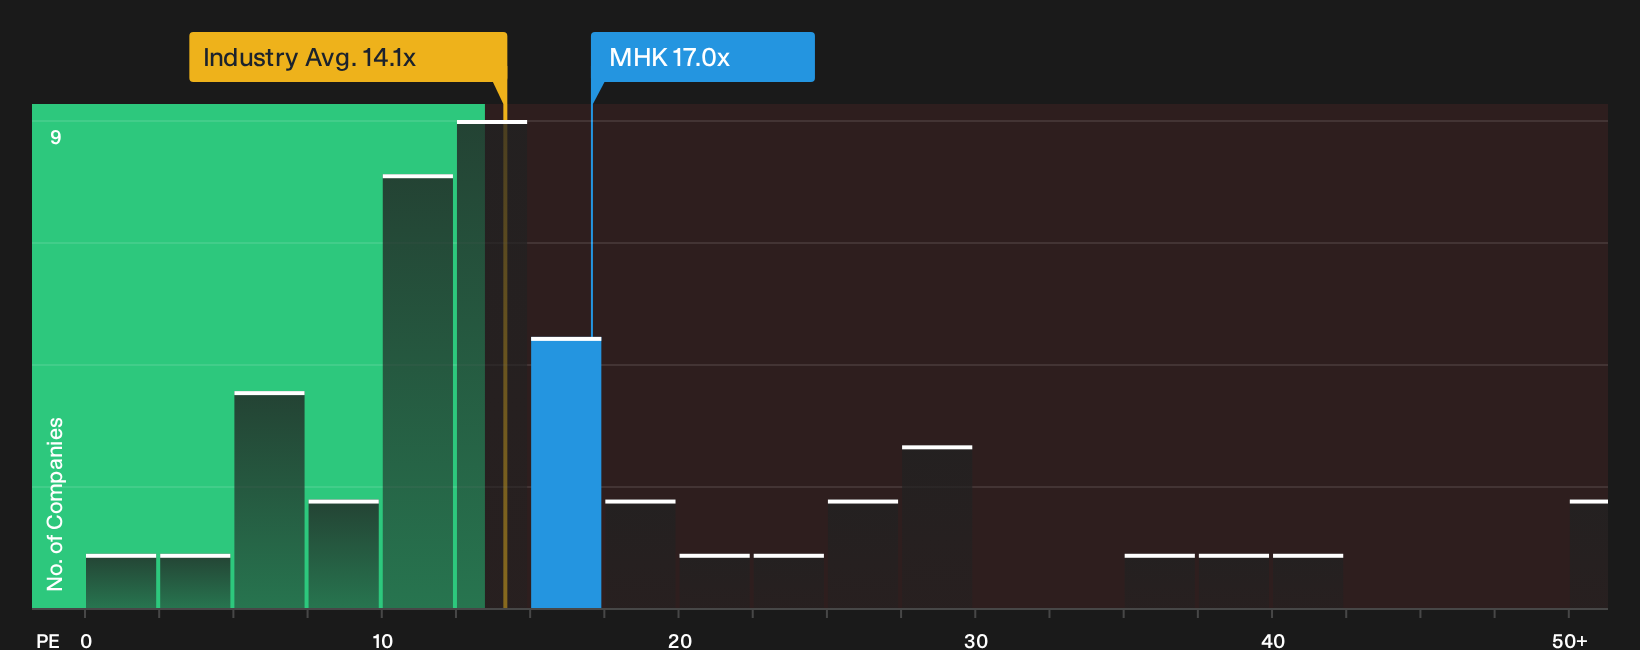
Mohawk Industries screens differently when you step away from the analyst fair value and just look at the P/E. The shares trade on 17x earnings, almost exactly in line with peers on 17x, yet below a fair ratio of 18.2x that our work suggests the market could drift toward over time.
That mix, a sector level premium to the broader US Consumer Durables group at 14.6x but a discount to the 18.2x fair ratio, points to limited valuation cushion if sentiment cools and some potential upside if earnings execution continues to improve. Which side of that equation do you think matters more at $151.73?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Does this setup feel balanced enough to you, or tilted too far toward optimism? Move quickly, review the underlying assumptions yourself, then weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Mohawk Industries?
If Mohawk Industries has sharpened your focus on valuation and quality, do not stop here. Use filter driven shortlists to keep finding better risk reward setups.
- Target resilient balance sheets and steady fundamentals with a list of solid balance sheet and fundamentals (24 results) that surfaces companies built to handle tougher conditions.
- Hunt for potential mispricings by scanning a 35 high quality undervalued stocks where solid cash flows and cleaner finances line up with compressed P/E multiples.
- Seek out future standouts early with a 20 high quality undiscovered gems that focuses on strong fundamentals before the crowd fully pays attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com