


Hormel Foods (HRL) is leaning into holiday seasonality, rolling out a limited time Planters winter collection that relies on exclusive retailer partnerships and a push into e-commerce and digital marketing channels.
Hormel Foods shares trade at US$22.21, with a 1 month share price return of 15.74% following a 90 day share price decline of 8.94% and a 3 year total shareholder return decline of 23.13%. This indicates that short term momentum has picked up while longer term performance remains weak.
Scan beyond Hormel Foods and spot other consumer staples with potential momentum shifts using the hand picked 35 high quality undervalued stocks.
That sharp 1 month rebound in Hormel Foods sits against years of weaker shareholder returns and only modest reported revenue growth. Are investors reassessing the underlying Planters and retail story, or are they just chasing a short term swing as valuation resets next?
Most Popular Narrative: 12% Undervalued
Hormel Foods closed at $22.21 against the analyst consensus Narrative fair value of $25.31, pointing to a discount that the analyst consensus Narrative on Simply Wall St ties directly to execution on margins and portfolio reshaping.
The ongoing simplification of Hormel Foods' portfolio, including exits from whole bird turkey, Brazil operations, a majority stake in Justin’s, private label snack nuts and certain contract manufacturing, is removing roughly US$300m of lower margin and more volatile annual sales. This can support higher blended net margins and more consistent earnings over time.
See why 43 investors see Hormel Foods as 12% undervalued.
Result: Fair Value of $25.31 (UNDERVALUED)
Still, this bullish Hormel Foods narrative can be knocked off course if commodity costs stay elevated or if additional price increases meet stronger consumer pushback.
Find out about the key risks to this Hormel Foods narrative.
Another View: Hormel Foods on Earnings Multiples
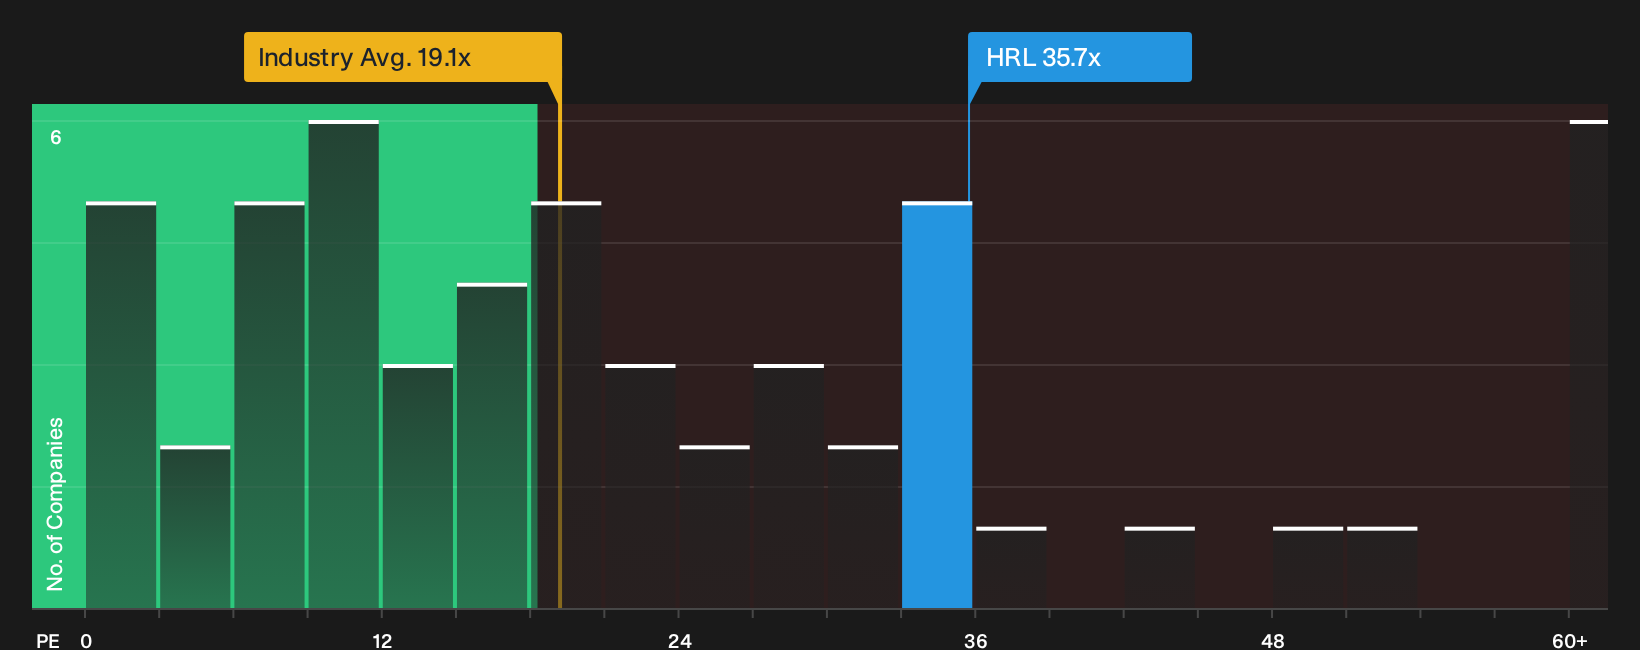
There is a catch to the Hormel Foods undervaluation story. On a simple P/E lens, the stock trades at 35.7x, which is richer than both the US Food industry at 19.1x and the peer average at 30.1x. That points to investors already paying up for future improvement.
The fair ratio estimate lands at 38.4x, only slightly above today’s 35.7x. This suggests limited room for further re rating without stronger execution or faster growth. If sentiment cools or forecasts reset again, it is unclear how much patience the market will show for this premium.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Hormel Foods so far, with a rebound in the share price but questions still hanging over valuation and execution. If you want to move quickly and ground your own view in the underlying data, start by weighing its 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Hormel Foods?
If Hormel Foods has sharpened your focus on valuation and momentum, do not stop there. Broaden your watchlist now so you are not reacting after the best opportunities move.
- Target resilient balance sheets and steadier fundamentals by running the list of solid balance sheet and fundamentals (24 results) before the next bout of volatility reshapes pricing.
- Hunt for underappreciated quality by scanning the 20 high quality undiscovered gems and spotting businesses the broader market might not be watching closely yet.
- Stack potential upside with stability by filtering for reliable payers through the 5 dividend fortresses and compare yields without losing sight of fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com