


Strategic Education (STRA) is back in focus after third quarter results showed a shift from prior profitability to a net loss, driven largely by a US$134.1m impairment on goodwill and intangible assets.
The share price reaction has been sharp, with Strategic Education now at US$54.59 after a 7 day share price return that declined 26.27% and a 30 day share price return that fell 33.74%, while the 1 year total shareholder return is down 29.95%. This suggests that recent earnings, the US$134.1m impairment charge and the latest dividend affirmation have shifted investor focus toward risks rather than potential upside.
Spot opportunities beyond Strategic Education by scanning a curated group of resilient education and service-focused stocks in our 30 resilient stocks with low risk scores.The valuation spread around Strategic Education has widened, with the share price well below both analyst targets and intrinsic estimates. After this sharp reset, what might represent a reasonable fair value range for new money today?
Most Popular Narrative: 44.5% Undervalued
On the analyst consensus Narrative on Simply Wall St, the implied fair value for Strategic Education sits at about $98.33, which is well above the last close at $54.59 and presents the recent drawdown as a sharp disconnect between modelled cash flows and the current quote.
The Education Technology Services segment is described as the fastest growing and most profitable part of the business. Analysts see this segment as an important driver of future adjusted EBITDA and a key pillar behind the 7x 2027 EBITDA valuation multiple.
See why 8 investors see Strategic Education as 44% undervalued.
Result: Fair Value of $98.33 (UNDERVALUED)
Still, the narrative around Strategic Education can break if regulatory changes slow Australia and New Zealand enrollment or if higher Education Technology Services costs continue to pressure margins.
Find out about the key risks to this Strategic Education narrative.
Another View: Valuation Multiples Look Stretched For Strategic Education
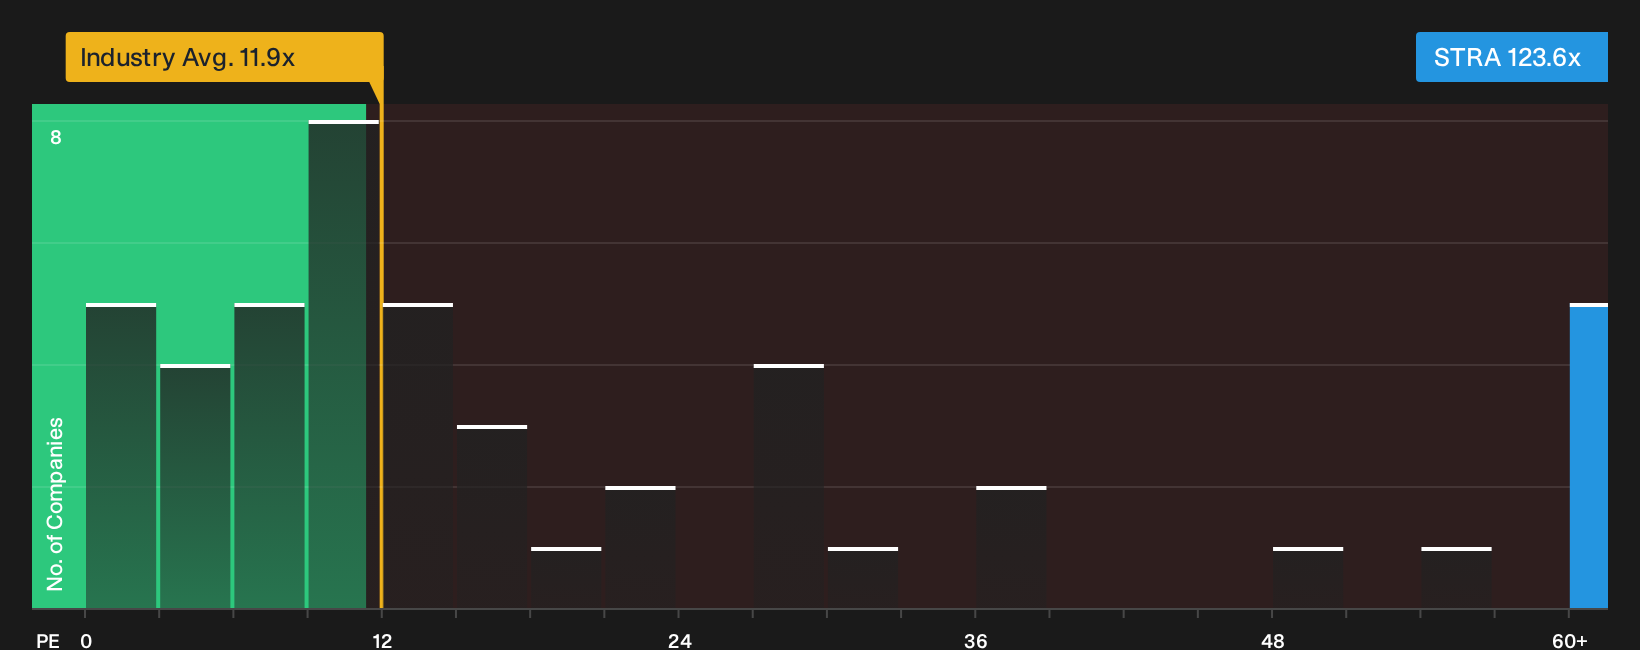
The 44.5% discount to fair value on Strategic Education from the narrative model presents a different picture when you look at simple earnings multiples. The stock trades on a P/E of 123.6x, compared with a fair ratio of 93.6x and a peer average of 20.7x for the US Consumer Services group.
This gap suggests valuation risk. If sentiment cools further and the market moves closer to the sector or even the fair ratio, the share price could face more pressure before any long term growth thesis has time to play out. Which version of value appears more compelling right now: the cash flow model or the multiple on today’s earnings?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Strategic Education is clearly mixed, with sharp valuation resets on one side and a still-supportive narrative on the other. You may wish to review both the potential weak spots and the brighter points before you decide where you stand, starting with the 2 key rewards and 3 important warning signs.
Ready for more investment ideas beyond Strategic Education?
If you only stop at Strategic Education, you risk missing other opportunities that could fit your portfolio even better across value, income and balance sheet strength.
- Target potential mispricing by scanning a curated 35 high quality undervalued stocks that focus on strong fundamentals and attractive entry points.
- Build a steadier income stream by reviewing a handpicked group of 5 dividend fortresses that aim to combine yield with resilience.
- Strengthen your core holdings by filtering for companies on the list of solid balance sheet and fundamentals (24 results) and avoid weaker financial profiles dragging on returns.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com