


- Sectra reported that Mount Sinai Health System agreed to adopt Sectra Reporting on Sectra One Cloud for all radiology services under a seven year contract covering more than 1.2 million exams annually, alongside a separate go live for Meritus Health on Sectra One Cloud for radiology.
- The combination of new cloud deployments and high level German C5 Type 2 and CSA STAR Level 2 certifications for Sectra One Cloud highlights how Sectra is building scale in recurring imaging workflows while addressing security sensitive healthcare workloads.
- We will now look at how Sectra’s strengthened cloud security credentials could influence the existing investment narrative around recurring revenue.
Sectra Investment Narrative Recap
To own Sectra, you need to believe the shift to Sectra One and Sectra One Cloud keeps pulling hospitals into long contracts that support recurring income, even as fewer upfront licenses are sold. The analyst consensus Narrative on Simply Wall St leans on that model, plus expected earnings growth, as the key pillar. The near term swing factor is whether big cloud rollouts land smoothly enough for margins to track those expectations.
The largest risk is that delivery and infrastructure costs from major deployments rise faster than usage based billing, which could leave earnings below what the current P/E near 100x implies. The Mount Sinai and Meritus cloud projects reinforce the contract backlog, but they do not remove execution, cost control, or Secure Communications project delay risks.
The Mount Sinai Health System agreement looks most relevant here. It layers Sectra Reporting onto an existing enterprise imaging setup for more than 1.2 million exams a year under a seven year deal. That speaks directly to the recurring cloud narrative and reliance on multi year imaging contracts as a source of future cash generation.
This type of contract sits alongside Meritus Health’s five year cloud agreement and the new German C5 Type 2 and CSA STAR Level 2 certifications. Together they indicate where the main catalysts are likely to sit. Large scale imaging IT migrations, longer SaaS terms, and security credentials are all operational levers that can either support or challenge the expectations embedded in the analyst consensus Narrative on Simply Wall St.
Sectra's narrative projects SEK 5.8b revenue and SEK 1.2b earnings by 2029. That path assumes 15.7% yearly revenue growth and an earnings increase of about SEK 581m from SEK 619.1m today.
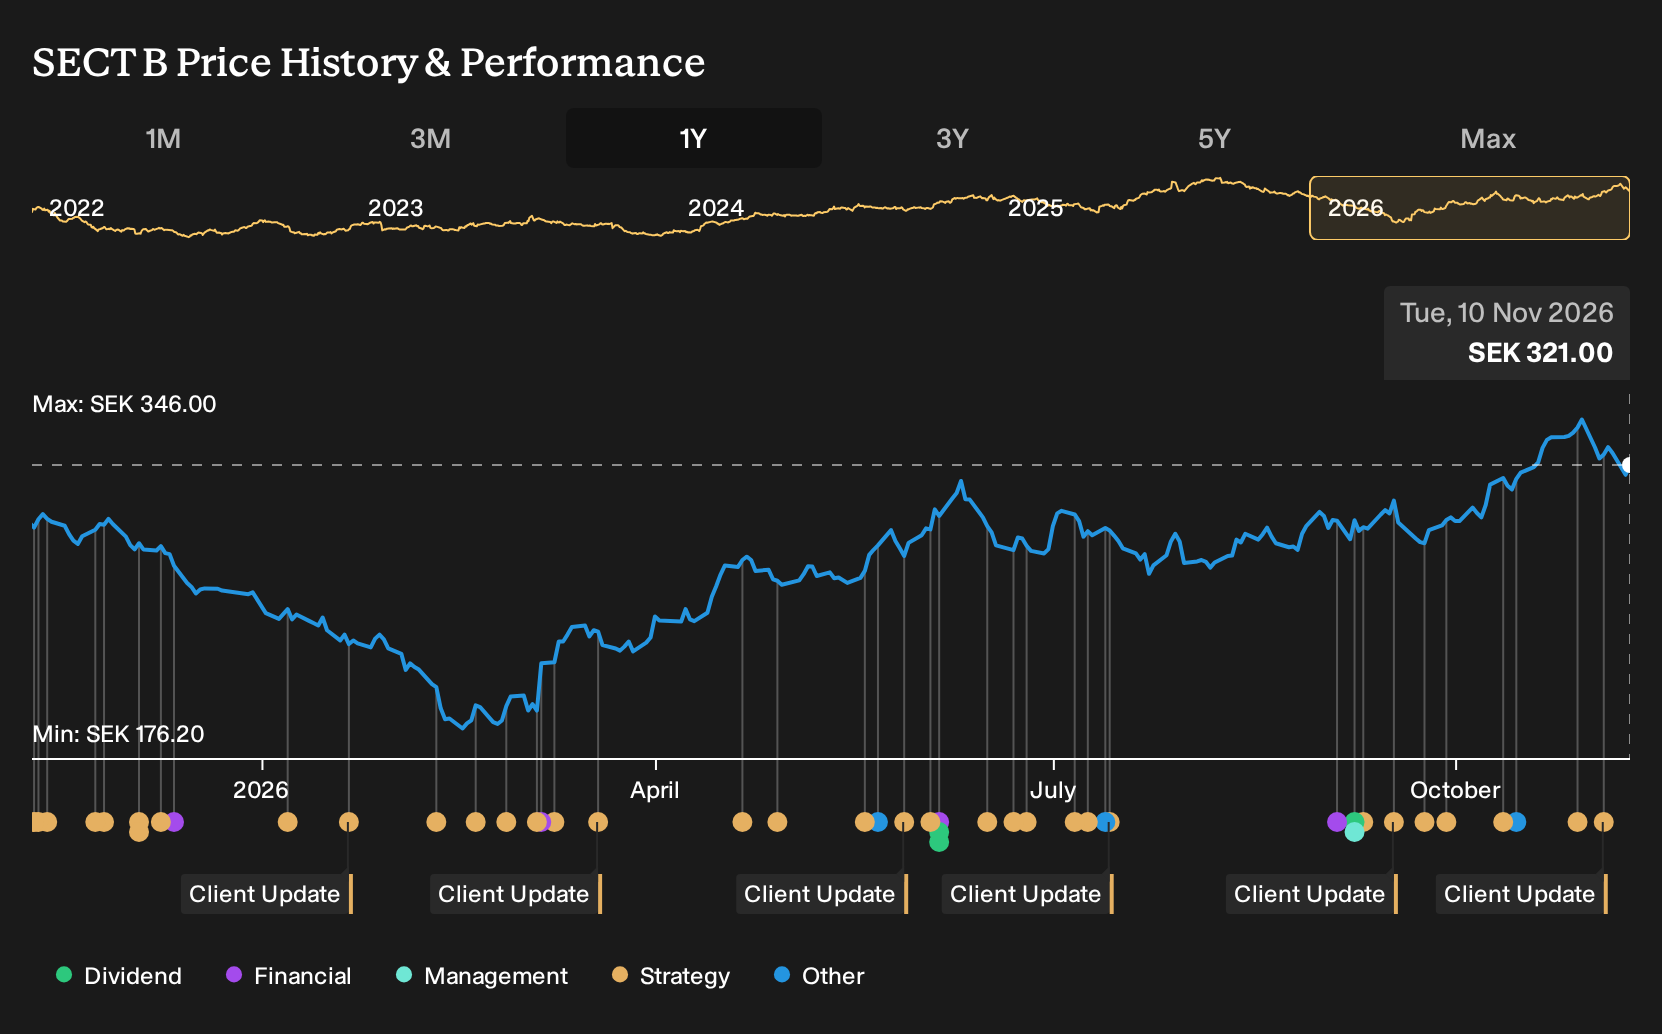
Uncover why Sectra's fair value indicates a 6% potential upside to its current price before the market fully reflects that difference.
Exploring Other Perspectives
One bullish twist on Sectra focuses on AI driven efficiency rather than contract volume. The most optimistic analysts already modeled revenue reaching about SEK 6.1b and earnings around SEK 1.4b by 2029 before this Mount Sinai and Meritus news. You can treat those higher forecasts as one possible path that might shift further as fresh information lands.
Explore 3 other Sectra fair value estimates, including one that suggests up to 6% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Sectra research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Sectra. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sectra's overall financial health at a glance.
Looking for more investment ideas beyond Sectra?
Once you have a view on Sectra, it can help to line it up against other opportunities that match your risk profile, income needs, and quality bar. The Simply Wall St Screener lets you filter for that mix directly, so you are not just reacting to headlines but scanning a wider field with a clear brief.
- If you want a watchlist tilted toward potential mispricing and quality, start with a curated set of 202 high quality undervalued stocks that pair stronger fundamentals with more modest valuations.
- For investors who care most about resilience and steady compounding, build a shortlist from a 207 resilient stocks with low risk scores that screens for sturdier balance sheets and more predictable business profiles.
- If you prefer to hunt for earlier stage opportunities with room to grow into their story, scan a 568 high quality undiscovered gems that surfaces smaller, fundamentally sound companies receiving less attention from the broader market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com