


Why Sonos stock is back in focus
Sonos (SONO) landed back on investor watchlists after reporting fourth quarter and full year 2026 results, pairing higher sales with a much smaller quarterly loss and a return to full year profitability.
The latest earnings beat and buyback activity have put Sonos back on traders’ screens. However, the 1-year total shareholder return is flat, the 3-year total shareholder return is up 50%, and the 5-year total shareholder return is down 51.13%. This points to mixed momentum around the US$16.89 share price and shifting views on both upside potential and risk.
Scan beyond Sonos to see how other consumer hardware stocks with healthier balance sheets and fundamentals stack up in our hand picked list of solid balance sheet and fundamentals (24 results).
Sonos just shifted back to full year profit, paired with a fresh buyback and a share price that barely moved over 12 months. Is this a quality audio business still on sale or already fully charged?
Most Popular Narrative: 9% Undervalued
On the analyst consensus Narrative on Simply Wall St, Sonos screens as modestly undervalued, with a fair value of $18.63 against the latest $16.89 close. This puts the focus firmly on how the installed base can support those numbers.
Leveraging more than 53 million connected devices across over 17 million homes, with management quantifying about US$12b of potential revenue from increasing devices per household and converting single-product homes, positions Sonos to use its system-centric and AI-focused approach to drive higher attach rates that can support revenue and adjusted EBITDA.
See why 19 investors see Sonos as 9% undervalued.
Result: Fair Value of $18.63 (UNDERVALUED)
Still, the narrative can crack if elevated memory costs keep squeezing gross margin, or if larger tech rivals pull buyers away from the Sonos ecosystem.
Find out about the key risks to this Sonos narrative.
Another View: Sonos looks pricey on earnings
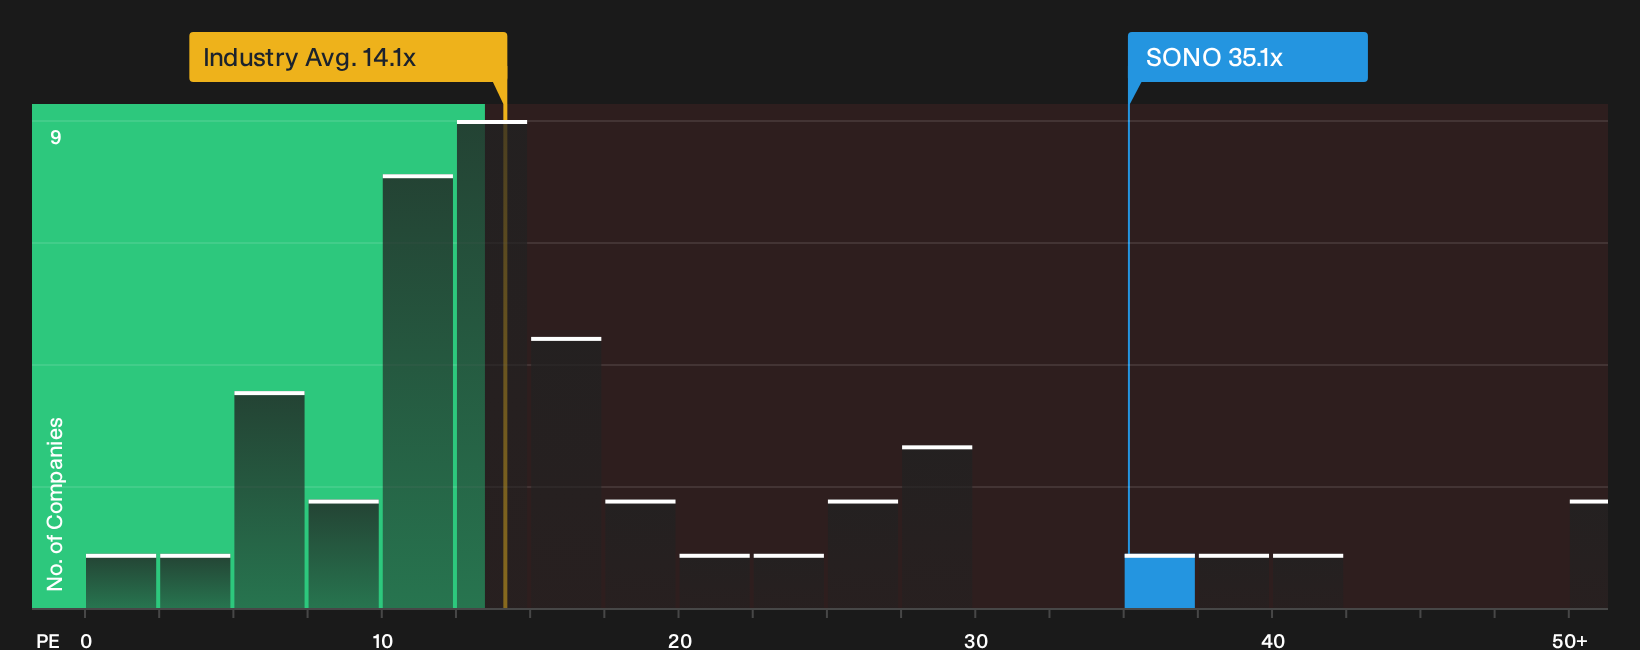
Sonos may screen as 9% undervalued on fair value estimates, but the P/E tells a different story. The stock trades on 35.1x earnings versus 14.6x for the US Consumer Durables group and 19.2x for peers, while the fair ratio sits at 23.3x. That gap points to valuation risk if sentiment cools.
For a closer look at what the numbers imply for today’s price tag, have a read of See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or quiet opportunity, Sonos now has enough data points for you to pressure test the story yourself and decide quickly where you land. To see what investors see as the key potential upsides, start with the 2 key rewards
Looking for more ideas beyond Sonos?
Sonos gives you one angle on audio and consumer hardware, but your portfolio benefits when you scan a wider field of opportunities that fit clear rules.
Use the Simply Wall St screener to uncover fresh stock ideas aligned with your style before others start paying attention.
- Target resilience first by scanning a 30 resilient stocks with low risk scores that filters for companies with lower risk scores and steadier financial profiles.
- Hunt for mispriced quality by running a 35 high quality undervalued stocks that focuses on strong businesses trading below their assessed worth.
- Spot potential future leaders early through a 20 high quality undiscovered gems built to surface high quality companies that many investors may still overlook.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com