


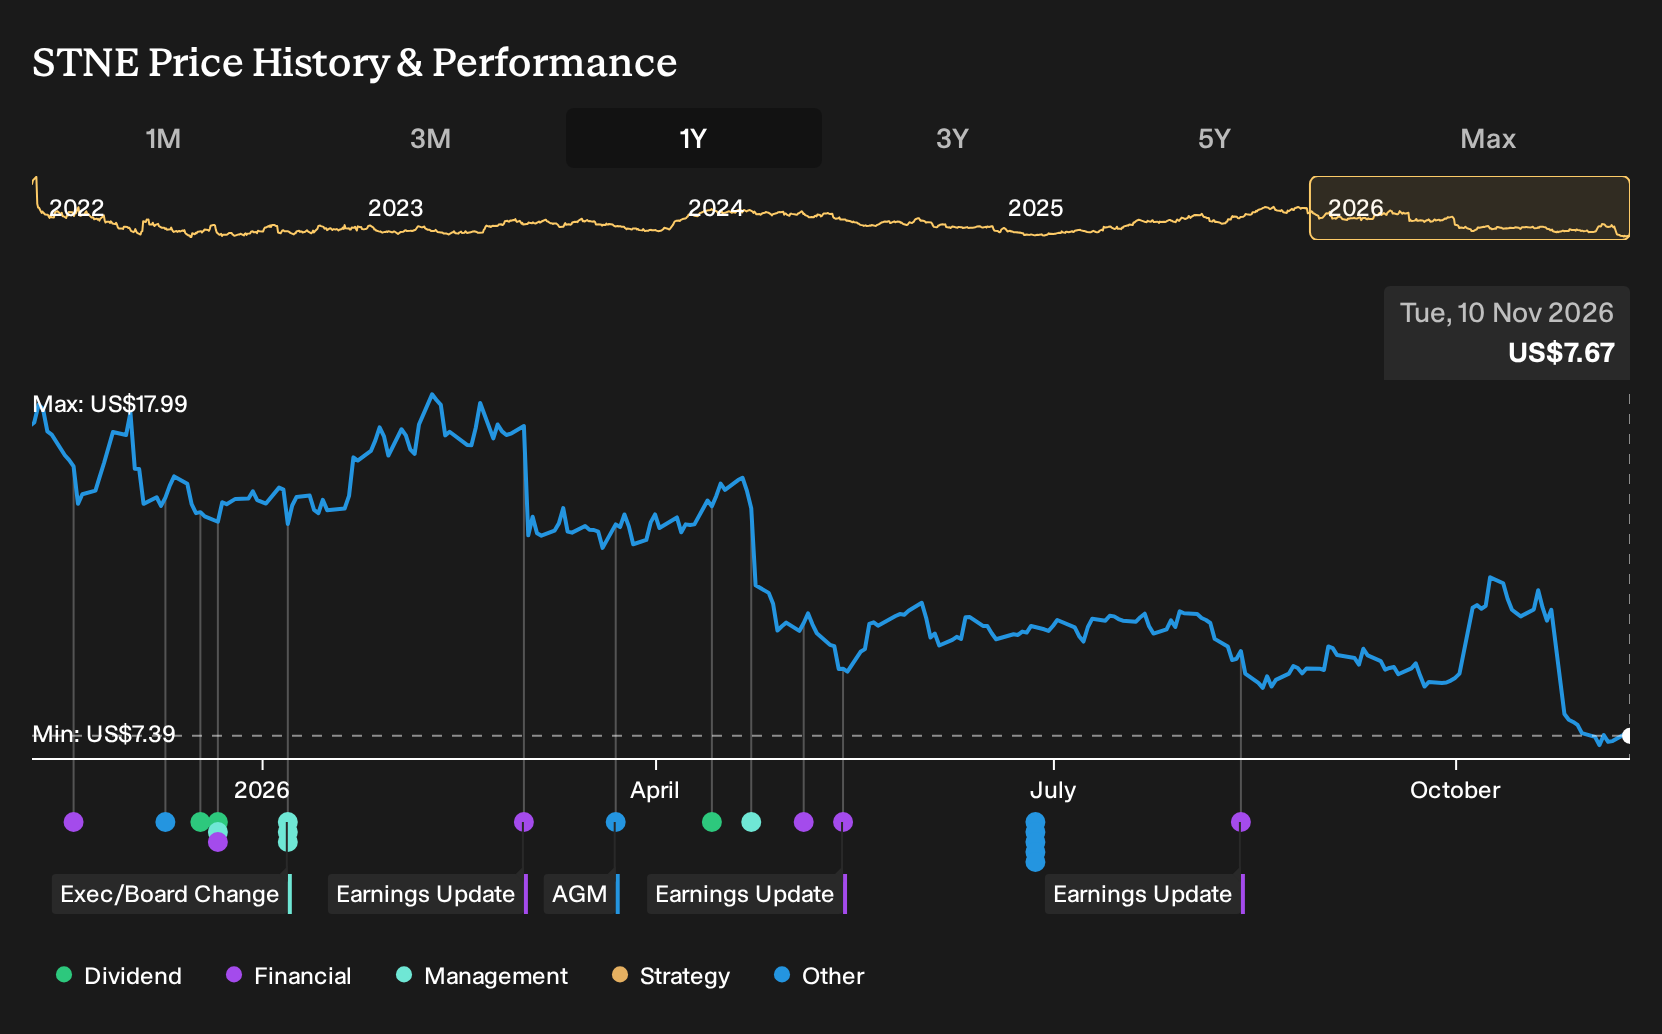
If back in November 2025 you had looked at StoneCo’s two clashing analyst stories, one painting upside from MSMB digitization and banking integration and the other warning on CBDCs and regulation, and decided to sit it out, the following year looked very different for you. Investors who held StoneCo over the past year are down 47.5%, including dividends. The question is which early sign, growth hopes or disruption risks, deserved more scrutiny at the time.
StoneCo has already moved. See which of 35 high quality undervalued stocks still trade below our estimates.
The Two Stories StoneCo Investors Were Really Choosing Between
The shares cost US$17.14 at the start of the period, and the debate around StoneCo was split between two very different but reasonable stories.
On the positive side, the bullish Narrative saw MSMB payments and banking integration as a springboard, with a Fair Value of US$18.8, described as the price implied if its growth plan played out. That view leaned on assumptions of rapid client growth in an underpenetrated market and stronger net margins supported by low cost funding.
The bearish Narrative focused on disruption and rules as the bigger swing factor, with a Fair Value of US$14.2 based on more cautious expectations. Rising CBDC adoption and heavier regulation sat at the center of that case, with the risk that real time systems like PIX and tighter oversight would erode StoneCo’s payment volumes and compress profitability.
What The StoneCo Results Actually Tested
StoneCo’s later filings showed revenue at R$3,337.38m in Q2 2026 compared with R$3,286.24m in Q2 2025, while net income excluding extra items fell from R$583.93m to R$444.59m and net margin declined from 17.8% to 13.3%. That combination nudged the cautious CBDC and regulation story ahead, since the profitability step up in the bullish plan did not materialise in this window.
The hinge assumption here was not headline growth. It was whether higher transaction and credit activity would convert into fatter net margins. For any other fintech, you would want to line up revenue, absolute profit and net margin over several periods to see if operating scale is really turning into better economics.
What StoneCo’s Lower Price Is Asking You To Believe
StoneCo now trades at US$7.67 after a 47.5% loss over the past year, and the bullish analyst Narrative on Simply Wall St still places its Fair Value above that level.
The Narrative leans on StoneCo as a multi product “bank for entrepreneurs” and assumes credit losses stay controlled as secured and government backed lending grows.
"The new positioning of StoneCo as “the bank for entrepreneurs,” with one relationship covering payments, banking and credit, is starting to be backed by marketing spend and a unified app, which could convert existing payments clients that still see Stone mainly as a POS provider into multi product users, potentially lifting ARPAC and supporting revenue and earnings."
One Narrative disagrees with today's price. → See where this Narrative says StoneCo should trade
Looking Beyond StoneCo’s Rails
StoneCo leans on payments, banking and credit in one place. You could also examine the infrastructure that lets merchants move money online.
One large platform built its pitch around being a two sided network. Buyers and sellers meet there so cash, cards and digital wallets can fund transactions.
Instead of owning deposits, this business often rents banking pipes. Partner institutions handle balance sheet risk while the platform focuses on checkout and fraud tools.
The result is a different way to follow similar payment flows. If StoneCo is one bet on merchants, this model offers another angle on digital payments.
That argument has a Narrative and a number behind it. → See the company one Narrative values 40% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com