


Azenta has climbed recently, yet its long term track record is mixed. This puts fresh attention on a simple question for readers who follow the stock closely: Is the current share price at US$40.48 adequately supported by the revenue the business is generating today and is expected to generate in the coming years?
- Over the past 5 years the share price has fallen 66.3%, so anyone looking at Azenta now is effectively reassessing what its current sales are worth after a long reset in expectations.
- Recent investments in gene synthesis, including the SynPlexity acquisition and licensing of technology from Elegen, can influence how quickly Azenta may grow its top line and how much profit it might be able to earn on each dollar of revenue.
- The analysts covering Azenta have run their own numbers. See what analysts think Azenta's shares could be worth.
The issue now is whether Azenta's present market value is well aligned with the sales it is producing and the revenue potential implied by its current business moves.
If you are weighing Azenta on its sales and long term returns, it can help to compare it against a focused set of other stocks screened for 35 high quality undervalued stocks.
Does Azenta Look Fairly Valued on Sales?
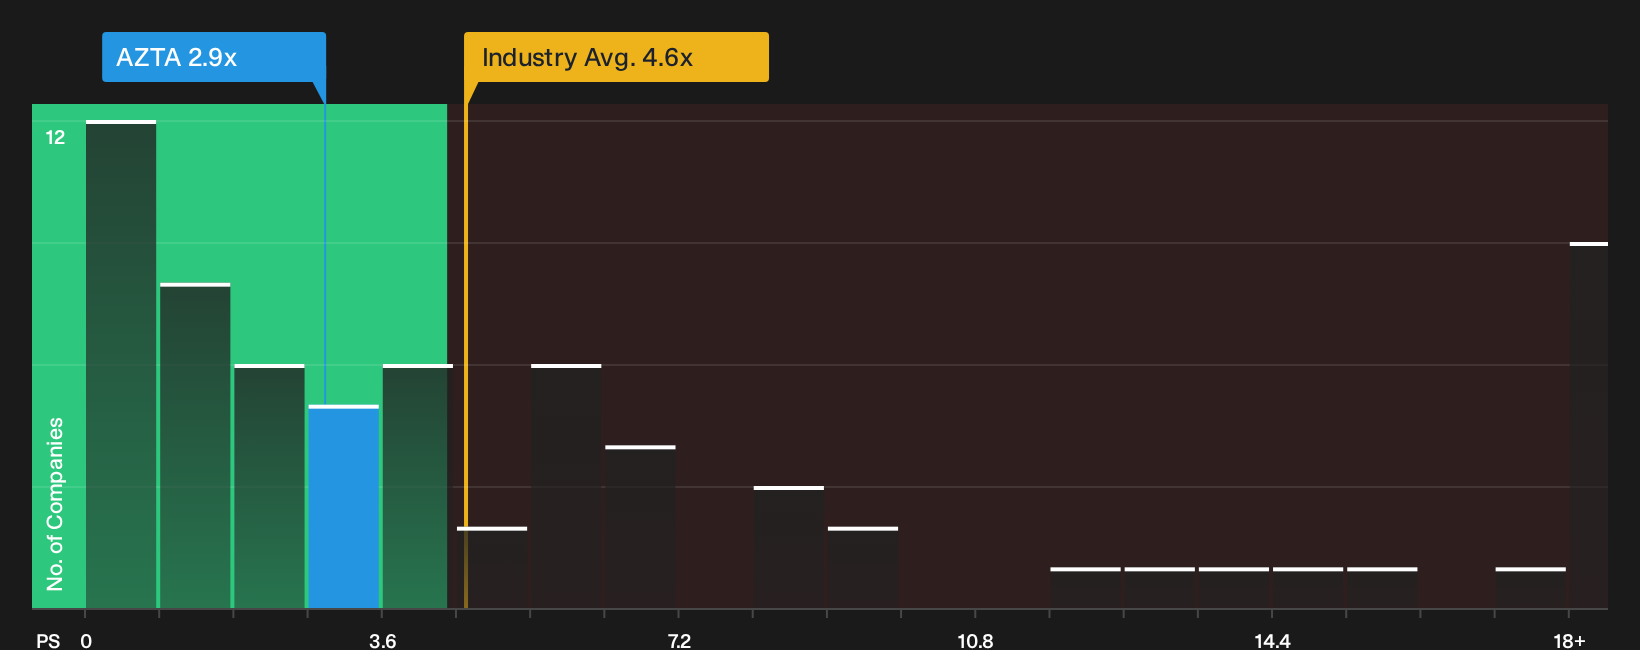
P/S is a useful lens for Azenta because the business is still building profitability and much of the debate centers on what its current revenue stream is worth. On this measure, the stock trades on a P/S of 2.9x, which is below both the Life Sciences sector average of 4.6x and the peer group around 11.7x. That gap tells you investors today are paying fewer dollars for each dollar of Azenta's sales than for many comparable companies.
The fair value framework, which adjusts the P/S multiple for Azenta's growth profile, margins, size and risk, points to a level close to where the shares trade now. In other words, the current 2.9x P/S sits near the range you might expect given those fundamentals rather than flagging the stock as clearly expensive or clearly cheap. Despite the recent push into gene synthesis through SynPlexity and the Elegen license, the market is not assigning a premium multiple to those incremental prospects on revenue. Explore the numbers behind Azenta's P/S valuation.
The Azenta Narrative: What Would Justify Today's Price?
Narratives pick up where Azenta's P/S puzzle leaves off and explain what kind of future in growth, profitability and earnings would need to occur for the stock to be worth materially more or less than it is today. All of this is available on Simply Wall St's Community page.
Each Azenta narrative treats fair value as a thesis about how the business might progress that you can watch over time, rather than a one-off snapshot. This helps you see whether the original assumptions still look reasonable as new information arrives.
Views on Azenta are split between the potential upside from recurring revenue and the weight of governance and execution risk.
Bull case: 8% undervalued
The bullish analyst Narrative on Simply Wall St focuses on how Azenta is reshaping its portfolio and recurring revenue mix.
"The reported shift to more than half of company revenue being recurring from biorepositories and consumables and instruments creates room for Azenta to layer incremental services…"
Discover why this Narrative puts Azenta at 8% undervalued.
Bear case: 7% overvalued
The analyst consensus Narrative on Simply Wall St highlights governance, impairments and Multiomics uncertainty as key constraints.
"Governance and disclosure concerns, including the securities fraud investigations following guidance cuts and the resignation of the CEO that coincided with a single day share price drop of 12%, could lead to higher legal and consulting costs…"
Explore why this Narrative puts Azenta at 7% overvalued.
One more Azenta question that could change the story
Numbers only go so far, because the real leverage at Azenta sits with the people setting priorities, allocating capital and deciding their own rewards, and that alignment question is still unanswered here. See who runs Azenta and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com