


- Packaging Corporation of America disclosed that it received a subpoena as part of a U.S. Department of Justice grand jury investigation into potential price fixing in the containerboard market, alongside other large producers.
- The criminal probe, which runs in parallel with an existing civil lawsuit on alleged price collusion, brings legal, regulatory and reputational pressure that could affect Packaging Corporation of America’s pricing power, cost structure and long term planning for its containerboard operations.
- We will now assess how Packaging Corporation of America’s investment narrative could be affected by the grand jury investigation into alleged price fixing.
Packaging Corporation of America Investment Narrative Recap
To own Packaging Corporation of America, you need to be comfortable with a cyclical packaging business that relies on a tight containerboard market, heavy mill investment and pricing discipline to support earnings. The analyst consensus Narrative on Simply Wall St refers to strong expected profit growth even though revenue is forecast to expand more slowly than the broader US market.
The grand jury probe sits alongside existing pressures. Input costs are elevated, net margins are weaker than a year ago and recent containerboard price hikes need to hold in customer contracts. If the investigation disrupts pricing or customer relationships in the near term, that would add to an already key risk around cost pass through.
The most relevant recent development is the series of containerboard price increases in 2026, including US$70 per ton in March and US$140 per ton from 1 September. These moves were aimed at offsetting higher freight, recycled fiber and energy costs at a time when management described mills as running very tight.
Those same price actions are now under the microscope as the DOJ looks at potential price fixing across containerboard producers, including Packaging Corporation of America. For investors, the question is whether those hikes remain sustainable catalysts for earnings, or whether regulatory and legal risk ends up limiting pricing flexibility and raising compliance costs over the next few years.
Packaging Corporation of America's current analyst storyline assumes revenues reach US$11.4b and earnings climb to US$1.7b by 2029, based on a 5.2% yearly revenue growth rate and an earnings increase of about US$977.3m from US$722.7m today.
Uncover why Packaging Corporation of America's fair value indicates a 4% potential upside to its current price that could narrow quickly.
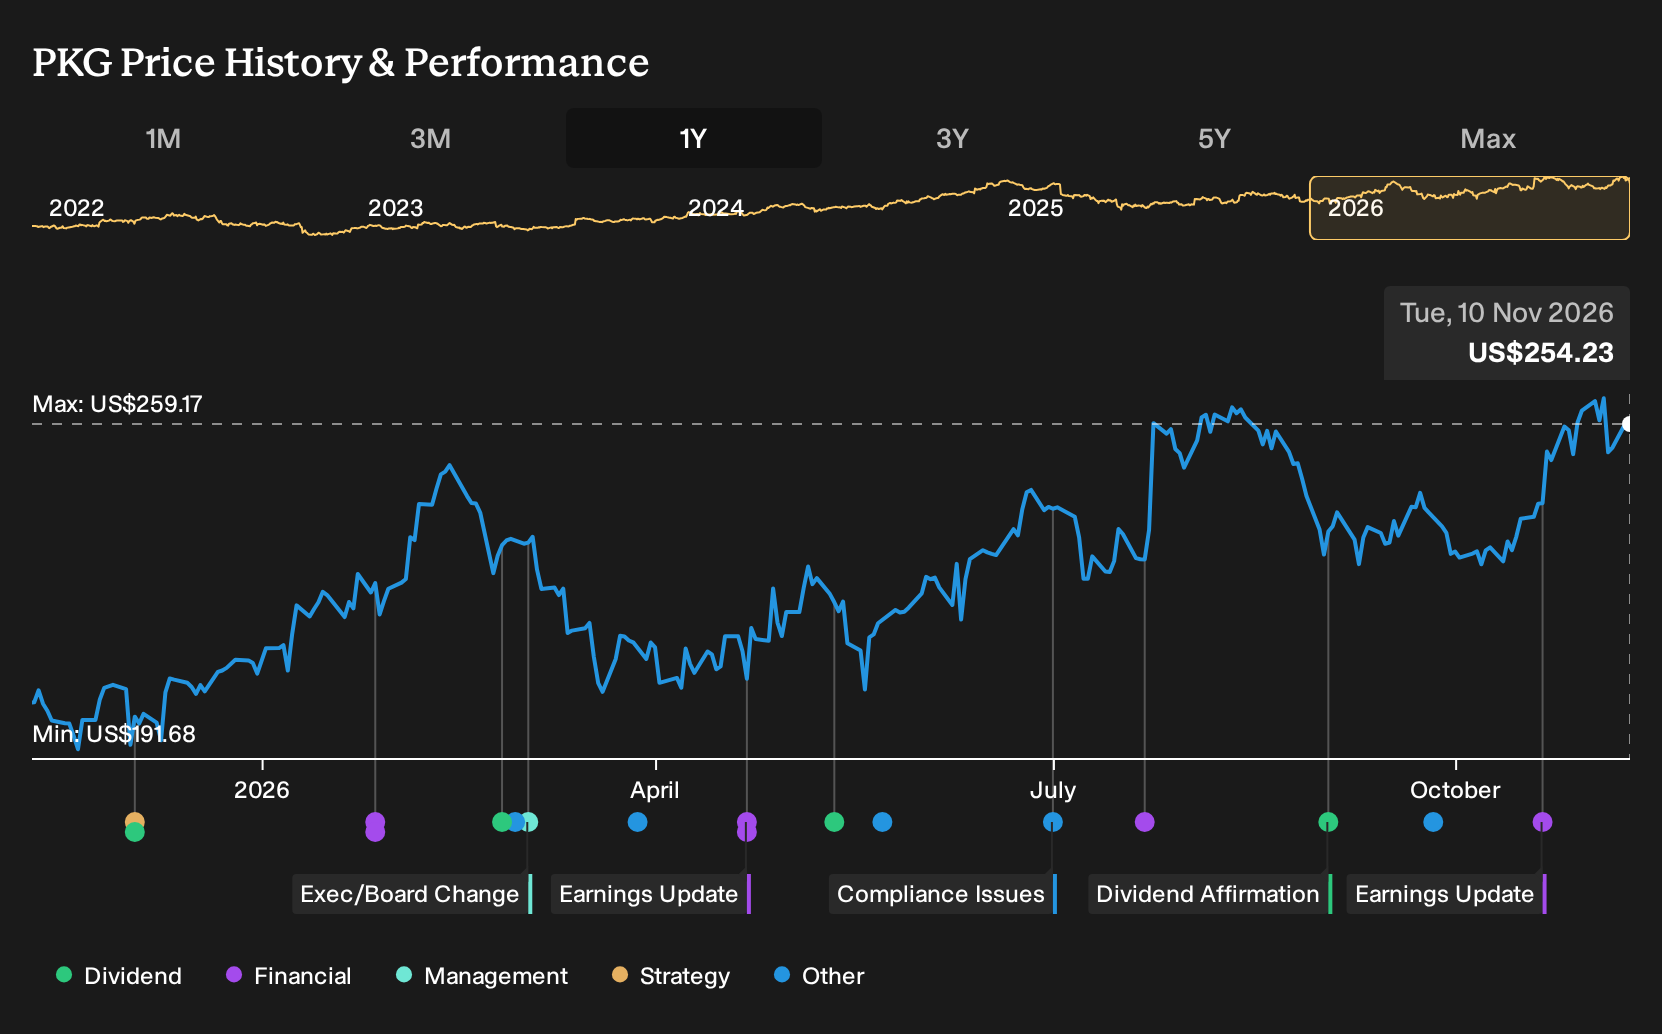
Exploring Other Perspectives
You might focus on tight containerboard supply as the big story, yet the most cautious analysts fixate on margin squeeze instead. Before this DOJ probe, they were only penciling in about US$11.2b of revenue and US$1.4b of earnings by 2029 for Packaging Corporation of America. That more pessimistic path could shift as this investigation unfolds.
Explore 2 other Packaging Corporation of America fair value estimates, including one that suggests as much as 23% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment results rarely come from following the herd, so go with your instincts.
- A great starting point for your Packaging Corporation of America research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Packaging Corporation of America. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Packaging Corporation of America's overall financial health at a glance.
Looking For More Investment Ideas Beyond Packaging Corporation of America?
Once you have a view on Packaging Corporation of America, it can help to compare that thesis with other opportunities that have different risk and return profiles. The Simply Wall St Screener is a quick way to surface stocks that match the type of balance sheet strength, income profile or value tilt you want to focus on next.
- If capital preservation is near the top of your list, start with companies that have sturdier financial footing by checking a curated list of solid balance sheet and fundamentals (24 results) that aims to pair robust balance sheets with sound fundamentals.
- If income is a priority, broaden your watchlist with yield focused ideas sourced from our hand picked 5 dividend fortresses that aims to spotlight higher paying opportunities with an emphasis on durability.
- If you want a fresh hunting ground away from widely followed stocks, scan through a curated pool of 20 high quality undiscovered gems that targets quality businesses which may still fly under the radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com