


- Bank of Communications reported third quarter 2026 net interest income of CNY 48,102 million and net income of CNY 26,388 million, with basic earnings per share from continuing operations of CNY 0.27.
- Across the first nine months of 2026, Bank of Communications showed higher net interest income, while basic earnings per share from continuing operations remained broadly flat compared with the prior period.
- The next step is to consider how Bank of Communications’ investment narrative might shift in light of stronger quarterly net interest income and profitability.
Scan how Bank of Communications stacks up against other large lenders by reviewing our hand-picked list of solid balance sheet and fundamentals (194 results), which may also appeal to income focused investors watching bank earnings momentum.
What Is Bank of Communications' Investment Narrative?
To own Bank of Communications, you need to be comfortable backing a large, capital intensive lender that relies on steady net interest income and disciplined credit risk rather than rapid expansion. The latest quarter fits that picture. Net interest income of CNY 48,102 million and net income of CNY 26,388 million point to an operation still earning money primarily through spread income. EPS of CNY 0.27 for the quarter and CNY 0.79 across nine months suggest profitability is holding, even if per share progress over nine months looks fairly flat.
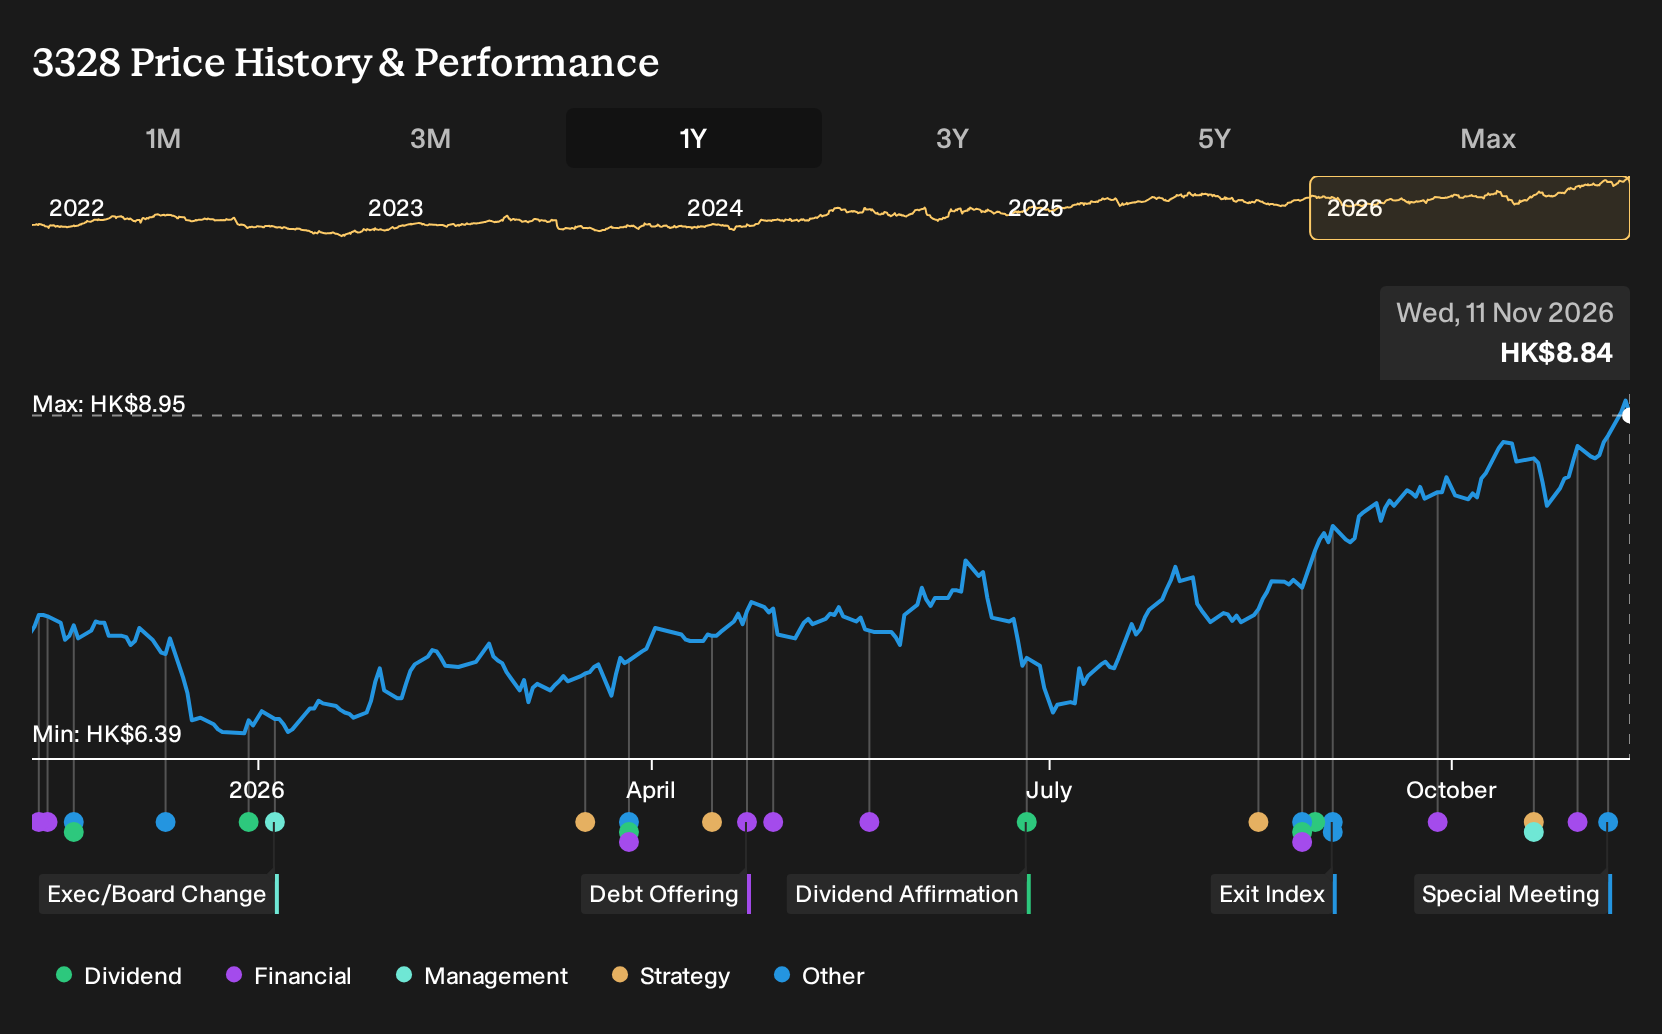
The near term story now hinges on whether management can keep that net interest engine stable while funding growth and meeting regulatory demands. Earnings over the past year have grown faster than the 5 year average and recent share price performance has been strong. However, analysts only see limited upside from here, which hints at expectations already baking in a lot of this progress. Dividend consistency and relatively low return on equity remain watch points, so the third quarter beat on income helps the narrative but does not erase the structural questions around capital efficiency.
That said, there is a less comfortable angle to the Bank of Communications story that sits behind those headline earnings...
There's only one way to know the right time to buy, sell or hold Bank of Communications. Head to Simply Wall St's company report for the latest analysis of Bank of Communications's Fair Value.
Exploring Other Perspectives
Community fair value estimates for Bank of Communications from the Simply Wall St Community span a tight range between 9.07 and 15.94, based on just 2 individual analyses. These views were formed before the recent earnings release, so you are seeing opinions that do not yet reflect the latest net interest and earnings profile. You can use that gap to stress test your own assumptions and compare several alternative viewpoints.
Explore another Bank of Communications fair value estimate, including one that suggests it could be worth just HK$9.07.
The Verdict Is Yours
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Bank of Communications research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bank of Communications. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bank of Communications' overall financial health at a glance.
Looking For More Ideas Beyond Bank of Communications?
If you want to broaden your watchlist beyond Bank of Communications and compare it with other potential opportunities, the Simply Wall St Screener can help you filter the market quickly using clear, fundamentals focused criteria.
- For investors who want growth potential at lower price points, consider smaller, higher risk opportunities screened through 122 elite penny stocks with strong financials that already show more robust financial traits than many peers.
- If value is the priority, scan for companies that pair quality fundamentals with attractive pricing using our focused list of 201 high quality undervalued stocks that might deserve a closer look.
- For those who care most about resilience and capital protection, use the curated set of 208 resilient stocks with low risk scores to find businesses scoring better on balance sheet strength and risk metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com