


- Taiwan Semiconductor Manufacturing (NYSE:TSM) reported booming revenue from AI chip production, signaling strong demand for its advanced foundry services.
- The company described itself as a clear beneficiary of AI infrastructure spending, in contrast to peers such as SoftBank.
- Management highlighted AI related orders as a key driver of recent top line strength during the latest revenue disclosure.
- TSMC's AI fueled revenue surge is important, yet it only captures part of what investors need to weigh on the business. Check out 1 major warning sign that Taiwan Semiconductor Manufacturing investors should know about.
TSMC is far from the only way to get exposure to the build out of AI infrastructure, so it is worth comparing it with 53 AI infrastructure stocks.
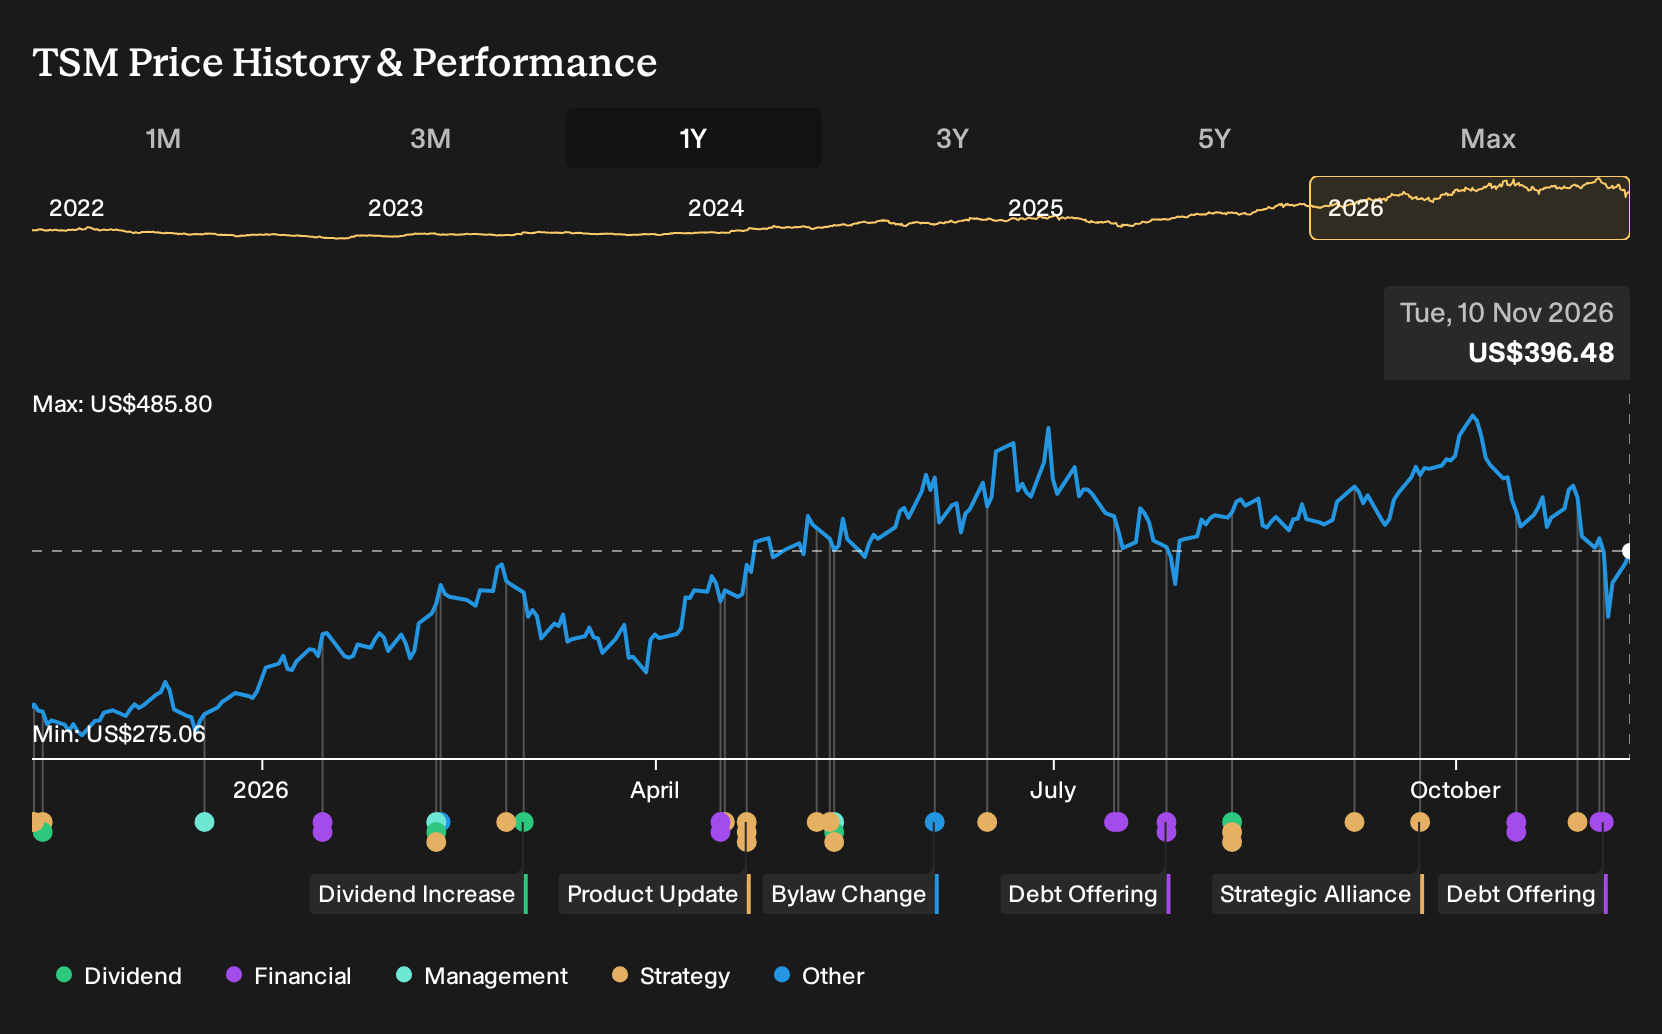
TSMC operates as a contract chip manufacturer that produces, packages, and tests advanced integrated circuits for global customers. This positions the group at the production backbone of AI infrastructure rather than in end user applications. Its US$1.8 trillion market value reflects the scale at which Taiwan Semiconductor Manufacturing already supplies semiconductor devices across the US, Europe, and Asia.
How does this AI revenue surge fit into the Taiwan Semiconductor Manufacturing story so far?
The latest AI heavy revenue mix reinforces Taiwan Semiconductor Manufacturing as an infrastructure supplier rather than a consumer facing chip brand. That lines up with its push to expand fabs in Taiwan, the US, Japan, and Germany, because higher capacity only matters if large AI customers keep filling those lines with advanced orders.
What does this say about market sentiment toward TSMC versus SoftBank and other AI plays?
Investors are clustering around TSMC as an AI hardware beneficiary, while SoftBank’s numbers point to a less direct payoff from AI exposure. The strong foundry revenue gives traders something concrete to lean on, which can matter when sentiment has already been debating whether prior share price gains fully reflected the AI theme.
What is the clearest thing to track next to test whether this AI strength is lasting?
The simplest yardstick is whether management keeps reporting AI related demand as a key driver of quarterly revenue, particularly as new fabs open and utilization rates become more important. Watch upcoming monthly sales disclosures and the next full earnings release to see if AI linked orders still dominate the growth story.
Add Taiwan Semiconductor Manufacturing to your Watchlist and get alerts as these catalysts play out.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com