


Yokogawa Electric (TSE:6841) has put income and earnings firmly in focus after lifting its interim dividend to ¥46 per share and raising full year guidance on sales, profit, and earnings per share.
The raised guidance and richer interim payout arrive in a weaker market environment. Yokogawa Electric’s share price has retreated over the past quarter, with a 90 day share price return of 24.31% in decline, while the 5 year total shareholder return of 100.79% still points to a strong longer run outcome overall, suggesting that recent momentum has faded even as the longer history remains supportive.
Scan beyond Yokogawa Electric to identify other industrial and automation plays that combine income potential with earnings momentum using our curated list of list of solid balance sheet and fundamentals (23 results).
Yokogawa Electric now appears to be a solid industrial franchise whose share price has stepped back sharply. Are investors being offered quality at a reasonable tag, or paying up for comfort after a strong run?
Price-to-Earnings of 20.2x: Is it justified?
Valuation on Yokogawa Electric is not cheap at a headline level, with the stock trading on a P/E of 20.2x at a last close of ¥4,216. This places it at a richer level than both its sector and peer group despite a recent share price pullback.
The P/E metric compares what investors are willing to pay today for each unit of current earnings. For an automation and measurement specialist like Yokogawa Electric, it effectively reflects how the market weighs its earnings track record, its forecast profit expansion, and the perceived resilience of its industrial customer base.
Here, the ratio is meaningfully higher than the JP Electronic industry average of 14.1x and above the peer average of 18.9x. The market is therefore paying a clear premium for the group’s profile. The estimated fair P/E of 19.1x is also lower than the current 20.2x, which points to a valuation level that could, over time, move closer to that fair multiple if sentiment or earnings delivery change.
Explore the SWS fair ratio for Yokogawa Electric.
Result: Price-to-Earnings of 20.2x (OVERVALUED)
Still, the recent share price slide of 18.3% year to date and softer 1 year total return could signal shifting sentiment if earnings delivery disappoints or if industrial demand softens.
Find out about the key risks to this Yokogawa Electric narrative.
Another View: What Our DCF Model Says About Yokogawa Electric
A different lens gives a different story. Our DCF model values Yokogawa Electric at ¥3,764.43 per share, which sits below the current ¥4,216 quote. That points to a stock that screens as overvalued on this cash flow view and raises the question of how much optimism is already in the price.
Look into how the SWS DCF model arrives at its fair value.
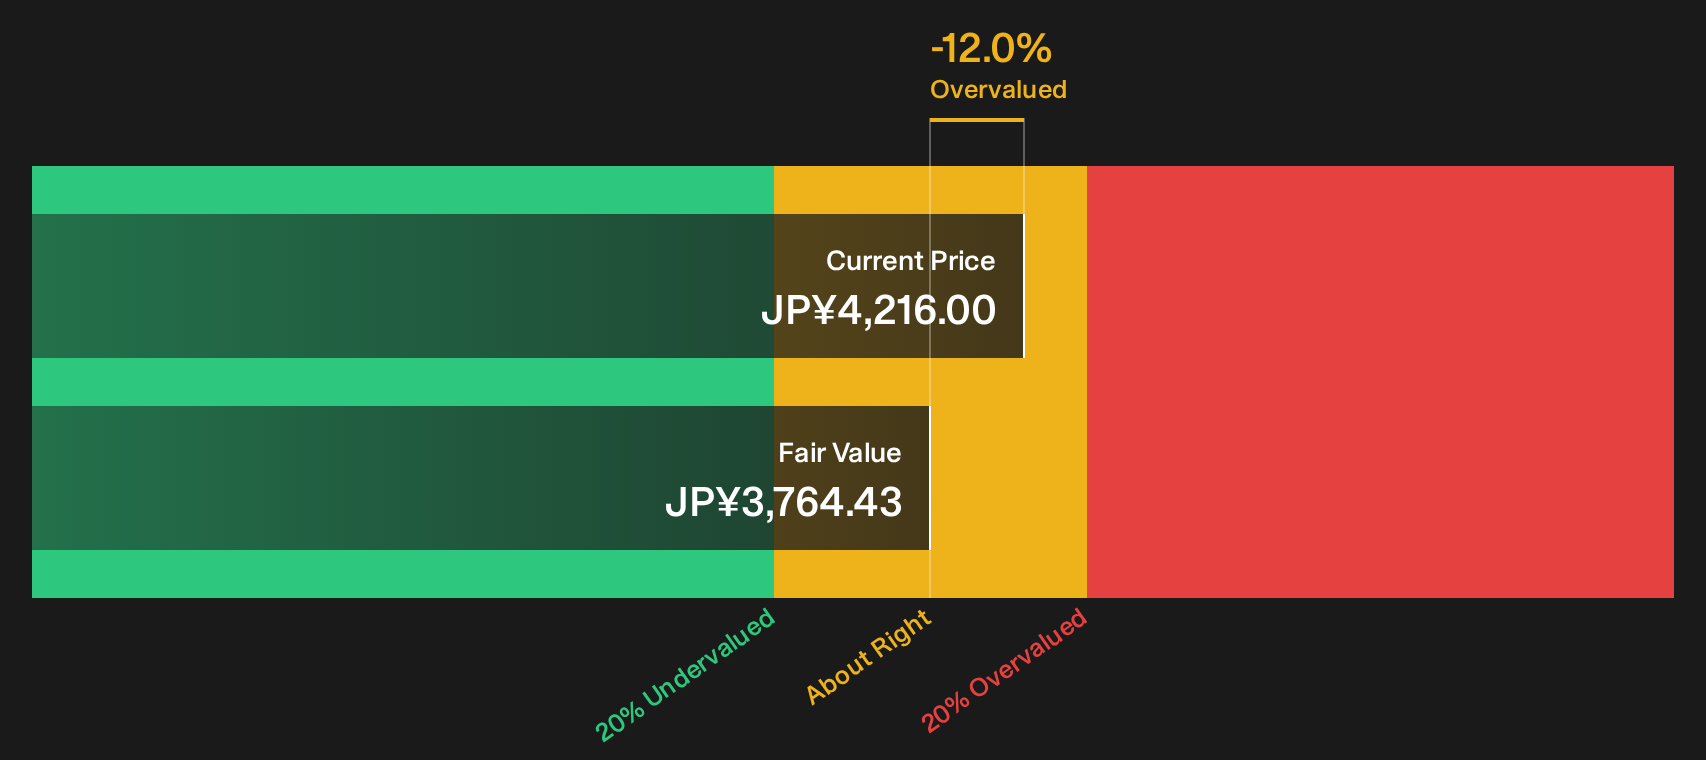
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Yokogawa Electric for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 23 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Yokogawa Electric looks mixed, with richer valuation signals on one side and a softer share price pattern on the other. Act while the details are fresh and review the underlying metrics for yourself, then weigh up the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Yokogawa Electric?
If Yokogawa Electric has sharpened your focus on quality and price, now is the moment to widen your search and pressure test your next move.
- Target resilient potential compounders that combine financial strength with measured risk using our 19 resilient stocks with low risk scores.
- Hunt for quality priced below what the market is paying elsewhere through a curated pool of 23 high quality undervalued stocks.
- Build a payout focused watchlist that leans on robust balance sheets and consistent income profiles by scanning our 29 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com