


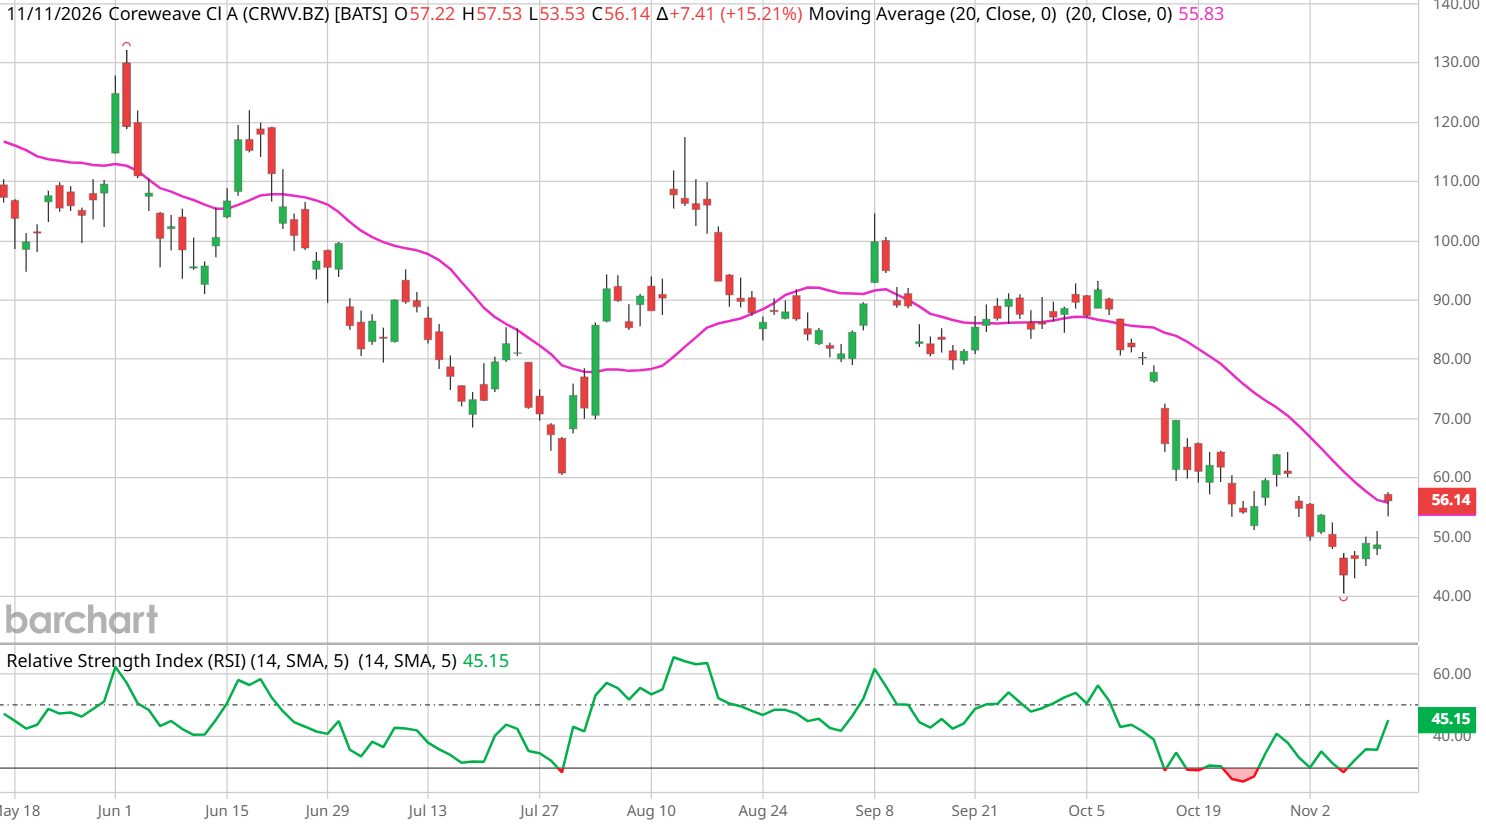
CoreWeave (CRWV) jumped 15% in premarket trading Wednesday after its third-quarter report showed that the AI cloud provider raised prices about 25% in July and another 10% later in the quarter, a striking display of pricing power from a company whose stock had lost about 40% of its value over the past month.
That slide had left shares 64% below their May highs, which made this report the catalyst that a battered neocloud complex badly needed.
Peers rallied in sympathy, with Nebius (NBIS) up 13%, IREN (IREN) up 7%, Cipher Digital (CIFR) rising 9%, Applied Digital (APLD) up nearly 10%, and Core Scientific (CORZ) tacking on 7%.
Pricing Power Is the Underappreciated Story
Rental rates on older Ampere and Hopper chips climbed 30% to 50% sequentially, a notable but underappreciated sign that demand for compute is extending well beyond the newest hardware.
Roughly 300,000 fully paid-off GPUs coming off contract in 2027 and 2028 could add nearly $10 billion in annualized revenue without any new capital spending, compared with the $3.66 billion CoreWeave booked in the entire third quarter.
Put simply, CoreWeave is charging more for the same chips, and its already-paid-off fleet could become a meaningful revenue engine once those contracts roll over.
CRWV Earnings Cleared the Bar
Revenue soared 168% to $3.66 billion, ahead of the roughly $3.54 billion consensus, while adjusted operating margin reached 10% a full quarter ahead of plan.
Backlog grew to $132.5 billion from $104 billion in June, and CoreWeave management raised 2026 revenue guidance to $13 billion to $13.3 billion while lifting adjusted operating income guidance 26% at the midpoint.
The company also targeted adjusted profitability in the first half of 2028, a timeline that puts its financing strategy under a microscope.
Can the Balance Sheet Keep Up?
However, net interest expense of $846 million swamped operating income of just $207 million, producing a $709 million net loss for the quarter.
Fourth-quarter interest is guided above $1 billion, up from the third quarter's $846 million, against roughly $47 billion of debt and capital spending of $37 billion to $39 billion.
With unsecured yields near 16% and credit default swap spreads (the cost of insuring against default) above 11%, management is bypassing the unsecured market entirely.
Instead, CoreWeave will rely on about $9 billion of expected prepayments, contract-backed loans priced near 7% to 7.5%, and limited parent-level capital, a mix that still leaves dilution risk for shareholders.
That 7% to 7.5% contract-backed rate is less than half the roughly 16% unsecured yield, which explains why management is anchoring its financing to customer contracts.
Wall Street Splits on CoreWeave
Analyst reactions underline that tension, as Citigroup raised its CRWV price target to $149 while Jefferies , Stifel and Morningstar trimmed theirs, citing lower multiples and financing exposure.
The macro backdrop offers little cover, with a December Fed rate hike fully priced in according to CME FedWatch, a hawkish setup that argues against treating this rally as an all-clear.
For a company carrying roughly $47 billion of debt and guiding to more than $1 billion in quarterly interest, a tighter rate path is far from an abstract concern.
The Next Catalyst to Watch
Nebius reports results on Thursday, and that print will be the next test of whether Wednesday's move marks a genuine sector bottom or merely a relief bounce.
Traders will be looking for signs that the pricing strength CoreWeave reported extends across the neocloud group. CoreWeave has shown it can raise prices, but the harder trick will be outrunning its interest bill.
For traders looking to target a quick day trade in CRWV after earnings, check out this quick clip to see the levels our expert day trader Kenny Glick will be looking to target around volume-weighted average price (VWAP) in today’s session.
This article was created with the support of automated content tools from our partners at Sigma.AI. Together, our financial data and AI solutions help us to deliver more informed market headline analysis to readers faster than ever.
On the date of publication, Sarah Holzmann did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.