


Video-sharing platform RUM Group (NASDAQGM:RUM) reported Q3 2026 results exceeding the market’s revenue expectations, with revenue up 290% year on year to $96.58 million. Its GAAP loss of $0.19 per share was 58.3% below analysts’ consensus estimates.
For more on RUM Group, read our free full research report.
RUM Group Q3 2026 highlights:
- Revenue $96.58 million vs S&P consensus estimates of $88.67 million (290% year-on-year growth, 8.9% beat)
- EPS (GAAP) -$0.19 vs analysts’ consensus estimates of -$0.12 (58.3% miss)
- Adjusted EBITDA $4.41 million (4.6% margin, 129% year-on-year growth)
- Operating margin -87.6%, up from -98.4% in the same quarter last year
- Free cash flow -$80.04 million compared to -$12.04 million in the same quarter last year
- Market capitalization $2.04 billion
Chris Pavlovski, CEO of RUM Group, commented, “Q3 was a defining quarter for RUM Group. We delivered record revenue, nearly four times last year’s, and achieved positive Adjusted EBITDA for the first time in our history. Quake AI is now the engine of our business. We have real assets running real AI workloads for real customers and generating real cash. Our 22,000-GPU estate is nearly sold out at 85% utilization. As capital becomes more selective, we believe it will flow to experienced operators with disciplined balance sheets. That is exactly where RUM Group stands, and we intend to use that position to build lasting value for our shareholders.”
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can experience short-term success, but top-performing ones sustain growth for years. RUM Group’s revenue grew at a strong 84.9% compounded annual growth rate over the last five years. Its growth beat the average business services company and shows its offerings resonate with customers.
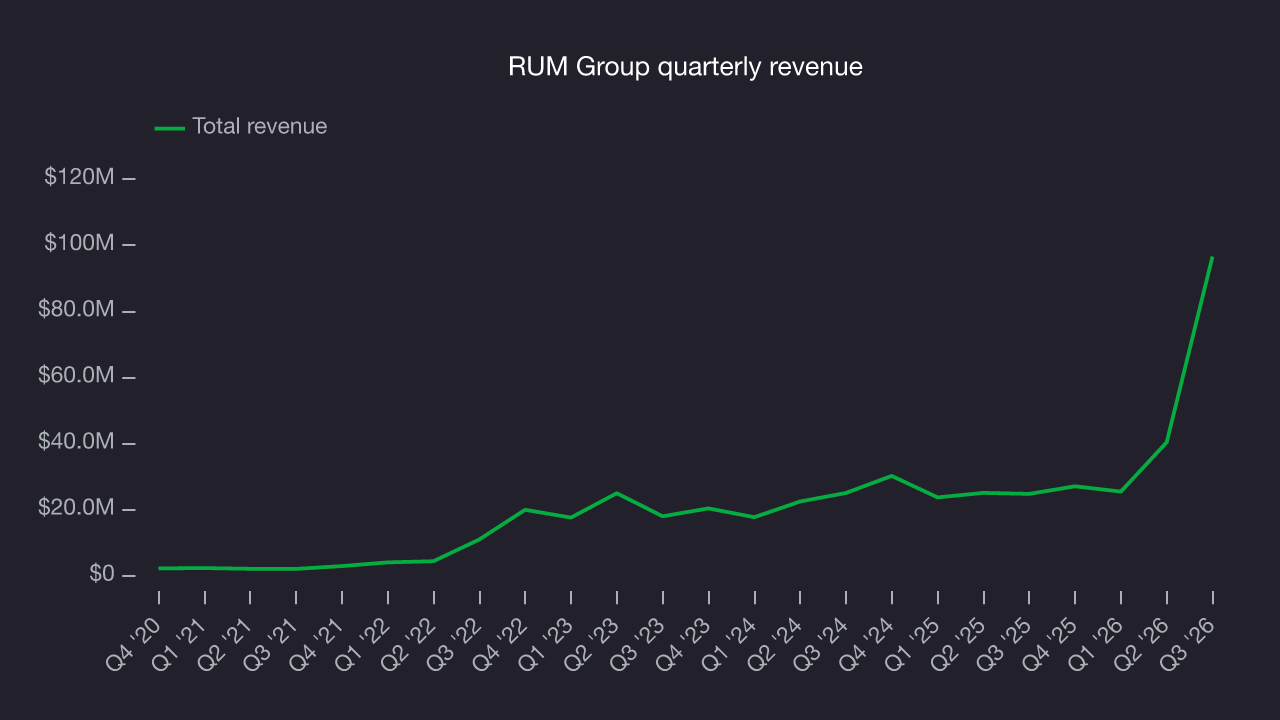
Long-term growth is the most important, but within business services, a half-decade historical view may miss new innovations or demand cycles. RUM Group’s annualized revenue growth of 48.7% over the last two years is below its five-year trend, but the results still suggest healthy demand.
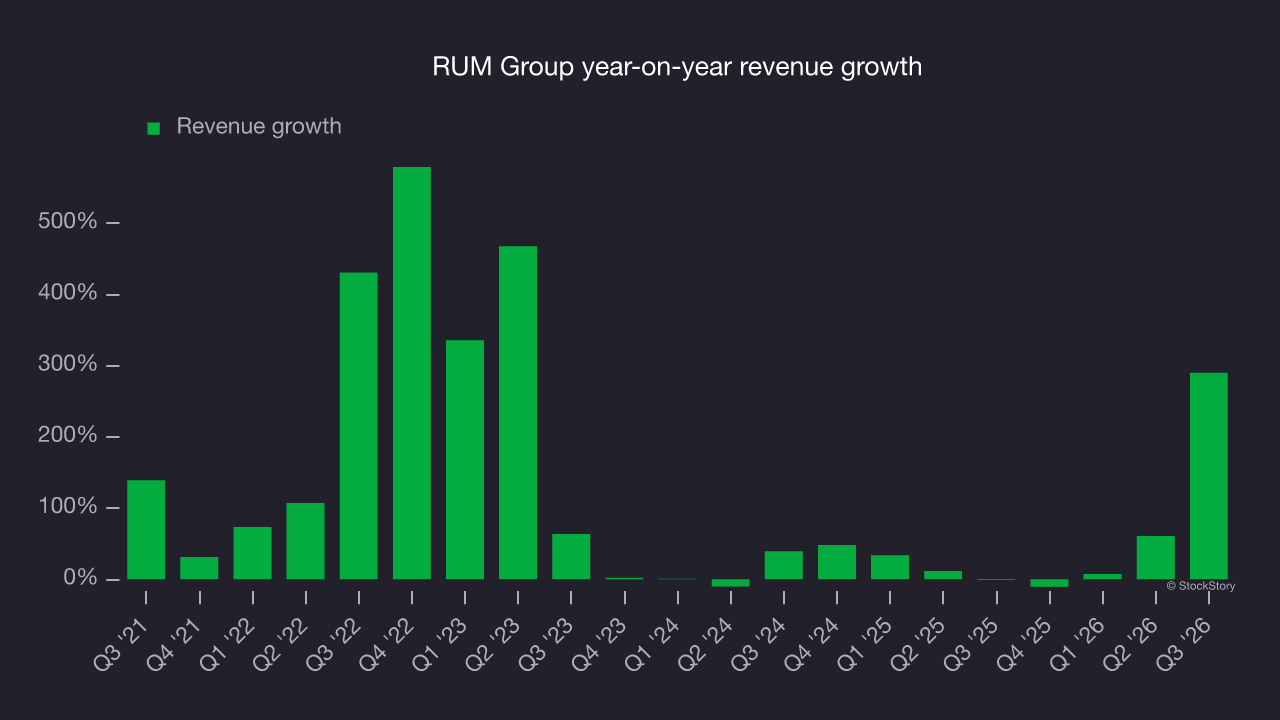
This quarter, RUM Group reported year-on-year revenue growth of 290%, and its $96.58 million in revenue beat Wall Street’s consensus estimates by 8.9%.
Looking ahead, sell-side analysts expect revenue to grow 185% over the next 12 months, according to S&P, an improvement versus the last two years. This strong projection implies its newer products and services will fuel better revenue performance.
Adjusted operating margin
Adjusted operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses, everything from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies because it excludes non-recurring expenses, interest on debt and taxes.
RUM Group’s high expenses have contributed to an average adjusted operating margin of negative 102% over the last five years. Unprofitable business services companies require extra scrutiny because they may be vulnerable in a downturn. The business’s ability to endure a full cycle is uncertain.
On the positive side, RUM Group’s adjusted operating margin rose by 3.6 percentage points over the last five years, as its revenue growth provided operating leverage. Still, it will take much more for the company to reach long-term profitability.
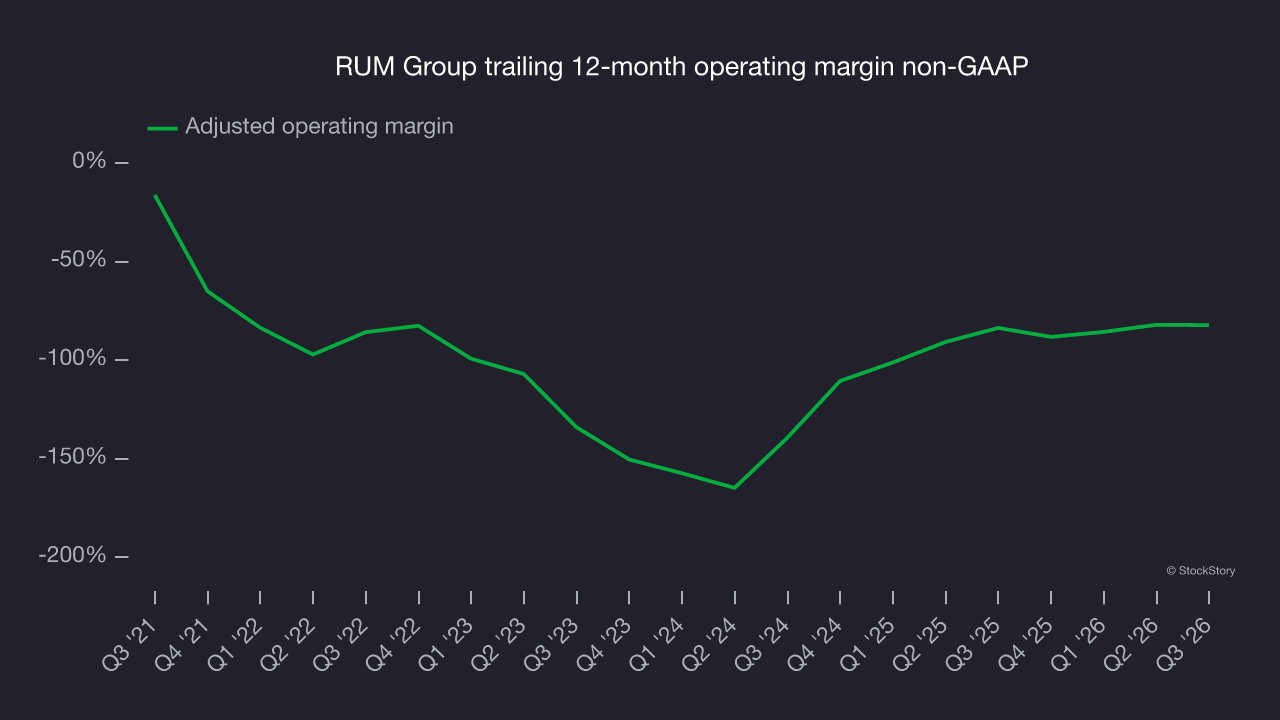
In Q3, RUM Group generated a negative 81.1% adjusted operating margin.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share, or EPS, points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Although RUM Group’s full-year earnings are still negative, it reduced its losses and improved its EPS by 5.1% annually over the last four years. The next few quarters will be critical for assessing its long-term profitability.
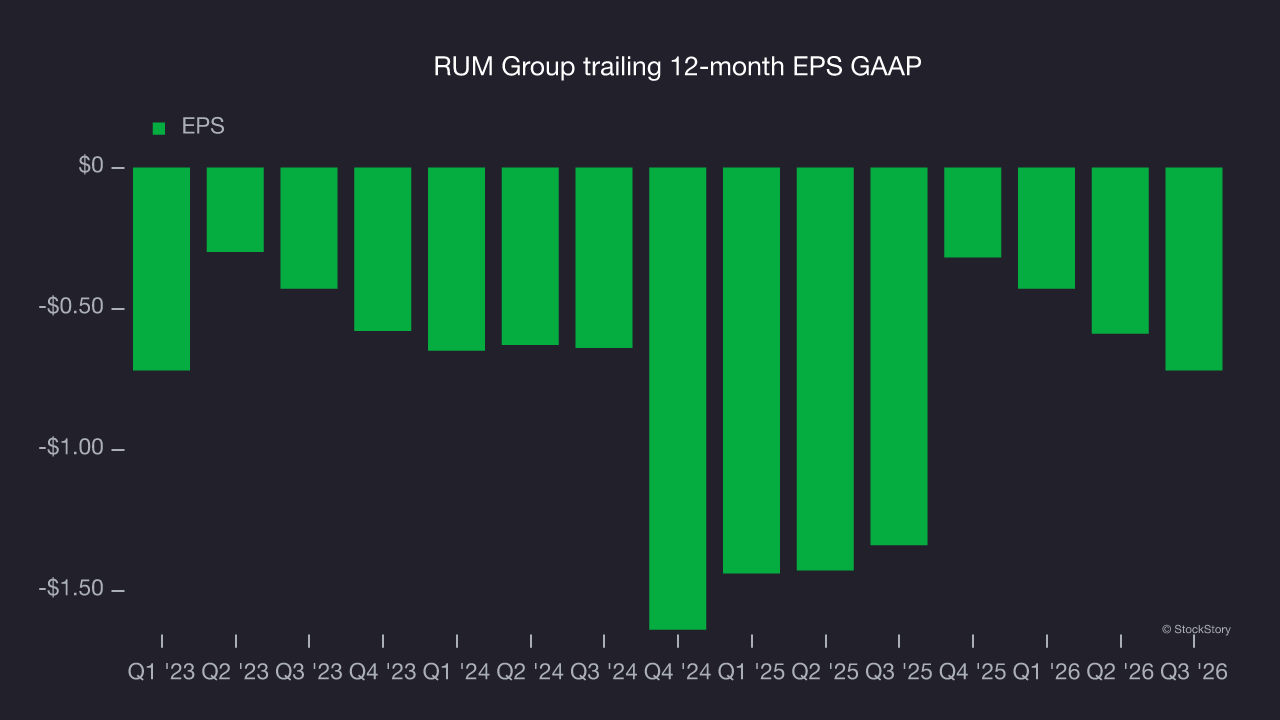
As with revenue, examining EPS over a shorter period can reveal changes in the business.
For RUM Group, its two-year annual EPS declines of 6.1% show it’s continued to underperform. These were poor results.
In Q3, RUM Group reported EPS of negative $0.19, down from negative $0.06 in the same quarter last year. This result missed analysts’ consensus estimates. Over the next 12 months, Wall Street expects RUM Group to narrow its losses. Analysts forecast its full-year EPS will improve from negative $0.72 to negative $0.46, according to S&P.
Key takeaways from RUM Group’s Q3 results
RUM Group’s quarter was solid. Revenue and adjusted EBITDA came in well ahead of analysts’ consensus estimates, although GAAP EPS missed. Shares rose 2.1% to $5.29 immediately after the results.
For investors considering RUM Group, the latest quarter is only one piece of the longer-term business quality picture. Quality, when combined with valuation, can help determine if the stock is a buy. Read more in our full research report here (it’s free).