


The Zhitong Finance App learned that after experiencing a historic sharp decline in the exchange rate of the euro against the British pound, options traders are planning a further rebound in the euro, betting that the euro had previously taken into account the risks surrounding the situation in France. As an indicator of market positions and sentiment, EUR/GBP risk reversal options (Risk Reversals) have risen to the most bullish level for the euro since the beginning of October, indicating that the market's demand for upward exposure to the euro is increasing.
Currently, the EUR/GBP exchange rate is around 0.8365, which is about 0.6% higher than the recent low. Previously, the pair had fallen about 3% from its high in late September.
Van Luu, head of global currency and fixed income solutions strategy at Russell Investments (Russell Investments), said: “The French risk pessimism that the market takes into account the price of the euro is excessive.” He added that the resilience shown by the British economy has been fully reflected in the British pound exchange rate, and compared to the British pound, the euro exchange rate has deviated from the reasonable level implied by relative interest rates.
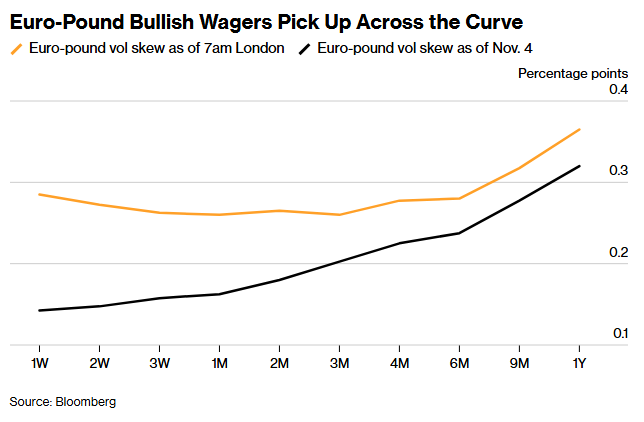
EUR/GBP bullish bets are heating up across the board over different timeframes
Between September 25 and October 30, the decline in the EUR/GBP exchange rate was among the top 1% of all 25-day trading windows in the past five years, and the frequency of daily declines actually set a record. October was also the pair's worst performing month since July 2022, further fueling market expectations that its trend might face a technical rebound.
There are two main factors driving the euro's decline. First, concerns raised by France's fiscal situation are dragging down European assets, and the market is worried that the French government will not be able to effectively control the growing burden of public finances. Meanwhile, the UK's economic growth showed resilience, signs of stabilization in the labor market, and mitigation of political risks, which provided support for the pound.
French fiscal pressure continues to ferment, becoming an important drag on the euro's recent weak performance. France is not only facing a high fiscal deficit and rising government financing costs, but the fragmentation of the political landscape has also impeded the implementation of fiscal consolidation measures. Eurozone finance ministers have previously urged France to pass a credible 2027 budget to restore investor confidence. At the time, the yield on French 10-year treasury bonds rose to a 25-year high, and market concerns about France's fiscal deficit, political differences, and future large-scale debt issuance continued to heat up.
Bank of France Governor Emmanuel Moulin also said on the 4th of this month that France must rely on domestic policies to resolve its own financial problems, and cannot expect the ECB to resolve the crisis. He pointed out that political uncertainty is an important factor driving up the risk premium on French treasury bonds, and passing the 2027 national budget will be a key first step in restoring market confidence and easing financial market pressure.
Van Luu said that although France's fiscal situation is still serious, the basic scenario judgment of Russell Investments is that the French budget will eventually be passed. Furthermore, the ECB has a variety of policy tools that can limit further increases in market pressure. However, whether France can successfully pass the budget, and whether the government can actually promote fiscal consolidation, will still be important variables affecting the trend of the euro.
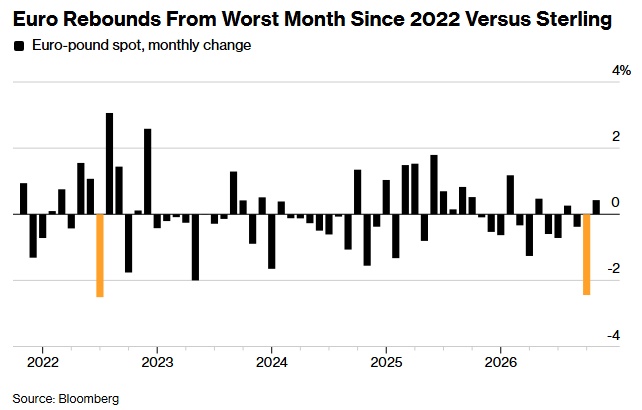
EUR/GBP rebounds from its worst monthly performance since 2022
Compared to the fiscal and political pressure faced by France, the British economy has recently shown some resilience. According to data released by the UK Office for National Statistics, in the three months ending August 2026, the UK economy grew 0.7%; the gross domestic product (GDP) grew 0.1% month-on-month in August. At the same time, the UK labor market also showed signs of stabilization: in the three months ending August, the unemployment rate fell to 4.7% from 4.9% previously, and the number of salaried workers increased by 13,000 in September. The Composite Purchasing Managers' Index (PMI) rose to 52.9 in October, hitting an eight-month high, and both manufacturing and service activity improved.
The performance of the UK economy was better than previously expected, which also changed the market's judgment on the Bank of England's monetary policy path to a certain extent. The Bank of England announced on November 5 that it would raise the benchmark interest rate by 25 basis points to 4%. The Monetary Policy Committee passed this decision with an 8-1 vote. The Bank of England pointed out that the UK consumer price index (CPI) rose 3.5% year on year in September. Against the backdrop of continued high energy prices, inflation is expected to rise to about 5% in mid-2027. Meanwhile, recent economic activity has performed better than expected, and the labor market is showing signs of stability, increasing the risk that rising energy prices will spread to wider inflation.
The Bank of England's interest rate hike also highlights the difference in the interest rate environment between the British pound and the euro. The ECB previously raised the deposit mechanism interest rate by 25 basis points to 2.5% in September, while the Bank of England's benchmark interest rate has now risen to 4%. The relatively high level of UK interest rates and the market's expectation that UK interest rates may remain high for a longer period of time provide support for the pound. However, the Bank of England also stressed that future interest rate decisions are not a predetermined path; they will still depend on changes in data such as inflation, wage growth, and economic activity.
Judging from the exchange rate trend, the contrast between France's fiscal risk and the resilience of the British economy has been fully reflected in the EUR/GBP exchange rate. Mitsubishi UFJ Financial Group (MUFG) pointed out in the foreign exchange outlook released in November that the British pound has recently benefited from better-than-expected growth in the UK and the rise in market expectations for tighter monetary policy in the UK. The agency expects the EUR/GBP exchange rate to be around 0.84 by the end of the fourth quarter of 2026, 0.85 by the end of the first quarter of 2027, and 0.86 and 0.87 at the end of the second quarter and the end of the third quarter, respectively, indicating its judgment that the currency is gradually recovering in the medium term.
Van Luu said Russell Investments is tactically buying EUR/GBP and expects the cross exchange rate to rise 3% to 4% over the next three to six months. He pointed out that the company preferred to express its judgment on the rebound of the euro by going long against the British pound rather than the euro against the dollar, because the EUR/GBP currency pair was less affected by geopolitical shocks.
It should be noted that the EUR/GBP rebound logic does not mean that France's fiscal risk has disappeared, nor does it mean that the supporting factors of the British pound are being reversed. Whether the French budget can be successfully passed, whether UK inflation will further raise interest rates, and future policy differentiation between the European Central Bank and the Bank of England may all affect the subsequent trend of this currency pair. For the options market, the risk reversal indicator turned bullish for the euro, reflecting more investors' reassessment of the downside risk of the euro and bets on recovering from extreme depreciation rather than confirmation of a trend reversal.