


Wrapping up Q3 earnings, we look at the numbers and key takeaways for the maintenance and repair distributors stocks, including Transcat (NASDAQ:TRNS) and its peers.
Supply chain and inventory management are themes that grew in focus after COVID wreaked havoc on the global movement of raw materials and components. Maintenance and repair distributors that boast reliable selection and quickly deliver products to customers can benefit from this theme. While e-commerce hasn’t disrupted industrial distribution as much as consumer retail, it is still a real threat, forcing investment in omnichannel capabilities to serve customers everywhere. Additionally, maintenance and repair distributors are at the whim of economic cycles that impact the capital spending and construction projects that can juice demand.
The 9 maintenance and repair distributors stocks we track reported a favorable Q3. As a group, revenues beat analysts’ consensus estimates by 2.6%.
In light of this news, share prices of the companies have held steady as they are up 3.5% on average since the latest earnings results.
Best Q3: Transcat (NASDAQ:TRNS)
Serving the pharmaceutical, industrial manufacturing, energy, and chemical process industries, Transcat (NASDAQ:TRNS) provides measurement instruments and supplies.
Transcat reported revenues of $97.09 million, up 18% year on year. This print exceeded analysts’ expectations by 5%. Overall, it was an exceptional quarter for the company with a beat of analysts’ EPS estimates and a solid beat of analysts’ EBITDA estimates.
"Our fiscal second quarter results demonstrate strong execution across each pillar of our core strategy: driving strong Service organic revenue growth, expanding Service gross margins, executing strategic acquisitions, and growing Rentals consistently,” said Jaime Irick, President and CEO. “Fiscal second quarter 2027 marked our seventieth consecutive quarter of Service revenue growth. Strength in our Calibration business lifted Service revenue 23%, including 16% Service organic revenue* growth, and drove 220 bps of year over year Service gross margin expansion, up from 90 bps in the first quarter. Distribution revenue grew 10%, fueled by continued strength in Rentals and Product sales."
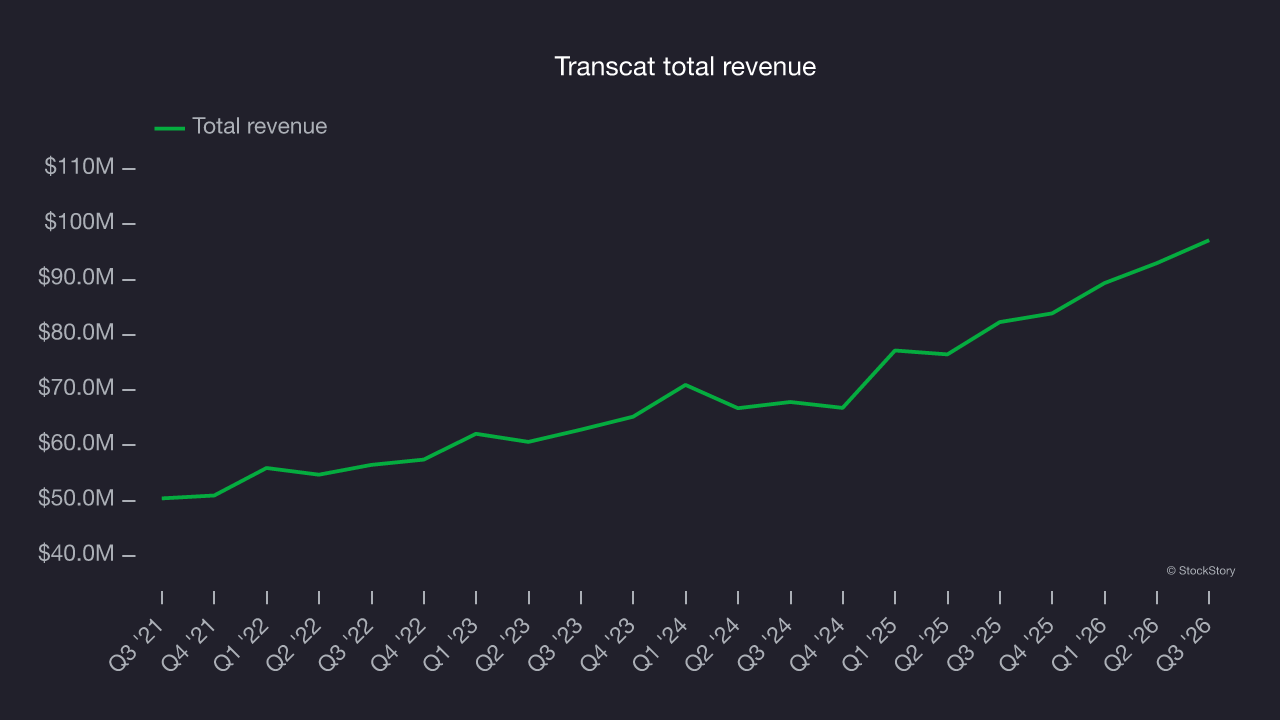
Interestingly, the stock is up 19.4% since reporting and currently trades at $106.86.
Is now the time to buy Transcat? Access our full analysis of the earnings results here, it’s free.
WESCO (NYSE:WCC)
Based in Pittsburgh, WESCO (NYSE:WCC) provides electrical, industrial, and communications products and augments them with services such as supply chain management.
WESCO reported revenues of $7.23 billion, up 16.6% year on year, outperforming analysts’ expectations by 5.1%. The business had an exceptional quarter with a solid beat of analysts’ organic revenue estimates and a solid beat of analysts’ EBITDA estimates.
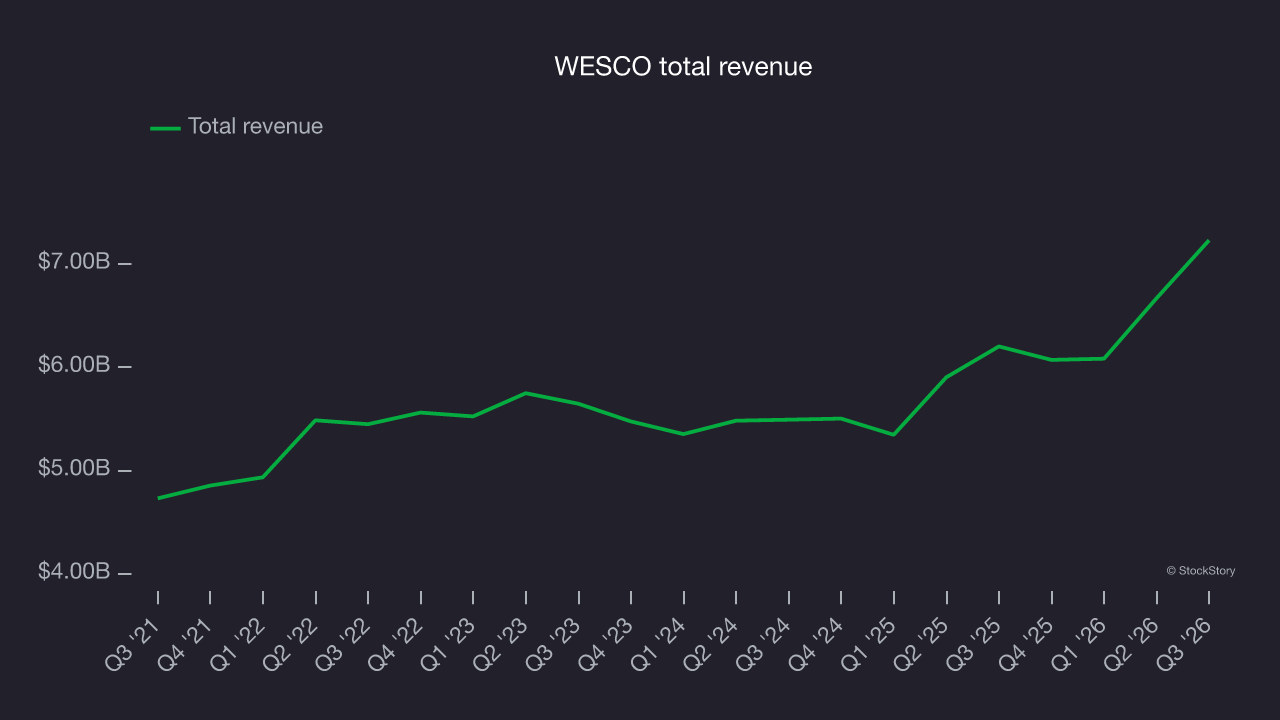
Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 8.8% since reporting. It currently trades at $316.81.
Is now the time to buy WESCO? Access our full analysis of the earnings results here, it’s free.
Weakest Q3: DXP (NASDAQ:DXPE)
Founded during the emergence of Big Oil in Texas, DXP (NASDAQ:DXPE) provides pumps, valves, and other industrial components.
DXP reported revenues of $587.2 million, up 14.3% year on year, in line with analysts’ expectations. It was a sluggish quarter as it posted a significant miss of analysts’ EPS estimates and a miss of analysts’ EBITDA estimates.
DXP delivered the weakest performance against analyst estimates among its peers. As expected, the stock is down 1.9% since the results and currently trades at $155.40.
Read our full analysis of DXP’s results here.
Fastenal (NASDAQ:FAST)
Founded in 1967, Fastenal (NASDAQ:FAST) provides industrial and construction supplies, including fasteners, tools, safety products, and many other product categories to businesses globally.
Fastenal reported revenues of $2.46 billion, up 15.5% year on year. This print surpassed analysts’ expectations by 1%. It was a solid quarter as it also logged a beat of analysts’ EPS estimates.
The stock is up 6% since reporting and currently trades at $54.53.
Read our full, actionable report on Fastenal here, it’s free.
W.W. Grainger (NYSE:GWW)
Founded as a supplier of motors, W.W. Grainger (NYSE:GWW) provides maintenance, repair, and operating (MRO) supplies and services to businesses and institutions.
W.W. Grainger reported revenues of $5.18 billion, up 11.3% year on year. This result beat analysts’ expectations by 2.1%. Overall, it was a very strong quarter as it also put up a solid beat of analysts’ organic revenue estimates and full-year EPS guidance beating analysts’ expectations.
The stock is up 5.6% since reporting and currently trades at $1,476.
Read our full, actionable report on W.W. Grainger here, it’s free.
Market update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Top 5 Growth Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.