


- Elkem ASA released third quarter 2026 results, with revenue of NOK 3,587 million and net income of NOK 319 million, compared with NOK 29 million a year earlier.
- The quarter showed materially stronger earnings per share at NOK 0.88 despite slightly lower revenue, which points to more efficient profitability in Elkem's operations.
- We will now look at how this stronger third quarter profitability shapes Elkem's existing investment narrative and earnings mix.
Compare Elkem's profitability shift with other materials players by scanning our hand picked list of solid balance sheet and fundamentals (194 results) that pair earnings power with sturdier finances.
Elkem Investment Narrative Recap
To own Elkem, you need to believe the shift toward higher margin silicon products, foundry alloys and carbon solutions, highlighted in the analyst consensus Narrative on Simply Wall St, can translate into more resilient profitability even when end markets like automotive and construction are soft. The third quarter jump in net income and earnings per share, despite slightly lower revenue, supports that efficiency story but does not remove demand risk.
The most immediate catalyst is whether this improved earnings mix and cost control can carry into coming quarters while the nine month period still shows a loss. The biggest near term risk is that weak silicon and DMC pricing or underperforming high cost assets, such as Iceland, cap further margin progress and keep group returns subdued.
The fresh data point that really matters here is the third quarter 2026 earnings release itself. Revenue of NOK 3,587 million was modestly below the prior year level while net income stepped up to NOK 319 million, lifting basic earnings per share to NOK 0.88. That pattern points to Elkem extracting more profit from each krone of turnover in the period.
Across the first nine months, the business still reported a net loss of NOK 422 million and a basic loss per share of NOK 0.88. That gap between a stronger single quarter and a weak year to date underlines the execution challenge behind the catalysts analysts see, especially around sustaining higher margins in the Silicon division while managing interest coverage and exposure to lower demand in key end markets.
Elkem's narrative projects NOK 18.3b revenue and NOK 2.6b earnings by 2029. That profile assumes 4.7% yearly revenue growth and requires earnings to rise by about NOK 2.2b from NOK 418.0m today.
Uncover why Elkem's fair value indicates a 20% potential upside to its current price before the discount closes.
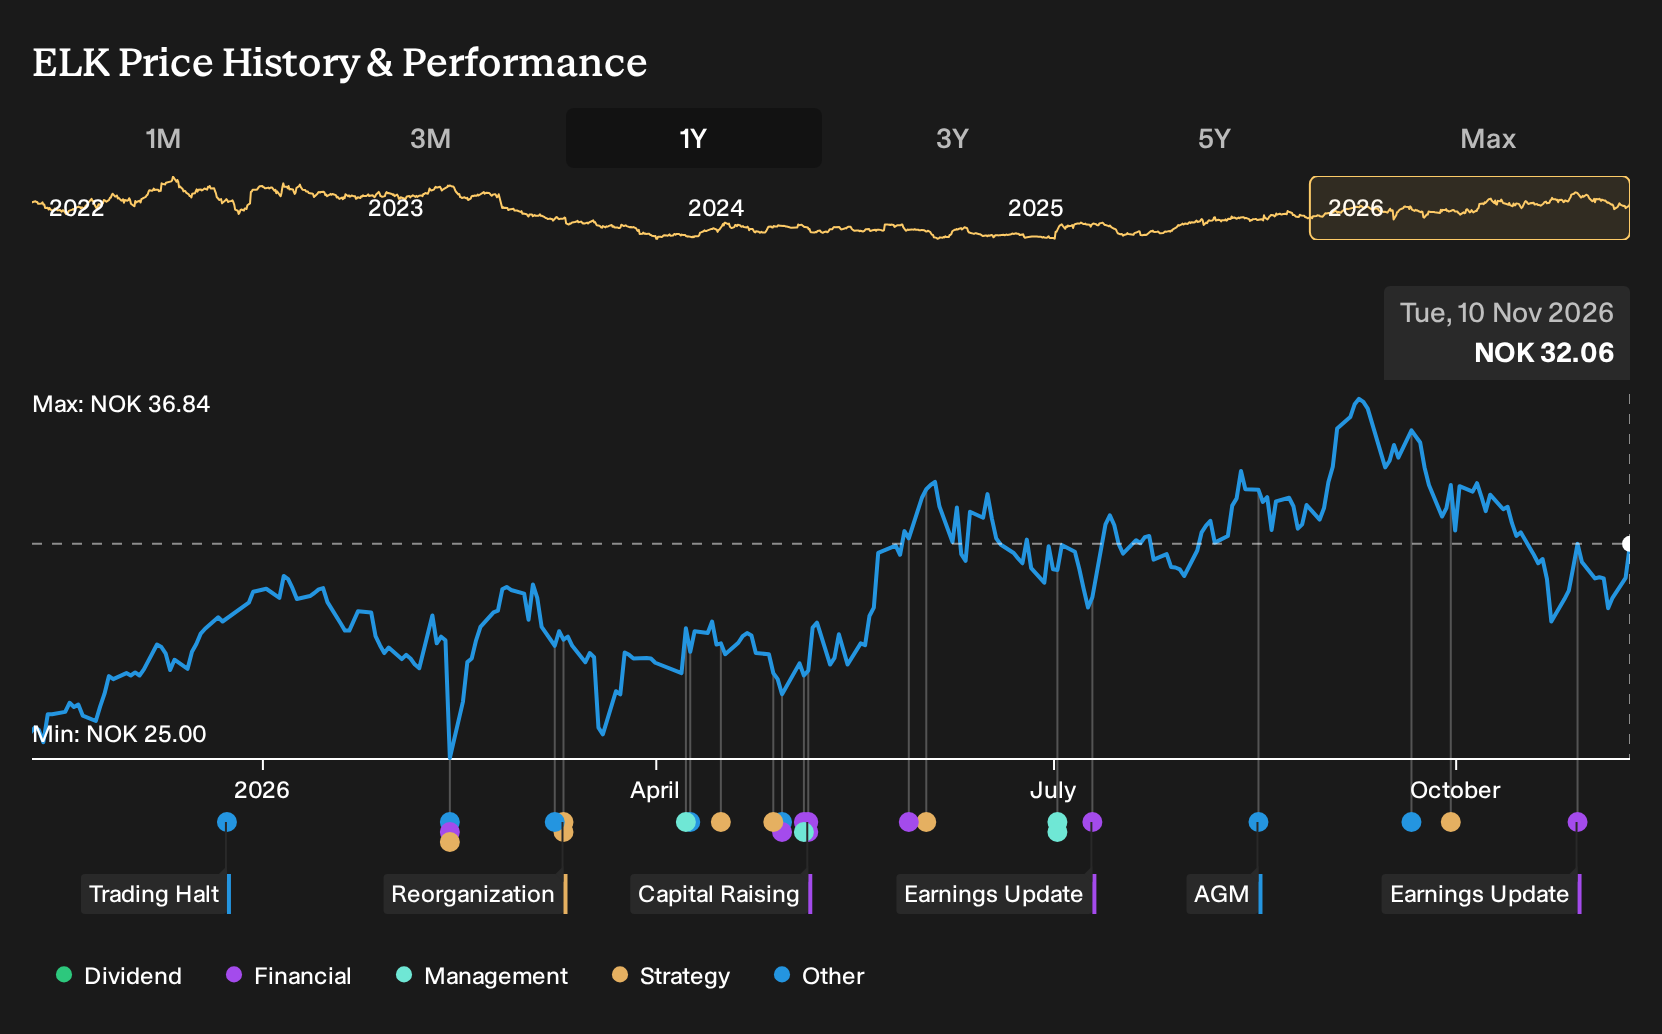
Exploring Other Perspectives
One alternate view focuses on weak silicon pricing as the key issue for Elkem. The most pessimistic analysts were only pencilling in about NOK 17.4b revenue and NOK 1.5b earnings by 2029 before these third quarter numbers. That paints a much slower earnings climb. Use this latest report as a prompt to compare those different narratives yourself.
Explore 3 other Elkem fair value estimates, including one that suggests it could be worth just NOK31.20.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Elkem research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Elkem. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Elkem's overall financial health at a glance.
Looking For More Ideas Beyond Elkem?
If Elkem's latest quarter has you rethinking where earnings quality and balance sheet strength really come from, it can help to widen the search and line it up against other listed businesses using the Simply Wall St stock screener.
- For investors who care most about valuation and business quality together, scan a focused set of opportunities through the 200 high quality undervalued stocks that combine robust fundamentals with appealing pricing.
- If resilience is the priority, especially after a choppy period for profits, filter for companies with steadier risk profiles by using the 208 resilient stocks with low risk scores to see which ones clear that bar.
- When you want to spot strong operators that are not yet widely talked about, work through the 565 high quality undiscovered gems and see which fundamentals-based stories deserve a closer look next.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com