


- Graham Corporation reported second quarter fiscal 2027 results with sales of US$69.76 million and net income of US$4.64 million, as well as higher earnings per share compared with the same period a year earlier. The company also reaffirmed full year net sales guidance of US$285 million to US$295 million.
- The latest report highlighted a sizeable backlog linked to defense, space and energy work that management continues to convert into revenue while maintaining its full year outlook. This points to operational execution as a key driver of the current business story rather than new end market exposure.
- We will now look at how Graham's reaffirmed full year sales guidance might reshape the broader investment narrative around backlog conversion.
Scan beyond Graham's backlog story and compare it with other contractors converting long term projects into revenue using our hand picked list of solid balance sheet and fundamentals (24 results)
Graham Investment Narrative Recap
To own Graham, you need to believe the record backlog in defense, space and energy can keep turning into steady sales and better profitability. The recent quarter, with higher sales and earnings per share than a year ago, supports that execution story. The key short term catalyst remains margin progress as that backlog flows through.
The biggest near term risk is that expectations have already moved ahead of delivery, with the analyst consensus Narrative on Simply Wall St highlighting a rich P/E and reliance on margin expansion toward mid teens EBITDA. The latest results help, but do not remove the possibility that future guidance or profitability underwhelms what is currently priced in.
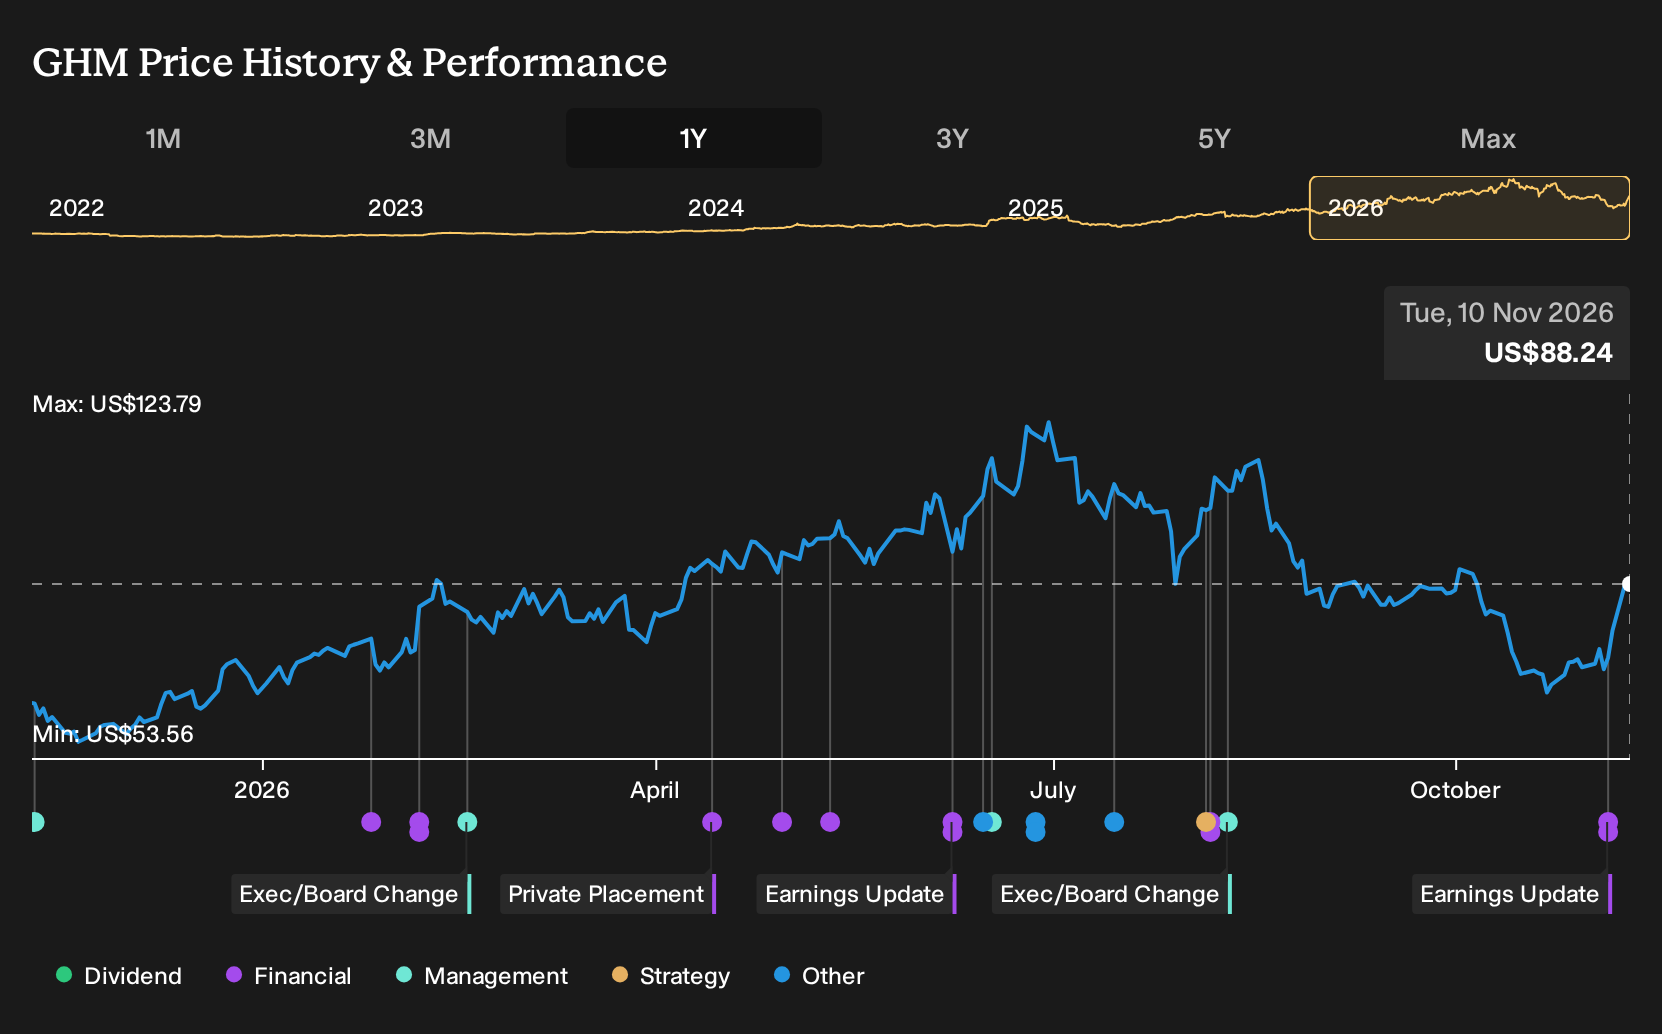
The reaffirmed full year fiscal 2027 net sales guidance of US$285 million to US$295 million is the announcement that matters most here. It links directly to whether Graham can translate its roughly US$561 million backlog into revenue at the pace the market is watching. Holding guidance signals management still sees that conversion path as intact.
For you as an investor, the catalyst is simple. If Graham keeps hitting these sales brackets while working toward higher margins, the backlog driven thesis around defense and space programs stays on track. If revenue timing or cost control slip against this guidance range, the high valuation and sensitivity to any disappointment become much more important.
Graham's current analyst narrative assumes revenue reaches US$367.4 million and earnings of US$37.7 million by 2029, based on forecast annual revenue growth of 12.0% and an earnings increase of about 3.2x from US$11.8 million today.
Uncover why Graham's fair value indicates a 46% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Not every analyst sees backlog conversion as the main swing factor for Graham Corporation. Some of the lowest estimates focused on margin pressure instead, even while still penciling in about US$375.2 million of revenue and US$38.6 million of earnings by 2029. Those forecasts came before this quarter’s guidance, so you may see opinions shift again.
Explore 2 other Graham fair value estimates, including one that suggests as much as 68% downside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Graham research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Graham. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, making it easy to evaluate Graham's overall financial health at a glance.
Looking for more investment ideas beyond Graham?
Once you have a handle on Graham, it can help to widen the lens and compare it with other businesses that fit different roles in your portfolio using the Simply Wall St Screener.
- If you want potential mispricing on your side, scan for quality companies that look cheap on the numbers with our 35 high quality undervalued stocks.
- For steadier income focused holdings, review stocks that combine higher yields with resilient payouts using the 5 dividend fortresses.
- When capital protection matters most, filter for businesses with stronger balance sheets and fundamentals through the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com