


Seagate Technology Holdings (STX) just rolled out its FireCuda Forge drive, the first hard drive built on the new Alkemi platform, combining SSD-style responsiveness with traditional HDD capacity.
Recent trading tells a mixed story. Seagate Technology Holdings’ share price has retreated sharply in the near term, with the 7 day move down 17.28% and the 30 day share price return down 35.94%. However, the 1 year total shareholder return of 75.20% and the very large 3 year total shareholder return show that longer term holders have still seen substantial gains as investors weigh AI driven storage demand against higher expectations built into the valuation.
Scan Seagate Technology Holdings peers riding the same AI and storage wave by reviewing our hand picked 53 AI infrastructure stocks alongside this FireCuda Forge launch story.
Seagate Technology Holdings has just swung from sharp gains over three years to a steep pullback in a month. Are traders simply cooling on the AI story, or has the share price run ahead of the business fundamentals?
Most Popular Narrative: 57% Undervalued
Against a last close of $501.62, the most followed narrative on Seagate Technology Holdings pegs fair value at $1,158.73, which frames this recent pullback as a potential valuation gap rather than just fading enthusiasm.
The arithmetic of that shows up in the supply gap. Nearline HDD supply is expected to fall roughly 300 exabytes short of demand in 2026, a 10 to 15% shortfall, widening to something like 400 exabytes in both 2027 and 2028. Blended nearline pricing has been running near $14.30 to $14.90 per terabyte against scenarios that put it meaningfully higher over the next two years.
See why 57 investors see Seagate Technology Holdings as 57% undervalued.
According to isidrohg, an investor in the Simply Wall St Community who wrote the narrative, this undersupply in nearline hard drives and the focus on HAMR are central to the valuation story for Seagate Technology Holdings.
That view ties a 56.7% discount to fair value directly to two moving parts. One is the broad shortage in hyperscale storage capacity. The other is Seagate Technology Holdings pushing more exabytes onto each drive, which the narrative argues lowers unit costs and supports margins even if pricing pressure eventually eases.
The narrative also leans on Simply Wall St modelling, which suggests Seagate Technology Holdings trades around 66.9% below an estimate of its future cash flow value of $1,513.65 using the SWS DCF model. That approach projects future cash flows, then discounts them back using an 8.39% rate to arrive at today’s estimated worth.
Taken together, the community view sketches a business with strong recent earnings growth of 157% over the past year, a net margin of 31.9% and a very high 127.3% return on equity, yet priced as if those cash flows are worth significantly less than the fair value implied by the narrative.
Result: Fair Value of $1,158.73 (UNDERVALUED)
Still, the narrative around Seagate Technology Holdings relies on two fragile points: disciplined capacity management within the duopoly, and successful, on-schedule HAMR execution with key cloud customers.
Find out about the key risks to this Seagate Technology Holdings narrative.
Another View: What Seagate’s P/E Ratio Is Saying
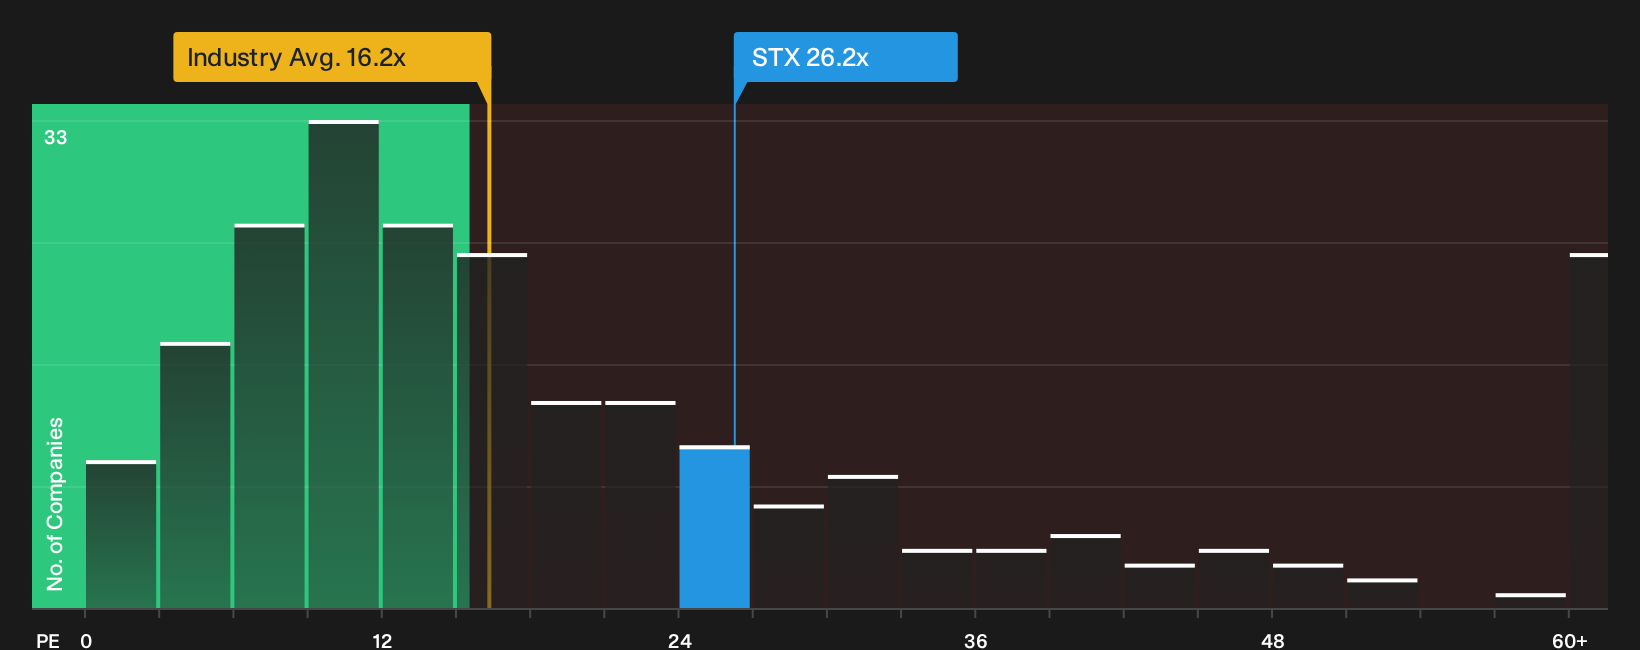
There is a sharp contrast between the Seagate Technology Holdings community narrative and the way the market is currently pricing the stock. On a simple P/E basis of 26.2x, the shares look expensive next to both the global tech sector at 16.2x and Seagate’s peer average at 14.9x. This is occurring even though the fair ratio model points to a much higher 44.9x as a level the market could move toward if sentiment shifted.
That split between today’s richer P/E and a higher fair ratio leaves investors weighing valuation risk against the possibility that the market never fully closes that gap. The open question is which side of that spread you want to lean toward.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages like this can be confusing. Move quickly from opinion to evidence and weigh Seagate Technology Holdings for yourself by checking the 3 key rewards and 2 important warning signs.
Looking for more Seagate Technology Holdings investment ideas?
You have already done the hard work on Seagate Technology Holdings. Do not stop there when a broader watchlist could sharpen your decisions and surface fresh angles.
- Target potential mispricing by scanning a curated set of value opportunities through the 35 high quality undervalued stocks.
- Strengthen portfolio resilience by zeroing in on companies with cleaner finances using the list of solid balance sheet and fundamentals (24 results).
- Spot under-the-radar opportunities early by checking the 20 high quality undiscovered gems before the crowd catches on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com