


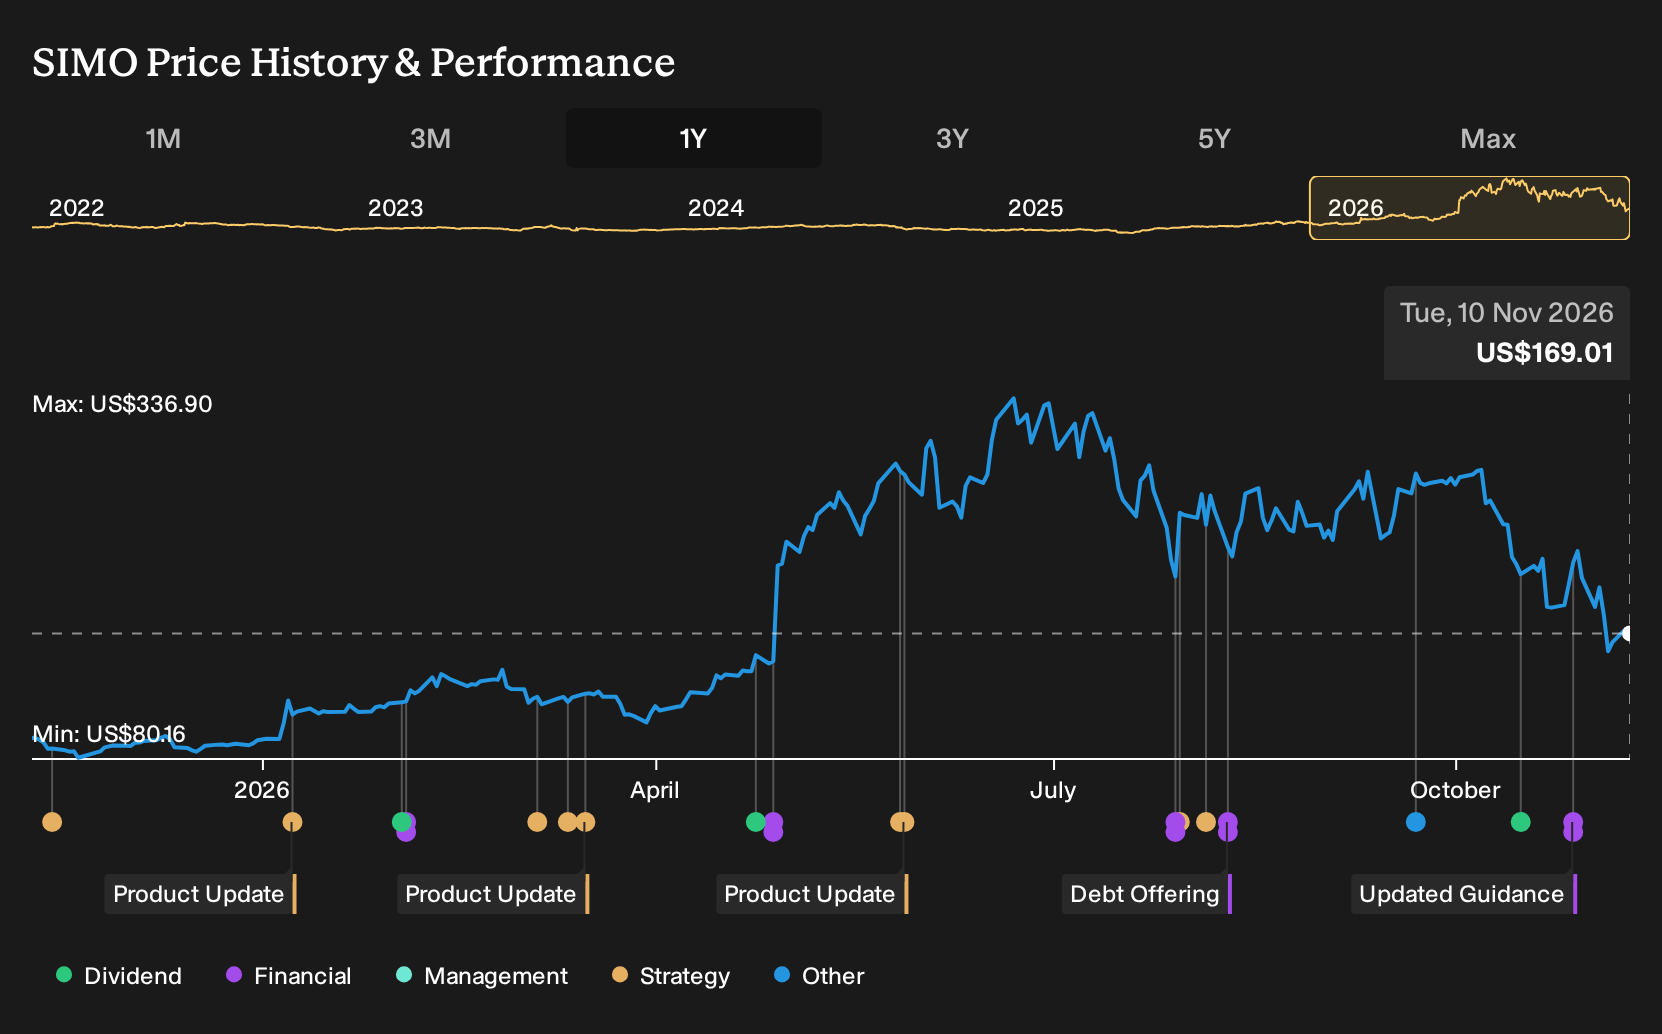
If Silicon Motion Technology looked too hot to touch back in November 2025, the next twelve months put that hesitation under a harsh spotlight. Investors who held Silicon Motion Technology over the past year are up 84.4%, including dividends. At the starting line, you saw bullish analysts leaning into PCIe and UFS momentum and sceptics warning about overvaluation and customer concentration. If you were weighing those arguments then, which specific risks or opportunities would have tipped your call?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Silicon Motion Technology has already moved. Pinpoint other ways to investigate the theme among 53 AI infrastructure stocks.
The Two Stories Investors Were Weighing On Silicon Motion Technology
The shares cost US$94.45 at the start of the period, and you had to pick between two very different stories about what Silicon Motion Technology might deliver next.
The bullish narrative saw a Fair Value of US$105, tied to new PCIe and UFS launches and assumptions that revenue could climb 10.4% a year with profit margins rising from 12.1% to 17.5% by 2028.
The cautious view put Fair Value at US$79, focused on geopolitical trade restrictions and vertical integration risk, with revenue growth at 9.9% but margins easing from 12.1% to 10.8% over the same horizon.
What The Results Changed For Silicon Motion Technology
Silicon Motion Technology spent the period backing its growth story with product launches into AI and enterprise storage, including the MonTitan SSD platform and PCIe Gen5 controllers. These supported the optimistic case for broader, higher value end markets. At the same time, Q3 revenue and profit rose but net margin slipped from 16.2% to 11.7%, which challenged the cleaner margin expansion the bulls had hoped for. Overall, the evidence cut both ways.
The whole debate turned on whether higher spec controllers would translate into both bigger sales and stronger profitability. When you weigh another stock built on a similar thesis, check whether new products show up as higher absolute earnings and a stable or improving net margin rather than just top line growth.
What Today's Silicon Motion Technology Price Is Asking You To Believe
Silicon Motion Technology now trades at US$169 after a 84.4% gain over the past year. The bearish analyst Narrative on Simply Wall St currently puts its Fair Value above that level and roots that view in how the business might scale higher value enterprise, automotive, and AI storage work.
That Narrative effectively asks you to judge whether Silicon Motion Technology can keep turning MonTitan, Enterprise Boot Drive, and Ferri design wins into a broader and more durable earnings base that supports current spending. The key question is whether that shift away from lower end devices can keep delivering the growth the Narrative assumes.
"The main thing that has to go right is that Silicon Motion Technology converts its expanding enterprise, automotive, and AI-focused controller and solution portfolio into a much larger, more diversified revenue base that offsets weakness in consumer devices and justifies higher R&D and operating costs."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Another Way Data Gets Moving
Silicon Motion Technology highlights how crucial storage controllers have become in modern systems.
One step upstream, data still needs reliable pathways before it reaches those controllers.
High performance networking and connectivity hardware ensure traffic flows cleanly into storage infrastructure.
One large infrastructure specialist concentrates on that layer, supplying custom silicon and networking gear.
As computing spreads across clouds, data centers, and private servers, this connective layer becomes a quiet but important adjacent opportunity.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 96% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com