


- Hesai Group reported Q3 2026 sales of CNY 1,068.29 million and net income of CNY 80.79 million, with lidar shipments rising and newer robotics segments beginning to contribute. Profitability for both the quarter and nine-month period was lower than a year earlier.
- Beyond the headline growth, Hesai Group is leaning heavily on early revenue from its Kosmo 3D data platform and robotic actuation modules. Management now frames these as the next engine for its Physical AI and robotics ambitions.
- We will now look at how this mix of higher Q3 revenue and lower earnings may influence Hesai Group's investment narrative and risk profile.
Scan how Hesai Group's Physical AI push compares with other robotics and automation plays by checking the curated 89 robotics and automation stocks that are also leaning into sensors, data, and actuation.
Hesai Group Investment Narrative Recap
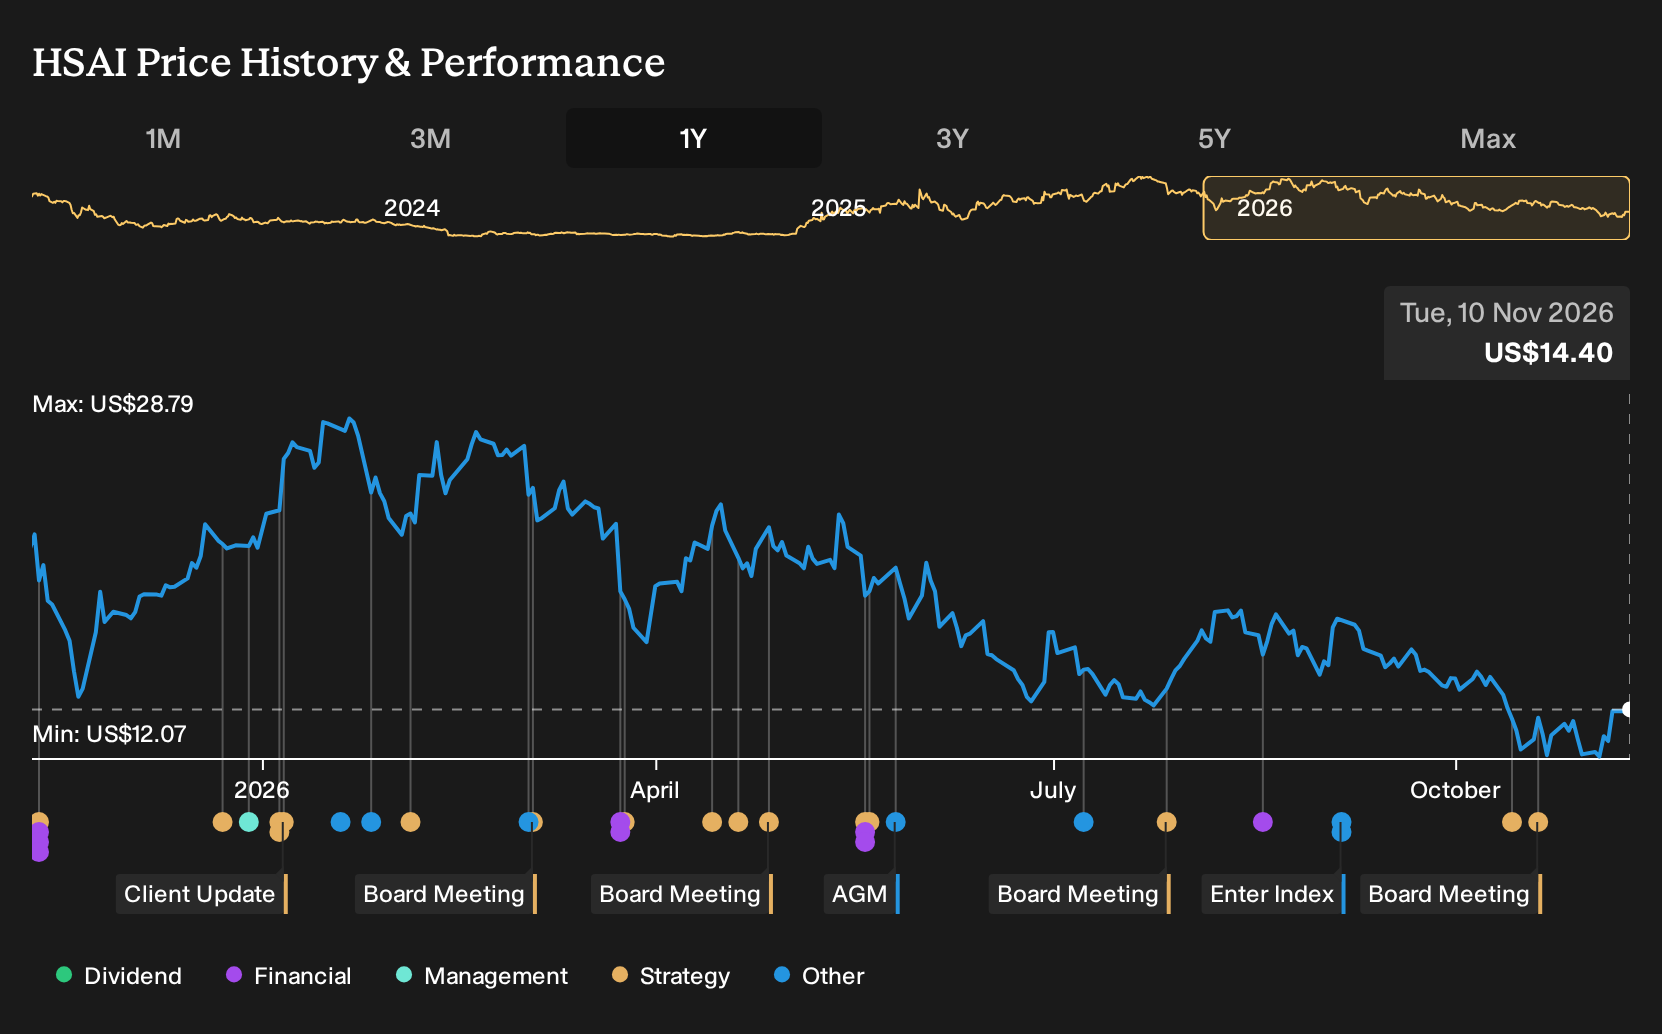
To stay on board with Hesai Group, you need to believe that lidar volume growth and newer Physical AI lines like Kosmo and actuation can eventually support profits, not just revenue records. Q3 2026 showed that tension clearly. Sales reached CNY 1,068.29 million, while quarterly net income and earnings per share from continuing operations sat well below last year.
The short term swing factor is whether lidar pricing and unit volumes can keep blended gross margin close to the roughly 40% level management has discussed in recent commentary from the analyst consensus Narrative on Simply Wall St. The immediate risk is that Strategic Growth Initiatives keep generating modest sales and operating losses, which could extend the pressure already visible in the weaker CNY 80.79 million quarterly profit.
The most relevant recent update is management’s plan for Strategic Growth Initiatives, including Kosmo and humanoid robot actuation modules, to reach about CNY 700 million of revenue and breakeven in 2027. Q3 already showed early traction, with SGI revenue around CNY 45 million and a meaningful operating loss, so the latest earnings put some hard numbers around that path.
For you as a Hesai Group shareholder, the connection is straightforward. The Physical AI push is where a lot of future upside in the analyst consensus Narrative on Simply Wall St sits. Yet it is also what drags on current earnings. Every quarter like Q3 2026 that delivers higher lidar shipments but softer profitability will test confidence that SGI can scale without eroding cash generation from the core lidar franchise.
Hesai Group's narrative projects CNY 8.2b revenue and CNY 1.5b earnings by 2029. This aligns with analyst assumptions for 35.0% yearly revenue growth and implies an earnings increase of about 3x from CNY 498.2m today.
Uncover how Hesai Group's fair value indicates a 77% potential upside to its current price that may be short-lived.
Exploring Other Perspectives
Some of the most optimistic analysts frame Hesai Group’s Physical AI push as a potential accelerator. Before this Q3 update, the bullish narrative leaned on revenue growth assumptions of 54% a year and earnings reaching about CNY 2.3b by 2029. You can now ask whether this earnings miss nudges those forecasts lower or simply delays them.
Explore 6 other Hesai Group fair value estimates, including one that suggests as much as 149% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Hesai Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hesai Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hesai Group's overall financial health at a glance.
Looking for more Hesai Group style ideas?
If the Hesai Group story has you thinking about where else lidar, automation, or solid fundamentals could line up with your portfolio, it can help to scan a broader watchlist using the Simply Wall St Screener.
- If capital preservation and smoother rides matter most to you, start with a basket of 30 resilient stocks with low risk scores that score well on our risk checks and may suit a steadier approach.
- For investors hunting for quality at a reasonable price, broaden your watchlist with a curated 35 high quality undervalued stocks based on strong fundamentals and discounted valuations.
- If you care about balance sheet strength as much as the story, focus on a list of solid balance sheet and fundamentals (24 results) that can help you filter for companies with healthier leverage and liquidity profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com